


Why Church & Dwight is on investors’ radar now
Church & Dwight (CHD) drew fresh attention after reporting higher third quarter net income and earnings per share year over year, and lifting full year EPS guidance to approximately 20% growth at $3.63.
Recent trading has backed up that earnings story. The share price is up 13.7% over the past month and 29.8% year to date, while the 1 year total shareholder return of 25.9% points to momentum that has been building rather than fading.
Scan how Church & Dwight’s upgraded guidance compares with other consumer companies showing fresh earnings momentum inside the curated 33 high quality undervalued stocks.
Bulls see Church & Dwight’s rally as a clean reflection of stronger earnings and fresh buyback firepower. Bears point to modest sales guidance. Which story does the current valuation actually support?
Most Popular Narrative: 2% Overvalued
On the narrative view, Church & Dwight’s fair value of $105.11 sits just below the latest close at $107.23, which puts more scrutiny on how durable its earnings quality really is under a 7.24% discount rate.
The numbers imply the Church & Dwight share price reflects a market that remains cautious on growth and margin durability despite the company raising its 2026 organic sales, EPS and cash from operations guidance and continuing to target its evergreen model.
See why 13 investors see Church & Dwight as 2% overvalued.
Result: Fair Value of $105.11 (OVERVALUED)
Still, if vitamin gummies stay weak and SG&A remains elevated after exits and acquisitions, Church & Dwight’s earnings narrative could lose some of its shine.
Find out about the key risks to this Church & Dwight narrative.
Another View: Cash Flows Point A Different Way
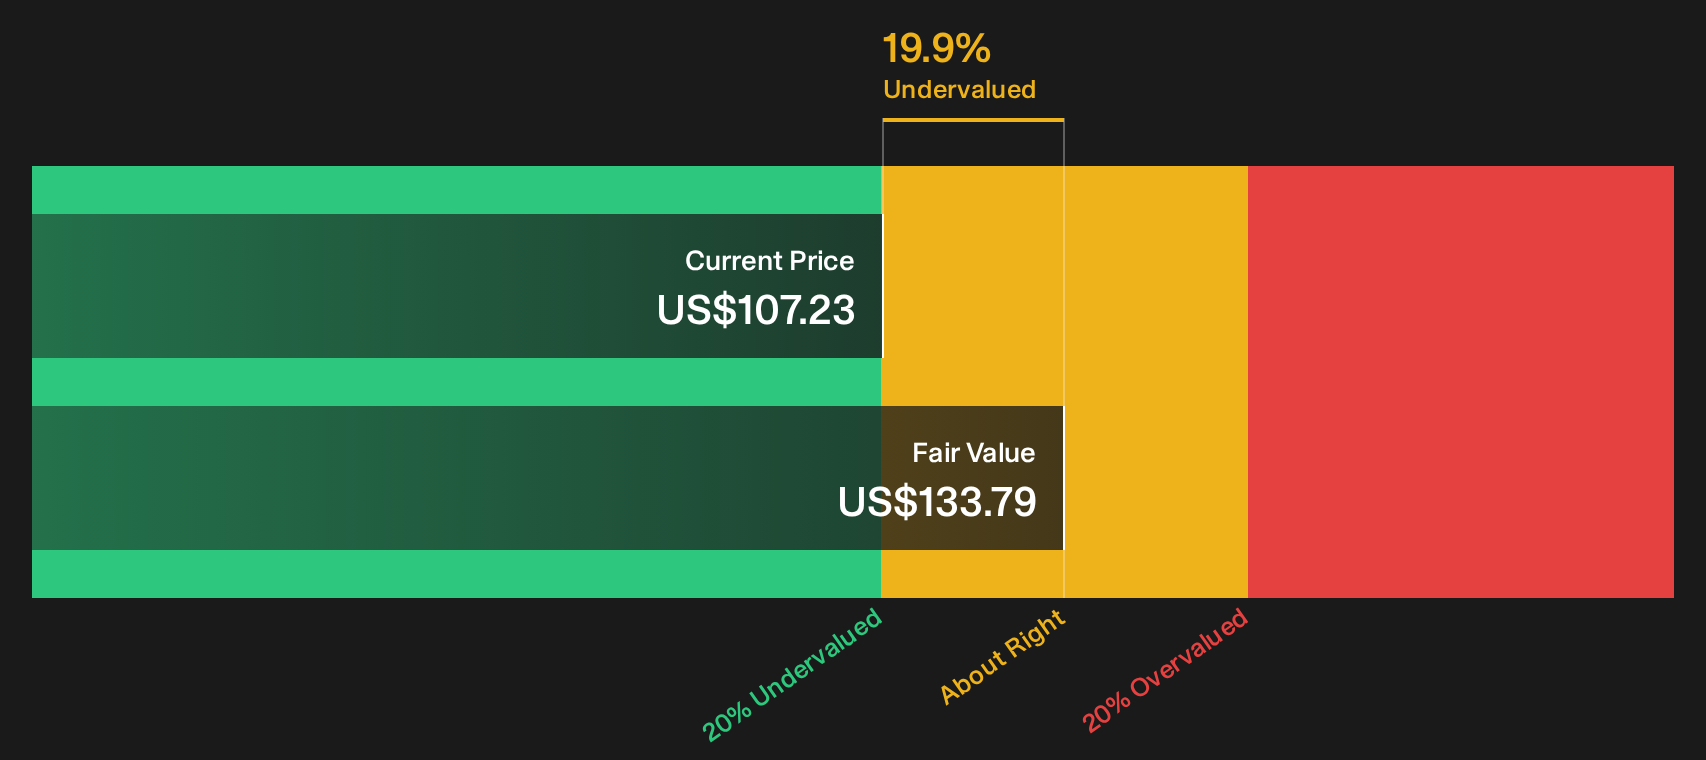
The narrative crowd sees Church & Dwight as 2% overvalued against a $105.11 fair value. Our DCF model tells a different story. On future cash flows, the shares at $107.23 screen about 19.9% below an estimate of $133.79, which raises a simple question for investors: Are earnings forecasts too cautious, or is the cash flow model too generous?
For anyone weighing those two camps, it helps to see how the cash flow work is built rather than just the headline number. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Church & Dwight for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Church & Dwight is split, which is exactly when fresh data can be most useful for you rather than the crowd. To see which potential upsides investors are focusing on, review the 2 key rewards
Looking for more investment ideas beyond Church & Dwight?
If Church & Dwight has sharpened your appetite for quality opportunities, do not stop here. The right shortlist can save you years of trial and error.
- Target dependable compounding potential by scanning a curated pool of financially resilient businesses through the 29 resilient stocks with low risk scores.
- Hunt for mispriced quality by checking companies that pair strong fundamentals with appealing prices inside the 33 high quality undervalued stocks.
- Spot future leaders early by reviewing the 19 high quality undiscovered gems that combine solid financials with lower profile market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com