


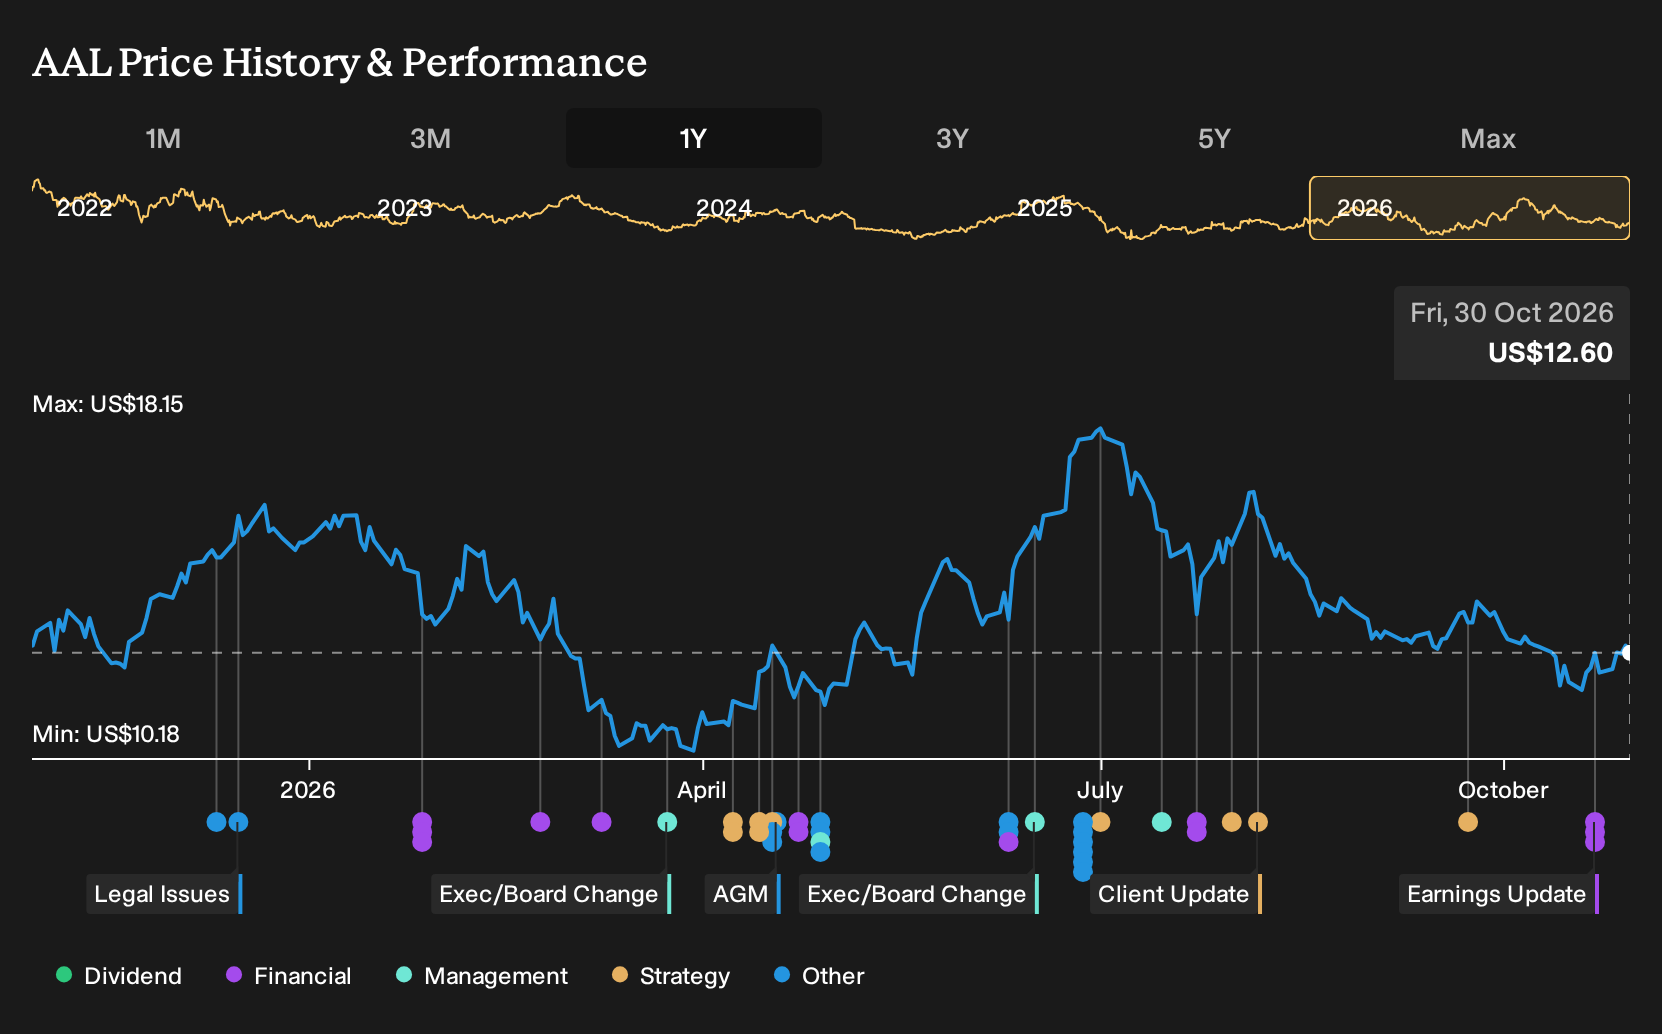
- American Airlines Group reported third quarter 2026 results with revenue of US$16.3b and a net loss of US$269 million, along with updated fourth quarter guidance indicating expected revenue and capacity growth.
- The combination of higher sales and wider losses, together with a lower passenger load factor despite increased capacity, highlights cost pressures and efficiency challenges within American Airlines Group's current operating model.
- We will now look at how American Airlines Group's higher revenue but wider third quarter loss could affect its broader investment narrative.
Scan beyond American Airlines Group and compare its Q3 pressures with airlines that score better on balance sheet strength and efficiency using our hand picked list of solid balance sheet and fundamentals (24 results).
American Airlines Group Investment Narrative Recap
To own American Airlines Group, you need to believe the airline can turn higher passenger volumes and premium focus into consistent profits while carrying a large debt load and volatile fuel costs. The latest quarter shows higher revenue but a wider loss. In the near term, the outlook hinges on tighter cost control and better use of added capacity.
The key short term catalyst is whether American Airlines Group can translate planned fourth quarter revenue and capacity growth into improved unit economics without eroding yields further. The biggest near term risk remains that fuel, interest expense and debt servicing keep absorbing cash, leaving losses elevated even as demand holds up.
The fresh guidance for fourth quarter 2026 is the clearest operational signal to focus on right now. Management expects total revenue to be 19.5% to 22.5% higher and available seat miles to be 5.5% to 6.5% higher. For you, the question is whether that extra flying produces healthier unit revenue and better fixed cost absorption.
Set that against the recent third quarter, where passenger load factor declined to 83.4% despite more capacity and the group still reported a net loss. If American Airlines Group fills more of those incremental seats at reasonable fares and holds non fuel costs in check, the guidance window becomes a useful test of execution and of how quickly losses can narrow.
American Airlines Group's narrative projects US$71.5b revenue and US$1.5b earnings by 2029. This assumes revenue growth of 5.4% per year and an earnings increase of about US$2.0b from current earnings of a US$481.0m loss.
Discover why American Airlines Group's fair value indicates a 22% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts frame American Airlines Group very differently from the baseline. They lean on premium pricing power and loyalty cash flows, and they expect revenue to reach about US$75.1b and earnings around US$3.8b by 2029. Those forecasts were set before this Q3 loss, so you may see those narratives evolve.
Explore 6 other American Airlines Group fair value estimates, including one that suggests as much as 737% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your American Airlines Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for American Airlines Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Airlines Group's overall financial health at a glance.
Looking for more investment ideas beyond American Airlines Group?
Once you have formed a view on American Airlines Group, it can help to widen the lens and compare it with other businesses that better match your risk tolerance and return goals using the Simply Wall St Screener.
- If capital preservation matters most to you, start with companies that aim for steadier balance sheets and milder drawdowns through the 29 resilient stocks with low risk scores.
- If you prefer strong fundamentals that the market may be underrating, scan for mispriced quality using the 33 high quality undervalued stocks.
- If income is your focus, look for payouts above 5% that still aim for resilience in tougher periods through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com