


Antero Midstream has delivered a powerful run over the past few years, and a fresh batch of operational updates has pushed the story back into focus. With the share price now reflecting years of strong total returns, the central question is how well that market value lines up with the earnings the business is generating today.
- Over 5 years, Antero Midstream has returned 174.8%, which puts a lot of past optimism on the table and makes the current valuation more dependent on the staying power of its profit stream.
- Recent operational gains, including higher volumes and a litigation related cash inflow that helped reduce debt, can support cleaner earnings and may influence how investors frame the stock's earnings power against its current P/E level.
- Your read on Antero Midstream is one view; the desks covering it have another. See what analysts think Antero Midstream's shares could be worth.
The stock's next move may depend on whether Antero Midstream's current earnings are strong enough to support the price investors are paying today.
If you are weighing whether Antero Midstream's current earnings justify its price, it can help to compare that trade off with 33 high quality undervalued stocks.
Where Does Antero Midstream Sit on Earnings?
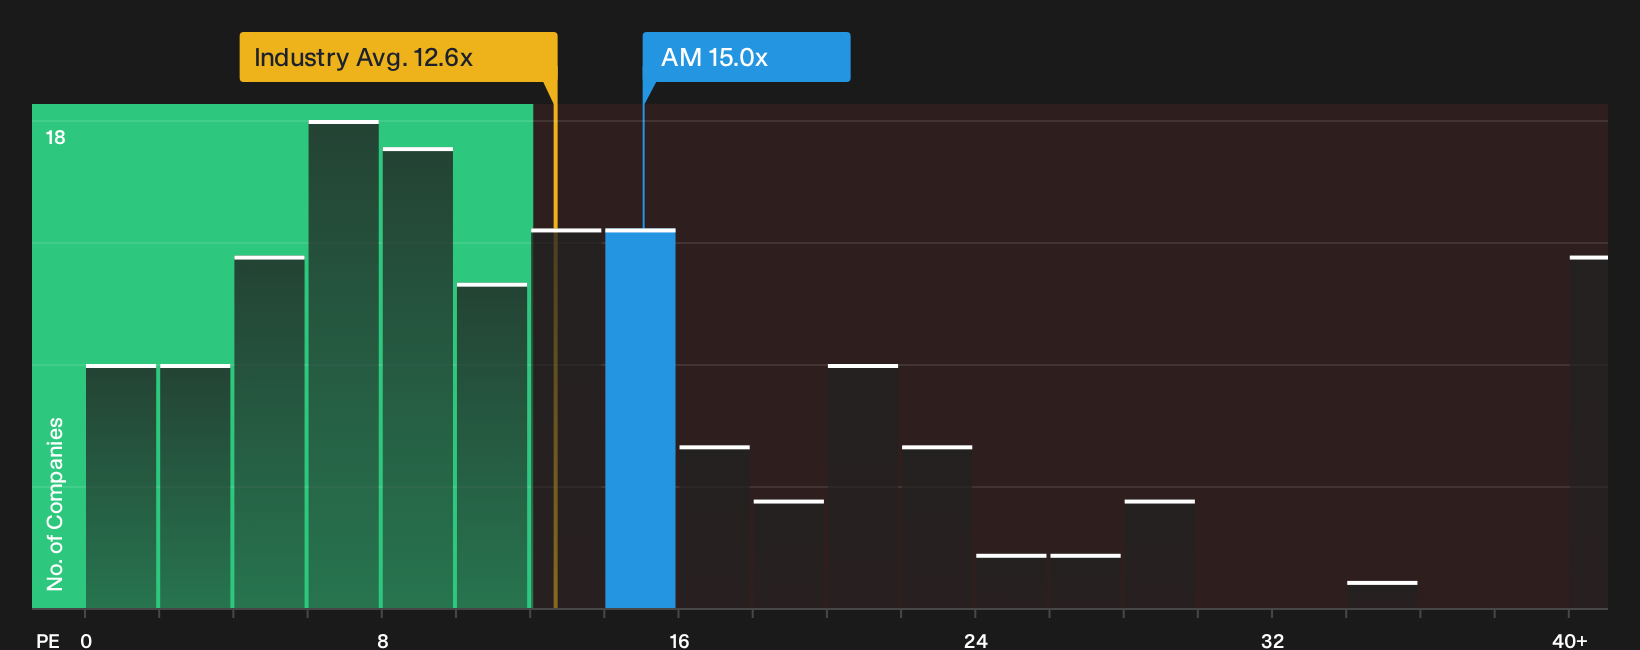
P/E suits Antero Midstream because earnings remain the main anchor for how investors frame this utility like cash flow profile. The stock trades on a P/E of 15.0x, which sits below the peer average near 17.8x yet above the broader Oil and Gas sector on roughly 12.6x. That leaves the shares priced at a premium to the sector but not at the top of the peer range, so the tag on each dollar of profit leans more toward a mid pack positioning within its specialist group.
Because the 15.0x P/E lines up closely with what a tailored fair value model would expect given Antero Midstream's economics, the ratio itself points to a price that is about right rather than clearly cheap or expensive on this metric alone. The recent guidance raise and stronger free cash flow outlook after the Q3 litigation gain help explain why the market is comfortable holding the P/E modestly above the sector average yet still short of the peer group level. Explore the numbers behind Antero Midstream's P/E valuation.
The Antero Midstream Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Antero Midstream pick up where the valuation puzzle leaves off. They spell out which assumptions about future growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price, and they sit on the Community page. Each narrative links a fair value estimate to a clear storyline about Antero Midstream's potential catalysts and key risks so you can track which version gradually lines up with reality over time.
One of the top community narratives on Antero Midstream: 11% undervalued
"Rising in basin natural gas demand from new West Virginia gas fired power plants and data centers is expected to increase throughput on Antero Midstream’s gathering and intrastate pipeline system…"
Discover why this Narrative puts Antero Midstream at 11% undervalued.
Antero Midstream’s valuation still leaves one crucial angle unresolved
Price tags and earnings only tell part of the story, because the real test is who is steering Antero Midstream and how their pay packets line up with your priorities. See who runs Antero Midstream and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com