


Canon (TSE:7751) has moved back into focus after fresh guidance from Canon Marketing Japan Inc. outlined expected 2026 net sales of ¥4,766,000 million and operating profit of ¥456,000 million.
Canon shares trade at ¥4,744 after a mixed recent run, with a 6.85% 90 day share price return but a softer 7 day move. The 1 year total shareholder return of 10.93% and 5 year total shareholder return of 117.88% indicate momentum that has built over time as recent earnings, guidance and dividend announcements reshaped expectations around growth potential and risk.
Scan beyond Canon and identify other potential beneficiaries of this earnings and dividend theme with a curated list of 14 high quality undervalued stocks.
The recent move leaves Canon caught between improving guidance and a choppier week of trading. Is this mainly a reprice of the business, or a mood swing in the market that valuation can test next?
Preferred P/E of 11x: Is it justified?
On Simply Wall St's numbers, Canon trades at a P/E of 11x, which is paired with a share price of ¥4,744 that sits below its estimated fair value based on future cash flow modelling.
The P/E ratio compares the current share price to earnings per share, so it gives you a quick read on how much investors are paying for each unit of profit. For a diversified group like Canon that spans printing, medical equipment, imaging and industrial gear, earnings power is a central anchor, because cash flows depend heavily on how resilient those profits are across cycles.
Canon screens as good value on several fronts. The P/E of 11x is lower than the estimated fair P/E of 15.7x. This implies a level the market could move toward if sentiment and fundamentals line up. That same 11x multiple also comes in below the JP Tech industry average of 12.4x and sits well under the peer average of 20.7x, so the stock trades at a marked discount to both the wider sector and its closer comparables.
Explore the SWS fair ratio for Canon.
Result: Price-to-earnings of 11x (UNDERVALUED)
Still, the picture can change quickly if Canon faces weaker demand in key printing or imaging lines, or if higher input costs pressure those ¥358,891 million profits.
Find out about the key risks to this Canon narrative.
Another View: Canon Through A Cash Flow Lens
The P/E story presents Canon as inexpensive, and the SWS DCF model goes even further. On those cash flow estimates, a fair value of ¥6,572.51 compared with the current ¥4,744 price indicates a steep discount that appears undervalued on a different yardstick.
When one framework highlights a modest gap and another suggests a bigger cushion, it raises a clear question for you as an investor: Which lens do you rely on more when the next earnings surprise is reported, the profits snapshot or the long term cash flow path that the market may be slow to fully reflect in the price?
Look into how the SWS DCF model arrives at its fair value.
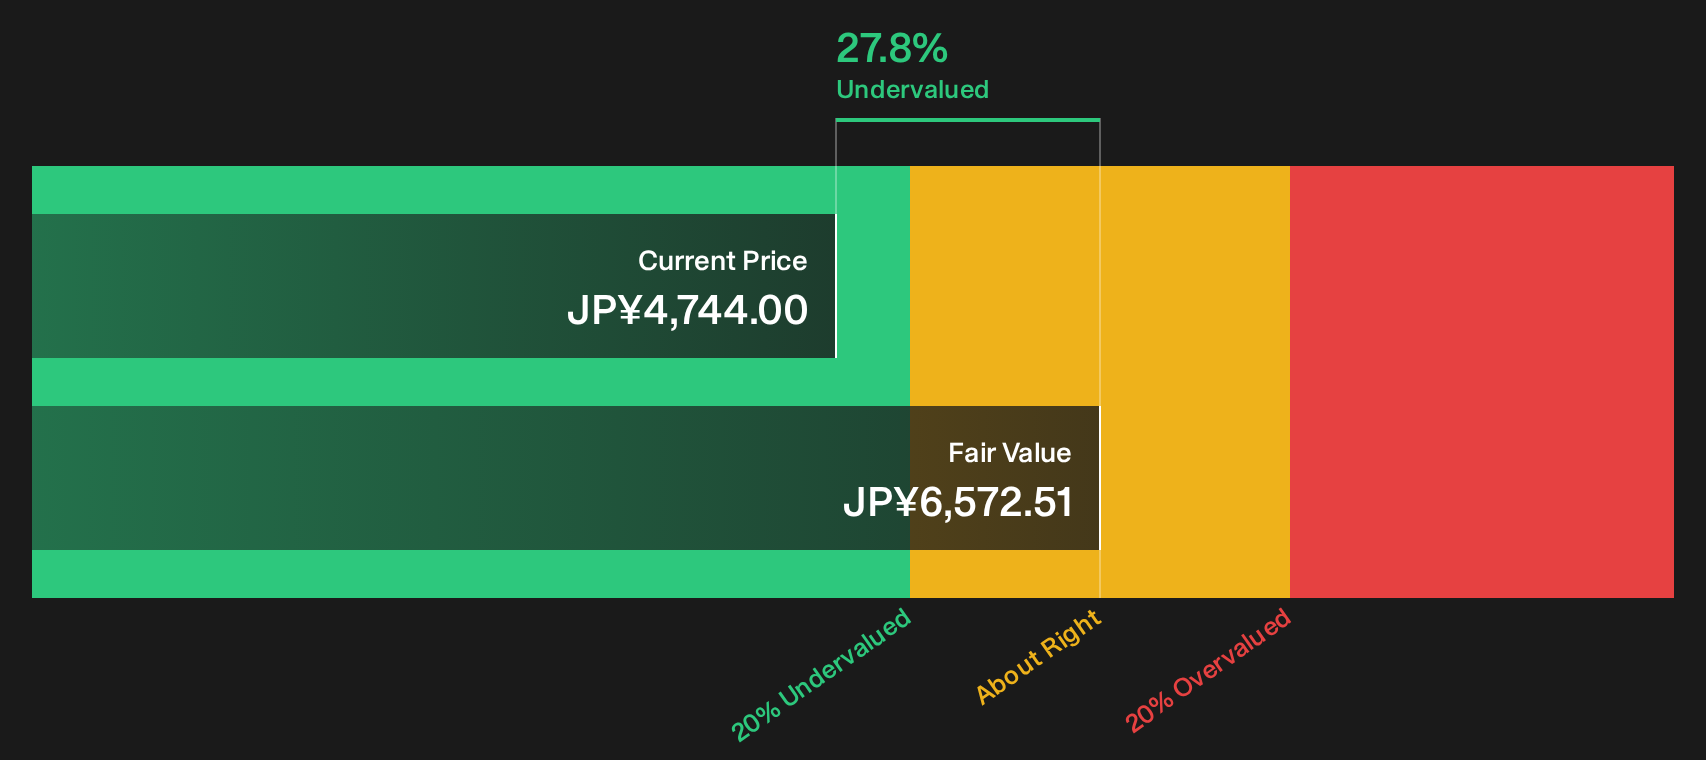
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Canon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Canon now looks finely balanced, with clear concerns and genuine optimism sitting side by side. Move quickly, review the underlying data, and weigh the 4 key rewards and 1 important warning sign
Looking for more Canon investment ideas?
If you only stop at Canon, you may miss opportunities that better match your risk, income, or quality preferences across the market.
- Target higher income potential by scanning companies that appear built for durable payouts with 30 dividend fortresses.
- Strengthen capital preservation by filtering for sturdier finances through the list of solid balance sheet and fundamentals (22 results).
- Get ahead of the crowd by tracking early standouts using the 71 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com