


Recent share performance and business context
IPG Photonics (IPGP) has drawn renewed attention after recent trading left the stock at US$72.59, with the price down 14% over the past month and 23% over the past 3 months.
Investors looking at this laser manufacturer are weighing that share slide against a business that reported annual revenue of US$1.07b and net income of US$27.56m, supported by double digit annual growth rates on both measures.
The recent slide in IPG Photonics' share price, with a 30 day share price return down 13.6% and a 90 day share price return down 22.8%, lines up with a longer stretch of weaker momentum. The 1 year total shareholder return has declined 15.5% and the 5 year total shareholder return has fallen 57.4%, suggesting sentiment has cooled despite the business reporting double digit annual growth in revenue and net income.
Scan beyond IPG Photonics and compare its recent pullback with 19 high quality undiscovered gems that the market may be pricing very differently.
IPG Photonics now trades well below the average analyst price target, after a sharp slide that followed double digit growth in revenue and net income. Is this discount mispricing, caution, or pointing to real valuation risk?
Most Popular Narrative: 42% Undervalued
Against the last close at $72.59, the most followed narrative for IPG Photonics points to a fair value of $124.14, built on analyst expectations for earnings, margins and discount rates that differ sharply from the recent share price slide.
The main factor that needs to work in the company’s favor is that IPG Photonics converts its shift toward higher value systems, medical expansion including Lumibird Medical, and directed energy programs such as CROSSBOW into sustained, profitable revenue that can help offset volatility in micromachining and defense.
The CROSSBOW high energy laser program is moving into a revenue phase with a US$10 million follow on order from Lockheed Martin, multi quarter shipments and successful field tests, providing a path for directed energy to become a more meaningful contributor to revenue and operating leverage if additional defense and infrastructure orders follow.
See why 4 investors see IPG Photonics as 42% undervalued.
Result: Fair Value of $124.14 (UNDERVALUED)
Still, the IPG Photonics story can break if Advanced Solutions weakness in micromachining and defense lingers, or if margin recovery efforts stall and profitability remains thin.
Find out about the key risks to this IPG Photonics narrative.
Another view on IPG Photonics valuation
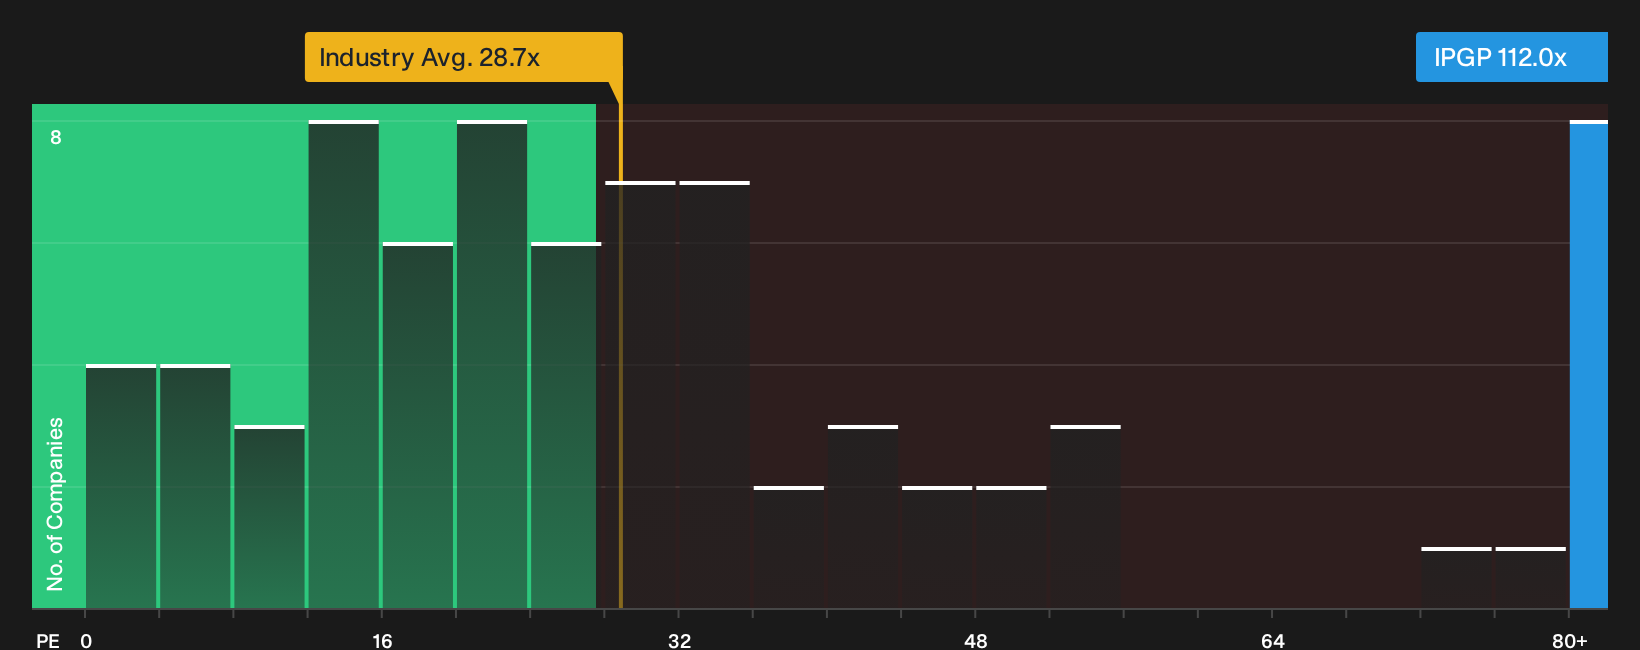
Analysts framing IPG Photonics as 42% undervalued contrasts sharply with a simple earnings multiple check. The stock trades on a P/E of 112x, compared with 28.7x for the US Electronic industry and 30.9x for peers, while the fair ratio sits at 53.3x. That gap points to real pricing risk if expectations reset.
For a closer look at how these earnings multiples line up against fundamentals, including where the fair ratio might eventually pull the valuation, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on IPG Photonics so far. If you want to act while sentiment is this divided and form your own view, review the 2 key rewards and 1 important warning sign
Looking for more IPG Photonics investment ideas?
If IPG Photonics has you rethinking your watchlist, use this moment to scan for other opportunities that match your risk comfort and income goals.
- Target resilient cash generators by reviewing companies in the list of solid balance sheet and fundamentals (24 results) so your portfolio leans on financially robust businesses.
- Hunt for mispriced opportunities and see which stocks the market may have overlooked with the 33 high quality undervalued stocks.
- Stack potential income streams by checking out higher yielding companies screened as 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com