


Alexander's (ALX) just reaffirmed its regular quarterly dividend, declaring a US$4.50 per share payout tied to a mid November record date as investors also look toward the upcoming Q3 2026 earnings release.
At a share price of US$251.62, Alexander's has logged a 3.2% 1 month share price gain and a 15.0% year to date share price return. The 1 year total shareholder return of 20.7% and 3 year total shareholder return of 62.0% point to momentum that has built over time rather than faded, despite the 8.1% 3 month share price decline. The recent dividend affirmation and upcoming Q3 2026 earnings date give investors fresh catalysts to reassess risk and income expectations.
Spot other real estate income plays showing momentum similar to Alexander's by scanning our curated list of 5 dividend fortresses.After a 3.2% one month climb and a 15.0% year to date run, the real question around Alexander's is simple: Is meaningful upside still on the table, or has most of the easy money already been made as earnings approach?
Price-to-Earnings of 7.6x for Alexander's: Is it justified?
On a pure earnings multiple, Alexander's looks cheap compared to its sector. The stock trades on a P/E of 7.6x, while the US Retail REITs group sits at 24.1x and the broader US market is at 18x. That gap shows the market is attaching a lower earnings multiple to ALX despite the recent share price strength.
The P/E ratio compares what investors pay for each dollar of earnings, so it is a simple way to see how profits are being valued. For a real estate investment trust like Alexander's, which earns income from leasing and managing properties, that earnings multiple often reflects expectations around rental income stability, asset values and balance sheet risk rather than rapid expansion.
Here the numbers send a mixed message. On one side, the P/E of 7.6x appears to offer value both versus peers at 24.1x and versus the estimated fair P/E of 10.6x. That fair ratio hints at a level the valuation could move toward if sentiment and fundamentals aligned. On the other side, forecasts call for earnings to decline on average over the next three years, and recent profits included a very large one-off gain of $148.0m that inflates the headline result. Interest costs are also flagged as not well covered by earnings, which can limit how much investors are willing to pay for each dollar of profit.
Against sector and fair value markers, the discount is still clear. Trading on 7.6x earnings compared to both a peer average of 24.1x and a fair P/E estimate of 10.6x suggests Alexander's is priced with a meaningful safety margin relative to many retail REITs, even as forecasts and capital structure risks weigh on that picture.
Explore the SWS fair ratio for Alexander's.
Result: Preferred multiple of Price-to-Earnings of 7.6x (UNDERVALUED)
Still, earnings pressure after a very large one off gain and interest costs that are not well covered could quickly reset how Alexander's is valued.
Find out about the key risks to this Alexander's narrative.
Another View on Alexander's Valuation
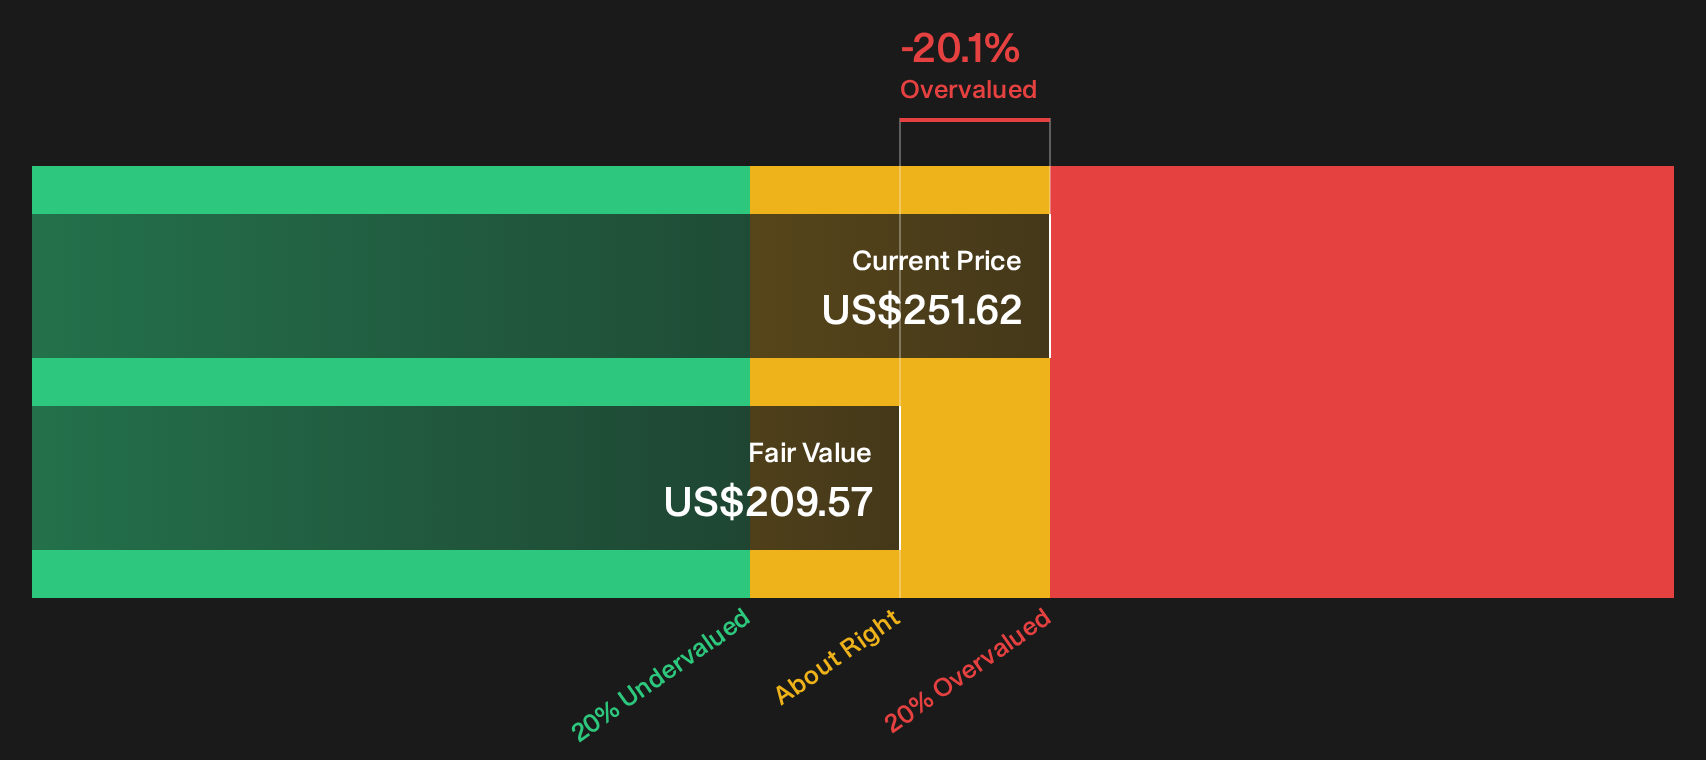
The earnings multiple points to value, yet the SWS DCF model tells a different story. On that cash flow view, Alexander's estimated future cash flow value sits at $209.57, while the share price is $251.62. That gap suggests the stock screens as overvalued on this metric. Which signal do you trust more when earnings are forecast to decline so sharply?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Alexander's for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Alexander's valuation and income profile can make the story feel messy, which is exactly why your own read on the numbers matters. If you want a fuller picture before you decide how much risk or upside you are comfortable with, start by weighing the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Alexander's?
If Alexander's has sharpened your focus on valuation and income, do not stop here. Broader research often surfaces opportunities you did not expect.
- Target sturdier portfolios by reviewing companies with resilient finances through our list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality by scanning the 33 high quality undervalued stocks that pair fundamental strength with attractive valuations.
- Strengthen your income stream by checking out the 5 dividend fortresses that combine higher yields with disciplined fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com