


Mastercard (MA) just reported fresh numbers, with third quarter 2026 results showing higher sales, net income and earnings per share compared with the same period a year earlier.
Recent moves in Mastercard’s stock suggest investors are leaning into that story. The share price has logged a 15.5% 1 month share price return and a 13.3% year to date share price return, while the 5 year total shareholder return of 88.0% reflects optimism that the latest earnings, partnerships and buybacks may still have room to influence sentiment over different time frames.
Scan Mastercard’s latest moves alongside a hand-picked group of payment and fintech peers using our 19 high quality undiscovered gems for ideas that may still be flying under most radars.
Mastercard’s latest surge has pulled the share price closer to analyst targets, yet a sizeable gap still remains to some fair value estimates. Is the recent move closing that gap, or just narrowing it slightly before the next rerating conversation?
Most Popular Narrative: 15% Undervalued
On the narrative view, Mastercard’s fair value of $750 sits well above the last close at $638.01, which puts the current price in clear discount territory according to follower consensus.
What it offers instead: a business that compounds safely, a payout growing at double-digit rates from a tiny base, and a price that does not currently reflect either of those things. Setups like that do not come around often, and the current pullback looks more like an entry point than a warning sign.
See why 151 investors see Mastercard as 15% undervalued.
Result: Fair Value of $750 (UNDERVALUED)
Still, Mastercard’s story can change quickly if regulators clamp harder on interchange fees or if newer payment rails win volume that currently flows across its network.
Find out about the key risks to this Mastercard narrative.
Another View: Mastercard Through The P/E Lens
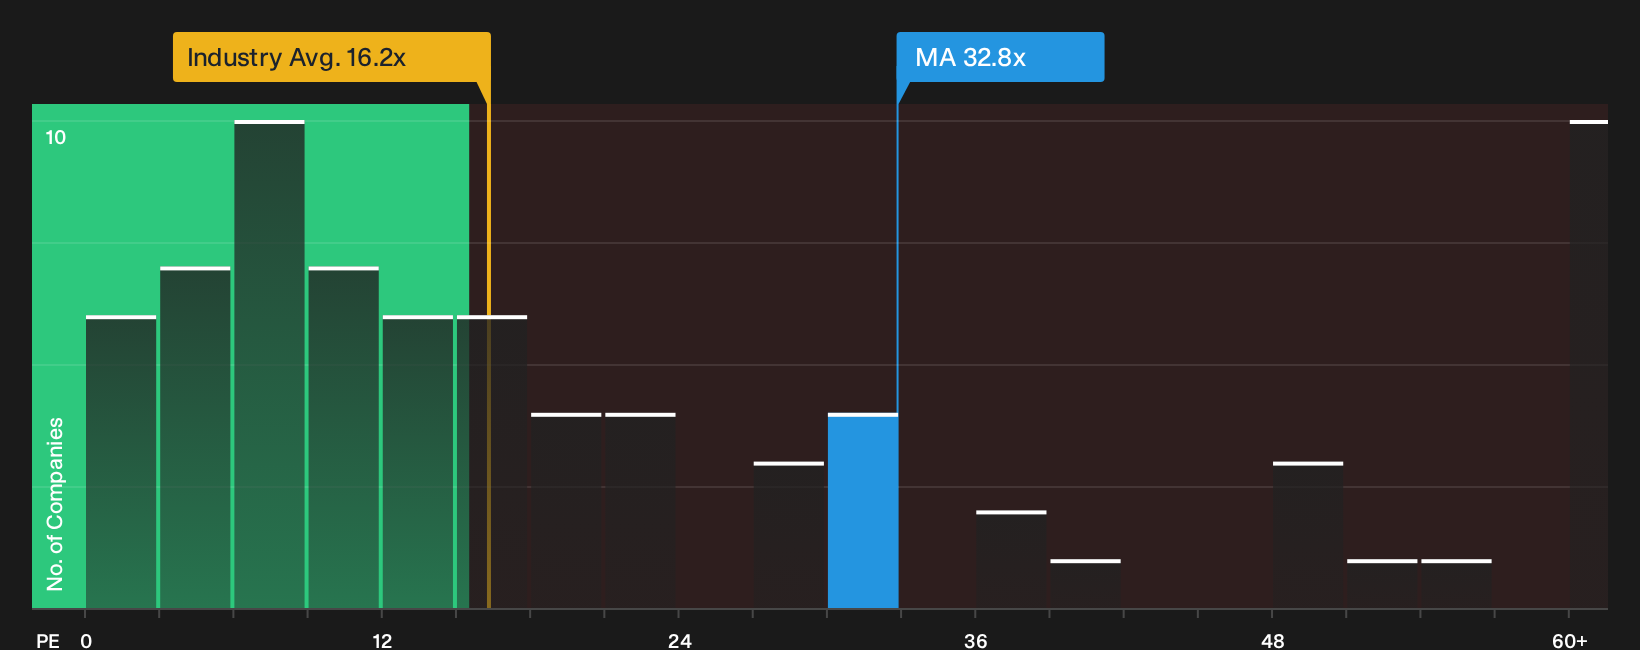
On a multiples check, Mastercard looks less straightforward. The P/E sits at 32.8x, roughly double the US Diversified Financial industry at 16.2x, higher than the fair ratio of 21.4x, yet below peers that average 48.7x. Is that a quality premium or valuation risk building up?
For a closer look at how that kind of earnings multiple can stretch or compress over time, and what it might mean for your own risk tolerance, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and worry around Mastercard feels familiar, that is the point. Sentiment is rarely one sided. Act quickly, review both sides of the ledger, and ground your own view in the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Mastercard?
Do not stop at one opportunity. Broaden your watchlist with focused stock ideas built from hard numbers, not hype, using the Simply Wall Street Screener.
- Target potential value by scanning a curated pool of quality companies that look mispriced with our 33 high quality undervalued stocks.
- Prioritise resilience and sleep-better-at-night holdings by filtering for businesses that score well on financial strength using the 29 resilient stocks with low risk scores.
- Zero in on payout-focused opportunities by tracking companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com