


Ardelyx has seen a sharp swing in fortunes, with the share price well below its highs even as investors focus on what its kidney treatment portfolio could mean for future sales. The key issue now is whether the current valuation of Ardelyx stock can be grounded in the revenue the business is generating and may generate from its therapies.
- Over the last 5 years, the stock has delivered a total return of 152.5%. That puts real pressure on the question of how much revenue progress is already baked into today's price.
- Fresh real world data on XPHOZAH presented at ASN Kidney Week 2026 may support expectations for future prescribing and sales. This feeds directly into how much investors are willing to pay for each dollar of Ardelyx's top line.
- The analysts covering Ardelyx have run their own numbers. See what analysts think Ardelyx's shares could be worth.
The stock's next move may depend on whether the current share price looks aligned with Ardelyx's sales when set against the Fair Ratio benchmark.
If you want a broader watchlist of companies where sales power is the starting filter rather than the finish line, consider a focused screen like 33 high quality undervalued stocks.
Does Ardelyx Look Undervalued on Sales?
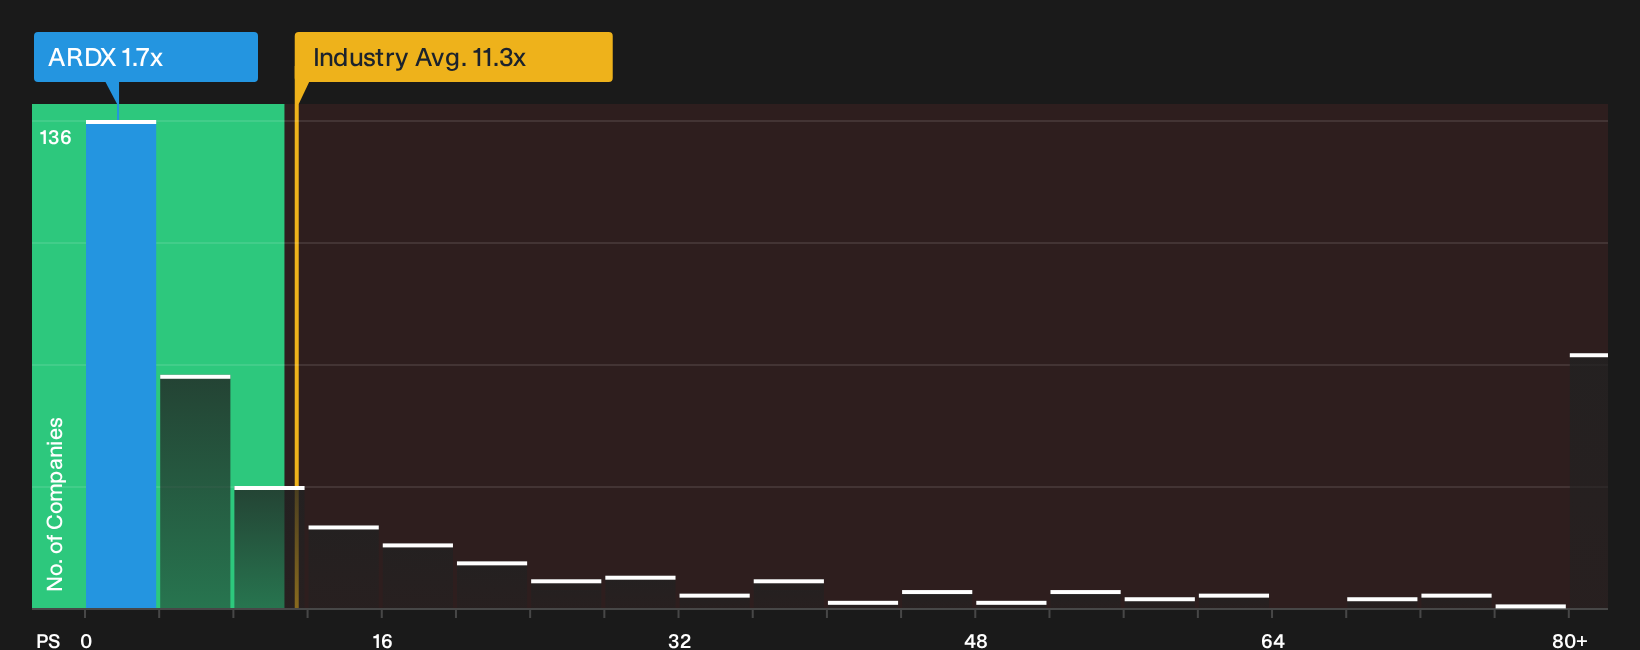
P/S works well for Ardelyx because investors are still focused on where its kidney therapy revenue base could go rather than on current profits. From this perspective, the stock trades on a P/S ratio of 1.7x, compared with an industry average for biotechs of 11.3x and a peer group average of 14.2x. The Fair Ratio, which blends in factors like growth potential, profitability profile, scale and risk, points to a higher multiple than where Ardelyx currently trades, so the shares screen as undervalued on sales.
Because the recent XPHOZAH data at ASN Kidney Week 2026 speaks directly to how large Ardelyx’s dialysis opportunity might be, the current discount on the P/S multiple comes into sharper focus. The valuation implies investors are paying far less per dollar of revenue than for many comparable biotech stocks, so you need to judge whether the company’s clinical and commercial execution justifies that gap. Explore the numbers behind Ardelyx's P/S valuation.
The Ardelyx Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ardelyx pick up where the valuation puzzle leaves off by spelling out which paths for Ardelyx's growth, margins and earnings would need to play out for the share price to look meaningfully higher or lower than today, all housed on the Community page. Each scenario ties its number to a clear view of how revenue expansion, profitability and risk might evolve, which you can revisit as fresh information emerges.
One of the top community narratives on Ardelyx: 77% undervalued
"Reliance on a narrow product range and major payer exposes Ardelyx to significant reimbursement, regulatory, and competitive risks that threaten long-term financial stability..."
Discover why this Narrative puts Ardelyx at 77% undervalued.
One more Ardelyx check that belongs beside the valuation work
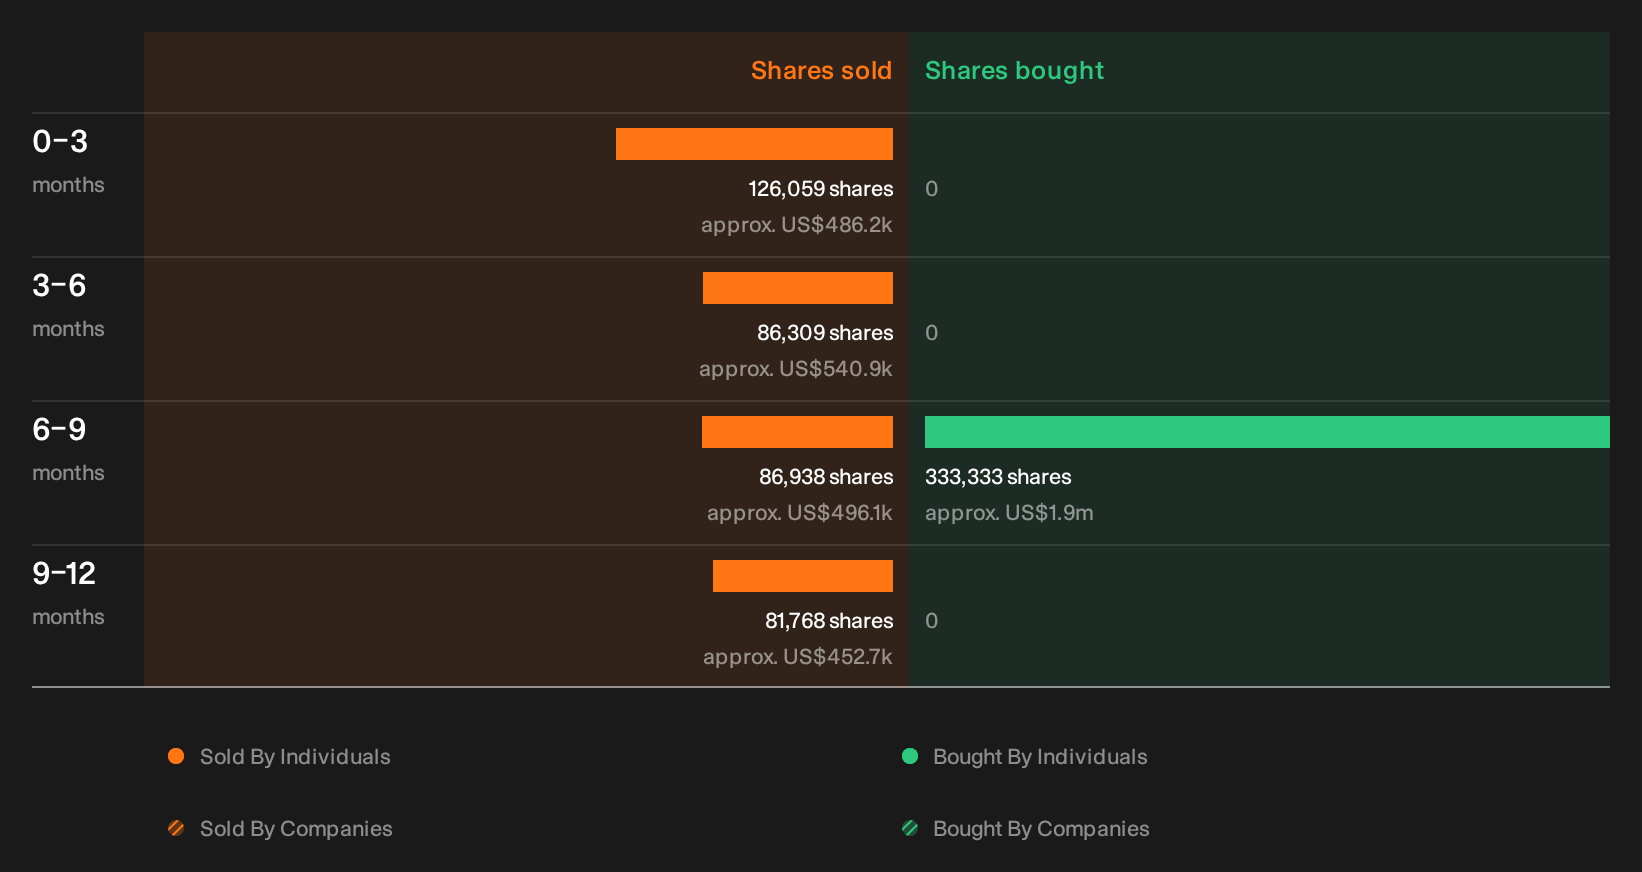
Price multiples tell only part of the story, because recent trading by Ardelyx insiders can hint at how those closest to the business are acting with their own holdings. See the recent insider selling flagged for Ardelyx.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com