


CONMED has seen its share price fall sharply over the past few years, which puts fresh attention on a simple question for investors who focus on fundamentals. Is the current valuation of the stock properly supported by the earnings the business is generating today.
- Over the past 5 years the share price has declined 70.4%, which puts the spotlight on whether the earnings profile still lines up with what the market is paying now.
- The business depends heavily on converting medical device sales into consistent profit, so the durability of its margins and cash conversion can be crucial for how investors judge what its earnings are worth.
- The analysts covering CONMED have run their own numbers. See what analysts think CONMED's shares could be worth.
The stock's next move may depend on whether CONMED's current share price is well supported by the level and quality of its earnings.
If you are weighing whether CONMED's earnings justify its current price, it can help to compare that question across 33 high quality undervalued stocks.
Is CONMED Still Cheap on Earnings?
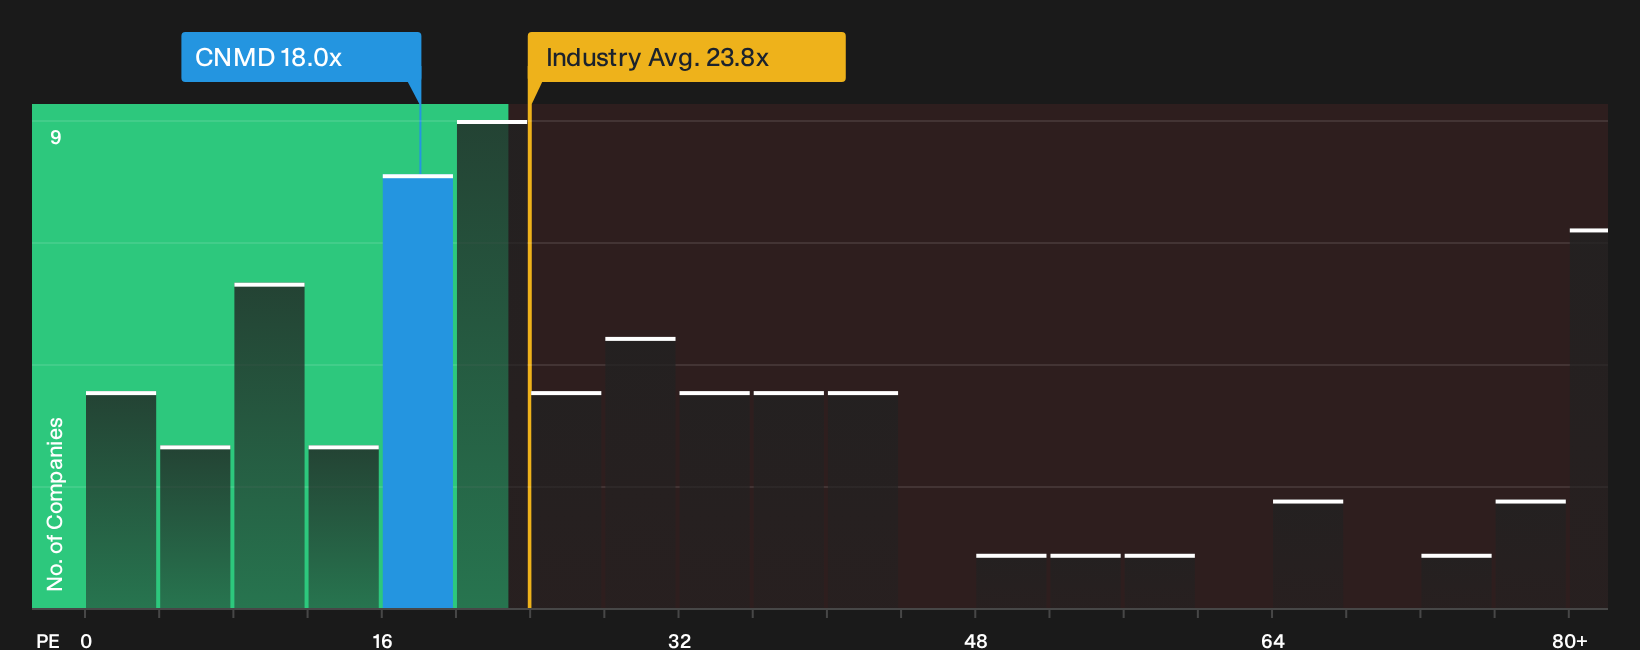
For a business like CONMED that is already profitable, the P/E ratio offers a straightforward way to see what investors are paying for each dollar of earnings. The stock currently trades on a P/E of 18.0x, which is below the Medical Equipment industry average of 23.8x and also well under the broader peer group on about 45.7x. That sets up a picture where the market is valuing CONMED's earnings at a lower level than many similar healthcare equipment companies.
The Fair Ratio model, which looks at factors such as earnings profile, margins, risk and size, points to a higher P/E than where CONMED trades today. On this framework, the current multiple screens as undervalued compared with what might be expected for a company with this earnings footprint. To decide whether that gap is justified, you would need to weigh how dependable you consider its profits, cash generation and product portfolio to be over time. Explore the numbers behind CONMED's P/E valuation.
The CONMED Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St give you a way to spell out what would need to be true about CONMED's growth, profitability and earnings profile for the current share price to look meaningfully higher or lower. Each one turns its view of fair value into a specific, trackable idea about the business, so you can see how that thesis holds up as new information arrives.
Community views on CONMED earnings are close on valuation but differ on how much its higher growth platforms can really deliver.
Bull case: roughly fairly valued
"CONMED’s decision to exit lower growth gastroenterology lines and concentrate capital and commercial resources on high growth, high margin platforms such as AirSeal, Buffalo Filter and BioBrace sharpens the product mix..."
Discover why this Narrative puts CONMED at roughly fairly valued.
Bear case: roughly fairly valued
"CONMED’s focus on platforms such as AirSeal, Buffalo Filter and BioBrace, supported by over 30 published BioBrace studies and clinical data for AirSeal, could be offset by the company’s scale disadvantages in cost leverage and distribution..."
Explore why this Narrative puts CONMED at roughly fairly valued.
CONMED’s price is only one piece of the puzzle
Before you decide how CONMED fits into your portfolio, it helps to understand who is steering the business and how their incentives line up with yours. See who runs CONMED and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com