


Raised guidance and capital returns set the tone
Cullen/Frost Bankers (CFR) reset the conversation for its stock after Q3 2026, pairing higher full year net interest income guidance with ongoing share repurchases and affirmed common and preferred dividends.
Investors have seen a mixed price path this year, with the share price giving back some ground over the past quarter while still showing strong year to date momentum, supported by raised guidance, steady dividends, buybacks, and Cullen/Frost Bankers’ upcoming move to the Texas Stock Exchange.
Scan how Cullen/Frost Bankers stacks up against other quality regional financials by reviewing this curated set of list of solid balance sheet and fundamentals (24 results).
Cullen/Frost Bankers just paired higher guidance with buybacks and a Texas-focused relisting, which gives you a live choice: pay up for that package now, or wait and hope the valuation hands you a cheaper shot.
Most Popular Narrative: 9.9% Undervalued
Cullen/Frost Bankers closed at $157.60, while the most followed narrative pegs fair value closer to $174.86. This puts the current Texas focused expansion story under a valuation lens rather than just a sentiment swing.
Management’s guidance for 2026, including higher ranges for full year average loan growth of 7% to 8%, net interest income growth of 4.75% to 5.25% and noninterest income growth of 7.5% to 8.5%, along with lower expected expense growth, points to operating leverage that could support future margins and earnings if delivered.
See why 4 investors see Cullen/Frost Bankers as 10% undervalued.
Result: Fair Value of $174.86 (UNDERVALUED)
Still, the Cullen/Frost Bankers story can break if Texas focused credit pockets in real estate and energy worsen, or if branch heavy expansion keeps expenses stubbornly high.
Find out about the key risks to this Cullen/Frost Bankers narrative.
Another View: Cullen/Frost Bankers Looks Pricey On P/E
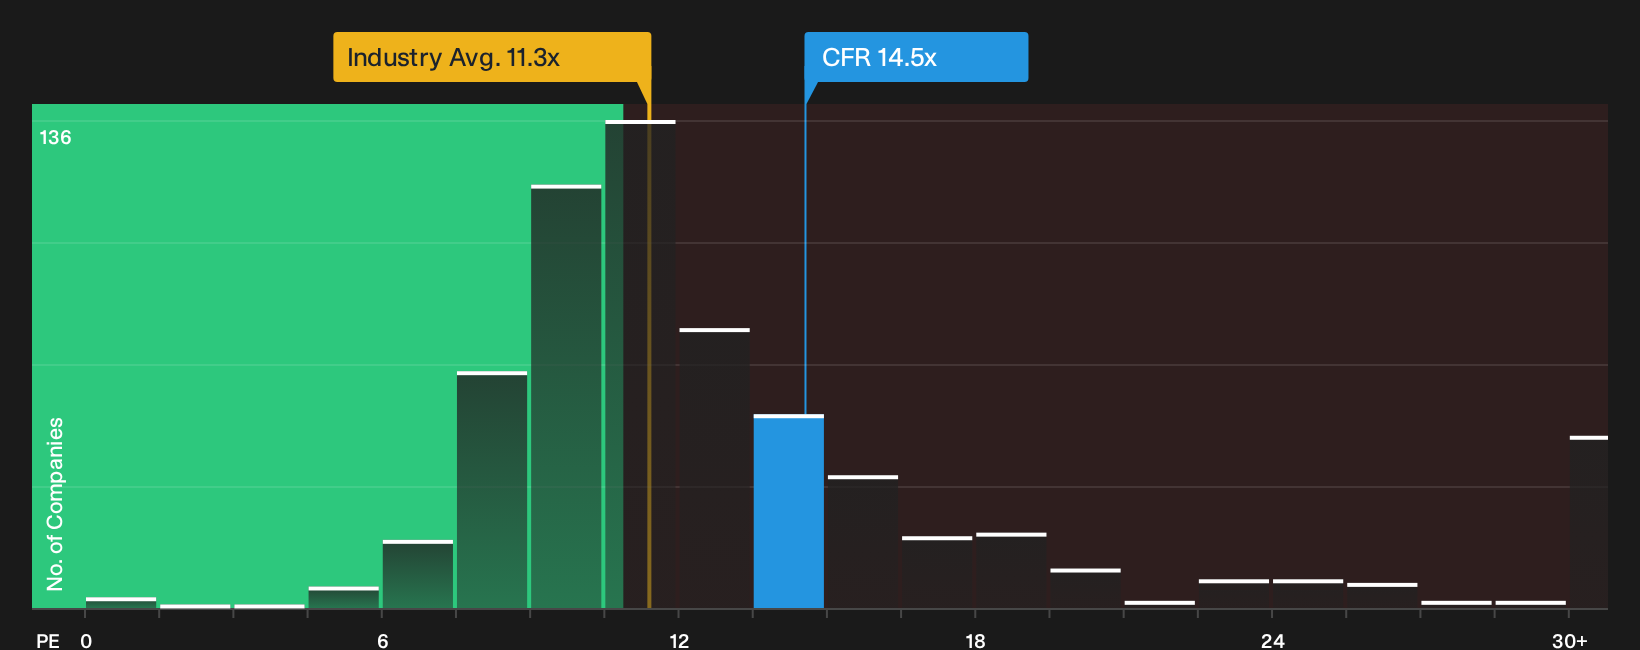
The first narrative paints Cullen/Frost Bankers as roughly 9.9% undervalued, yet the market’s own yardstick tells a different story. On a P/E of 14.5x, the stock trades richer than the US Banks industry at 11.3x and above its own fair ratio of 11.8x. This points to less of a clear bargain and more valuation risk if expectations slip.
That richer multiple can still make sense if you think Cullen/Frost Bankers’ branch expansion, dividend record and Texas footprint justify paying up, but it also means there is less room for disappointment before the share price has to adjust.
For a closer look at how this price compares with earnings power across peers, review the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed signals on Cullen/Frost Bankers so far. If you want your view to be more than a headline reaction, review the underlying rewards and risks, starting with the 3 key rewards.
Looking for more Cullen/Frost Bankers sized ideas?
If Cullen/Frost Bankers has your attention, do not stop here. Cast the net wider and pressure test your thesis against fresh opportunities before the market moves.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (24 results) that filters for financial strength first.
- Hunt for potential mispriced opportunities with a 33 high quality undervalued stocks that spotlights quality businesses trading below their implied worth.
- Prioritise stability and income by reviewing a 5 dividend fortresses built around high yield and payout resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com