


- American Homes 4 Rent recently reported a 4.22% dividend yield on a 67.3% Core FFO payout, supported by 96% occupancy across 60,482 single family rental homes and an integrated development platform aligned with the 21st Century ROAD to Housing Act.
- The business is recycling capital from lower yielding MLS dispositions into higher yielding developments and joint ventures, which may influence how its dividend profile and cash generation are viewed relative to other residential REITs.
- This article examines how American Homes 4 Rent's dividend and occupancy metrics contribute to the broader investment narrative for the REIT.
Compare American Homes 4 Rent's 4.22% yield and capital recycling approach with a curated 5 dividend fortresses that may offer similar income profiles with different risk trade offs.
American Homes 4 Rent Investment Narrative Recap
To own American Homes 4 Rent, you need to be comfortable with a single family rental platform that leans on an integrated development engine, high occupancy and a recurring dividend. The recent 4.22% yield on a 67.3% Core FFO payout, supported by 96% occupancy, broadly reinforces that income story rather than changing it.
The more immediate swing factor is how well management keeps extracting a yield spread between MLS disposals and new projects while interest costs remain a headwind. The main risk is that elevated rates or sticky supply in markets like Texas or Florida compress that spread, which would put pressure on funds from operations and dividend flexibility.
The capital recycling update is the clearest recent datapoint tied to this story. American Homes 4 Rent is moving cash out of lower yielding MLS dispositions and into higher yielding developments and joint ventures. That directly links to the reported 67.3% Core FFO payout ratio and the current 4.22% dividend yield.
For catalysts, this recycling program sits alongside the moderated in house development pipeline, joint venture capital and clarity from the 21st Century ROAD to Housing Act. Execution on those projects, combined with maintaining high occupancy in the 90% range through lease expiration management, will go a long way toward determining whether current earnings forecasts and interest coverage concerns are conservative or justified.
American Homes 4 Rent Analyst Assumptions Behind the Dividend Story
Analysts sketch a different side of the American Homes 4 Rent income profile when you line up the dividend, the occupancy and the forecast earnings path. Their models point to revenue rising by 3.8% a year over the next three years while profit margins move from 24.7% today to 10.4% in about three years. On those assumptions, earnings are expected to move from $463.5 million today to $218.8 million by 2029, even though the dividend is currently framed around Core FFO and high occupancy rather than headline net income.
That shift in profitability feeds directly into how some analysts frame valuation risk around the stock. They are using 2029 estimates that assume revenues reach about $2.1b and earnings come in at $218.8 million, which implies a future P/E of 68.6x compared with 24.1x today and 41.9x for the wider US residential REIT group. On top of that, the analyst set working off the Simply Wall St report assumes the share count itself declines by around 3.04% a year over the next three years, which would magnify per share metrics if the forecasts prove accurate.
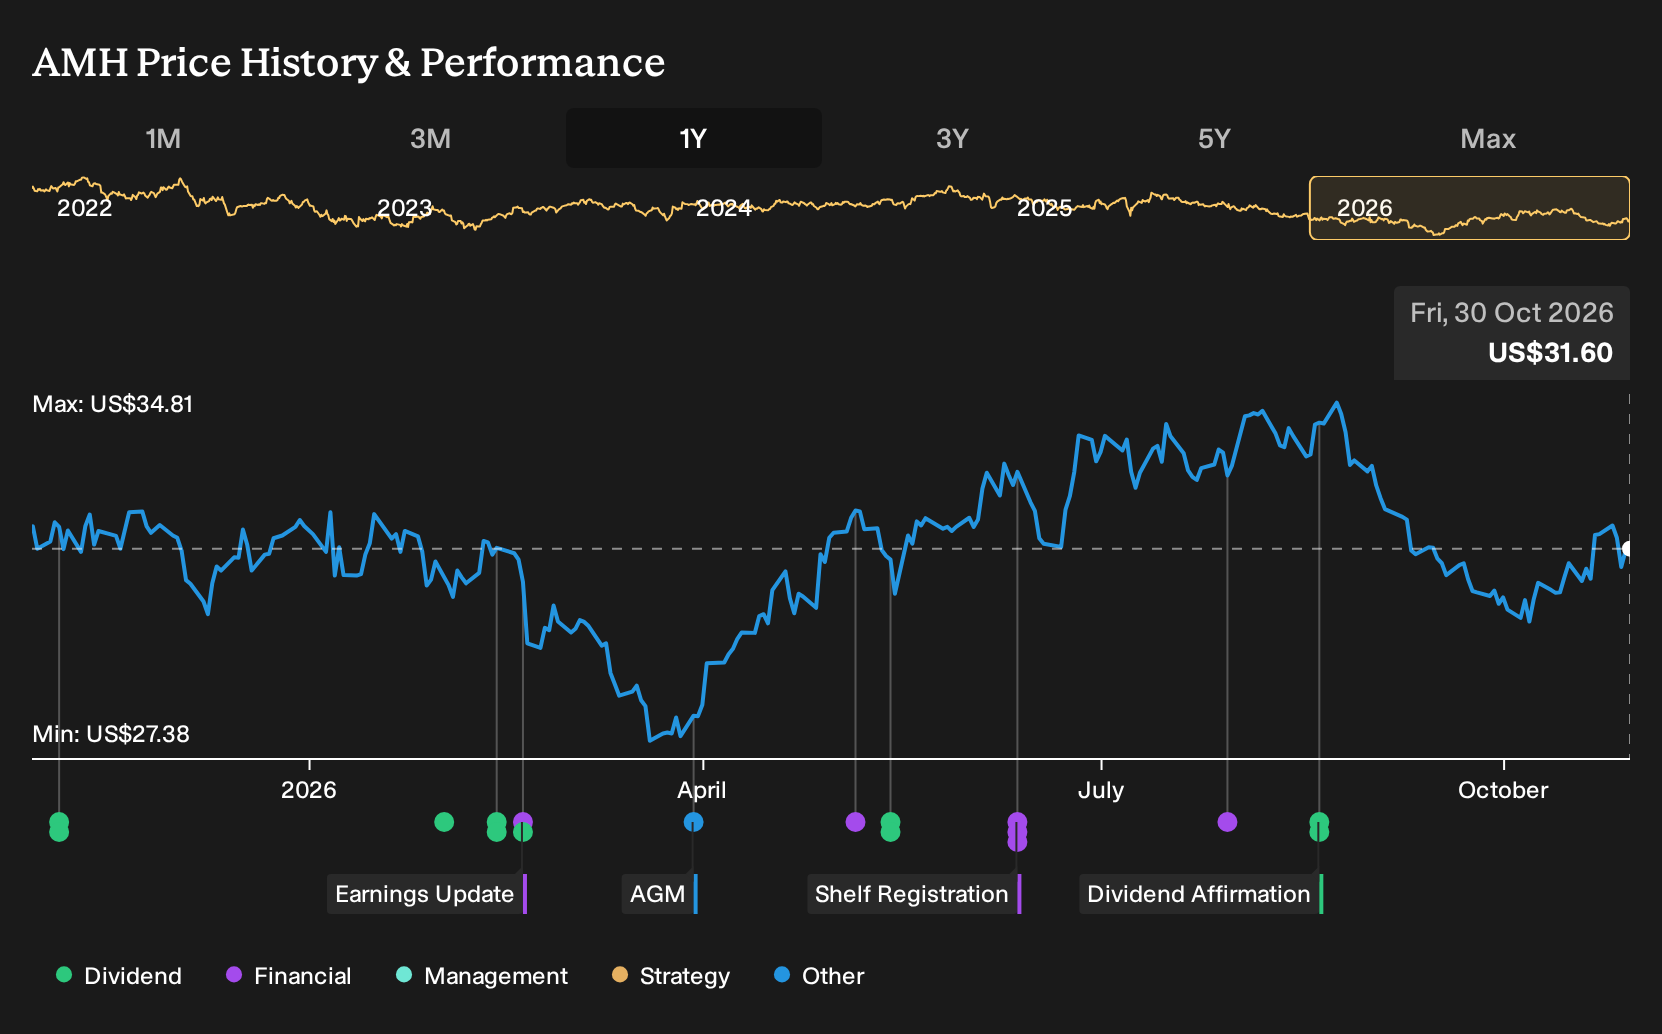
Price targets in that framework cluster around a consensus of $37.11, against a recent share price reference of $31.02 as of the report, with the most optimistic analyst at $42.00 and the most cautious at $31.00. Those targets rest on the view that American Homes 4 Rent still commands more value than the market price implies despite the expectation of lower earnings by 2029. For an income focused holder looking at the 4.22% dividend yield and 67.3% Core FFO payout, that split between solid occupancy driven cash generation and softer earnings forecasts is a key piece of context when thinking about relative trade offs versus other residential REITs or a curated dividend screener.
American Homes 4 Rent's narrative projects about $2.1b revenue and $218.8 million earnings by 2029. This rests on revenue growing at 3.8% per year and an earnings decline of $244.7 million from $463.5 million today.
Discover how American Homes 4 Rent's fair value indicates a 17% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community range from US$28.51 to about US$52.20, so some retail investors see American Homes 4 Rent as materially mispriced in both directions. When you set that against interest rate and supply risks, plus the potential impact of the Road to Housing Act, you are looking at sharply different paths for future cash generation. Opinions can diverge widely, so explore several of these viewpoints before deciding how American Homes 4 Rent fits your income plan.
Explore 3 other American Homes 4 Rent fair value estimates, including one that suggests there could be as much as 65% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your American Homes 4 Rent research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for American Homes 4 Rent. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Homes 4 Rent's overall financial health at a glance.
Looking for more investment ideas beyond American Homes 4 Rent?
If the American Homes 4 Rent story has sharpened your thinking on income, balance sheets and risk, it can help to line those views up against a wider set of opportunities using the Simply Wall St screener tools.
- For income that aims to pair yield with resilience, review a curated 5 dividend fortresses that focuses on companies prioritizing regular distributions and balance sheet support.
- If capital protection ranks higher on your checklist, scan through a 29 resilient stocks with low risk scores to find businesses that score well on volatility and financial risk metrics.
- When you want to hunt for potential future leaders before they are widely followed, search across a 19 high quality undiscovered gems that filters for quality fundamentals with relatively limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com