


Q3 earnings beat and guidance reset the conversation
Dominion Energy (D) has pulled investor focus after third quarter results came in ahead of management guidance on earnings per share, paired with firmer full year operating earnings and dividend guidance.
The latest update matters because it ties near term performance to a long pipeline of regulated grid, data center and renewable projects, while also confirming the payout framework that income focused holders track closely.
The recent Q3 beat and reaffirmed guidance have landed alongside a run of income focused headlines, including the confirmed quarterly dividend of US$0.6675 per share. That backdrop has helped Dominion Energy’s 1 month share price return of 8.66% and year to date share price gain of 12.46% contrast with a 90 day share price decline of 3.76% and a 3 year total shareholder return of 68.29%, which together indicate momentum rebuilding after a weaker stretch as income and long term holders reassess the stock around US$66.62.
Scan beyond Dominion Energy and compare its setup with a curated 42 power grid technology and infrastructure stocks that is riding the same grid and data center investment wave.
After a sharp move back toward US$66, the question for Dominion Energy holders is simple: accept today’s reset terms or wait and hope valuation work provides a cheaper entry point.
Most Popular Narrative: 5% Undervalued
On the most followed view, Dominion Energy’s fair value of $70 sits modestly above the last close at $66.62. This frames the current reset as a small discount rather than a deep value play.
Planned investment of nearly US$65b from 2026 to 2030 in grid modernization, infrastructure upgrades and renewable deployment, including roughly US$2b of battery projects over five years, creates a visible pipeline of capital that can translate into higher regulated asset value and long-term earnings.
See why 56 investors see Dominion Energy as 5% undervalued.
Result: Fair Value of $70 (UNDERVALUED)
Still, the story can flip quickly if the NextEra merger runs into tougher conditions, or if further Coastal Virginia Offshore Wind delays squeeze Dominion Energy’s projected economics.
Find out about the key risks to this Dominion Energy narrative.
Another View: What Dominion Energy’s P/E Is Telling You
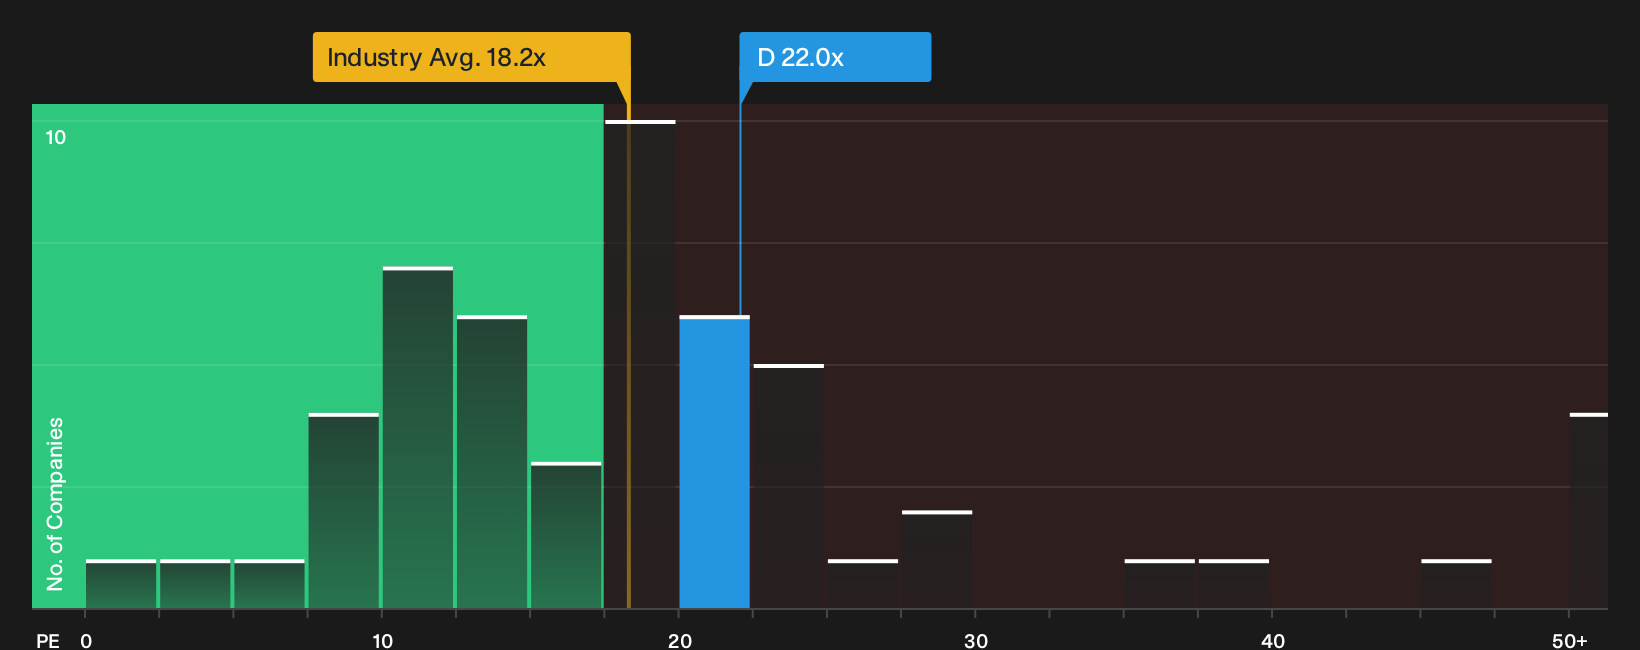
The earlier fair value of $70 casts Dominion Energy as modestly undervalued. The P/E ratio tells a tougher story. At about 22x earnings, the stock trades richer than both peers at 21x and the global Integrated Utilities group at 18.2x, even though the fair ratio sits higher at 24.8x. That gap hints at some upside if sentiment improves, but it also leaves less room for error if earnings or regulation disappoint.
For a closer look at how that earnings multiple stacks up against what the numbers suggest the ratio could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on valuation and earnings can make Dominion Energy feel finely balanced. Move quickly, review the underlying data, and weigh both sides through the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Dominion Energy?
If Dominion Energy has sharpened your focus, use that momentum and line up a few more high conviction candidates before the next round of earnings resets expectations.
- Target resilient balance sheets and robust fundamentals by reviewing the list of solid balance sheet and fundamentals (24 results) that filters for companies with financial strength front and center.
- Stack the odds toward value by scanning the 33 high quality undervalued stocks that highlights quality businesses where price and fundamentals still appear out of sync.
- Prioritize staying on top of emerging stories with the 19 high quality undiscovered gems before the crowd fully prices in their potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com