


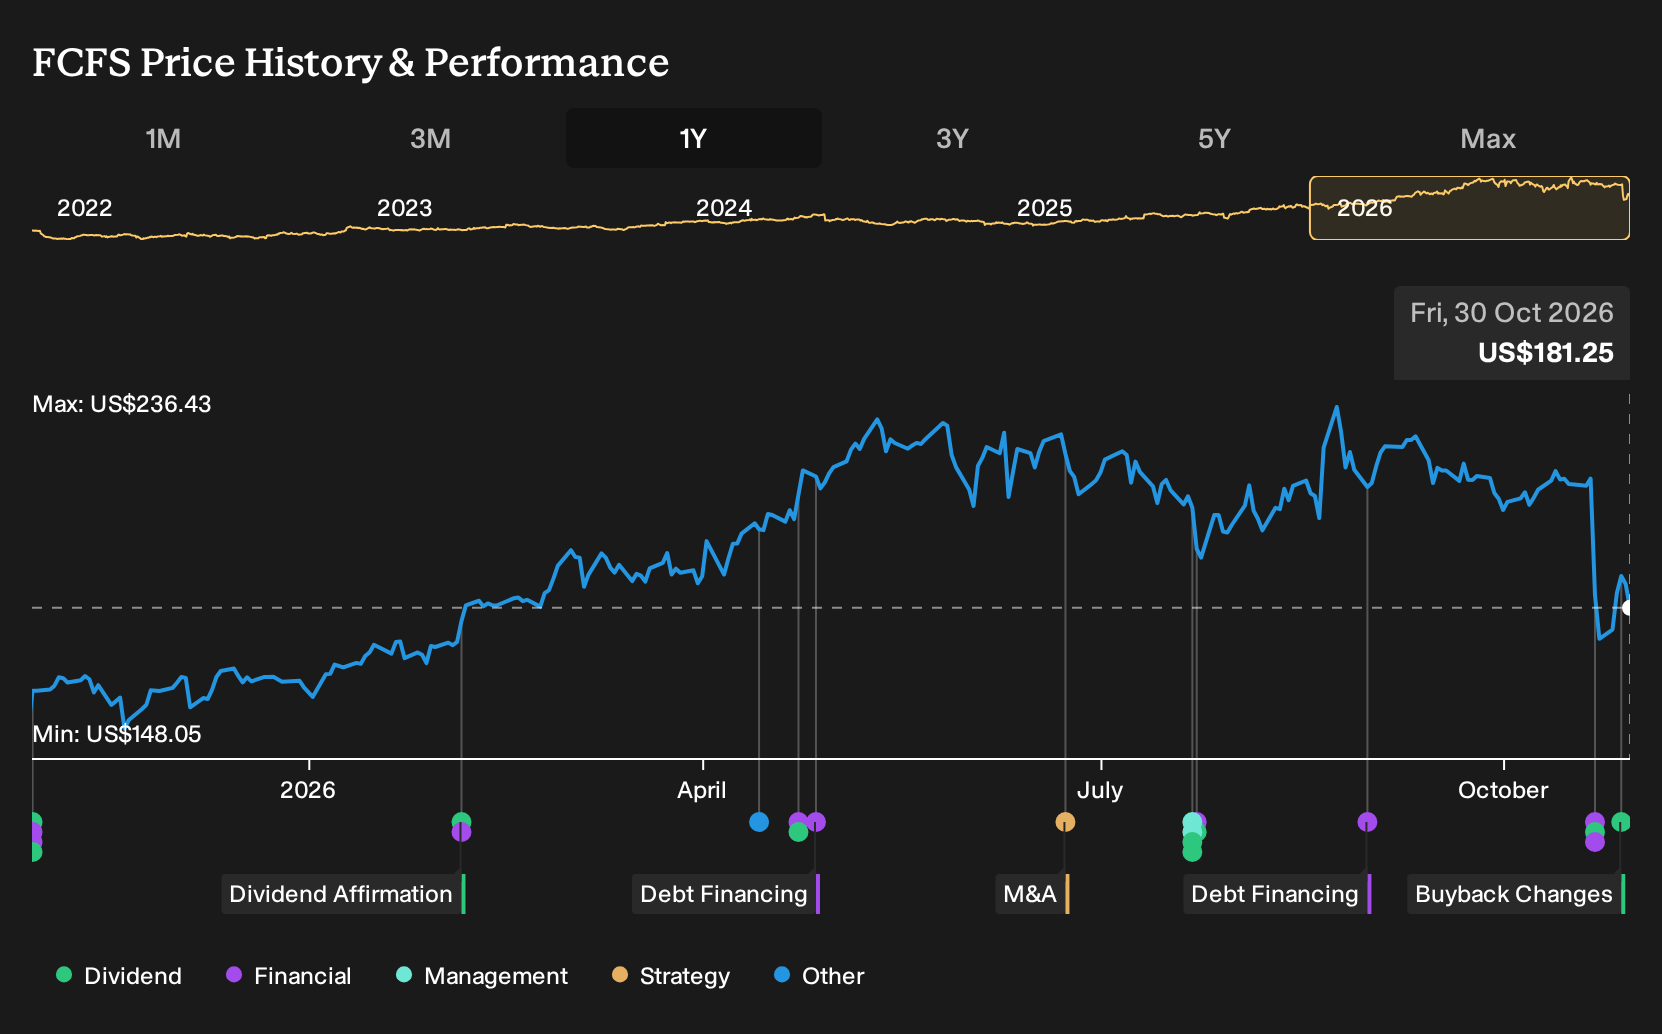
- FirstCash Holdings reported third quarter 2026 revenue of US$1,101.17 million and net income of US$101.15 million, increased its quarterly dividend by 10% to US$0.46 per share, and lifted its share repurchase authorization to US$350 million after recent buyback activity.
- The combination of higher earnings, a larger dividend, and an expanded buyback program indicates that FirstCash Holdings management is prioritizing direct capital returns to shareholders while reiterating its revenue outlook for the rest of 2026.
- Next, the focus turns to how this mix of higher earnings and a larger buyback shapes FirstCash Holdings investment narrative for you.
Compare how FirstCash Holdings is rewarding shareholders with buybacks and dividends against a curated 5 dividend fortresses that is also returning substantial cash to investors.
What Is FirstCash Holdings' Investment Narrative?
To own FirstCash Holdings, you need to be comfortable with a pawn led, cash constrained customer model that depends on steady demand for small collateral backed loans and consistent merchandising of forfeited goods. Recent results show revenue of US$1.10b in the third quarter and net income of US$101.15 million, with year to date earnings of US$302.32 million. Execution hinges on running thousands of locations efficiently, pricing loans and merchandise carefully, and managing credit exposure in the retail POS payment solutions arm without letting funding costs erode those economics.
The fresh dividend increase and larger US$350 million repurchase pool signal that management is putting surplus cash into shareholder return rather than heavy new capital projects. That can support the current investment story if operations continue to support this level of outlay. It also raises the stakes on balance sheet discipline, especially with a high level of debt, higher risk funding sources, and a stock that screens as expensive on P/E versus both fair value estimates and consumer finance peers.
Even so, there is a less comfortable side to this capital return story that starts with management incentives and insider behavior...
There's only one way to know the right time to buy, sell or hold FirstCash Holdings. Head to Simply Wall St's company report for the latest analysis of FirstCash Holdings's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community currently offers 2 fair value estimates for FirstCash Holdings, ranging from about US$94.90 to US$247.50 per share, so opinions already span a wide band. Set those pre-buyback views against the fresh US$350 million authorization and dividend lift, and you get very different readings on how aggressively management is returning cash. Use that spread as a prompt to review several alternate viewpoints before deciding how this capital allocation story fits your own expectations.
Explore another FirstCash Holdings fair value estimate, including one that suggests as much as 37% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your FirstCash Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for FirstCash Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FirstCash Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond FirstCash Holdings?
Once you have a view on FirstCash Holdings, it can help to compare that thesis against other opportunities with different income profiles, balance sheets, or risk levels. The Simply Wall St Screener lets you quickly filter for companies that better match the return and volatility trade off you want.
- If you want income with less drama, start with resilient payers and review a selection of 29 resilient stocks with low risk scores that combine cash returns with lower risk scores.
- For investors who care most about financial strength, focus on durability and funding quality by screening through a list of solid balance sheet and fundamentals (24 results) that can better withstand shocks.
- If you are hunting for potential future standouts, widen the lens with a 19 high quality undiscovered gems that surfaces high quality businesses the market may not be paying close attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com