


Linde’s latest earnings and industrial gas expansion
Linde (NasdaqGS:LIN) has drawn fresh attention after third quarter results showed higher sales alongside lower quarterly profit, paired with a larger industrial gas agreement in India and a reaffirmed dividend.
Linde’s share price has climbed 7.25% over the past month and 19.84% year to date, while the 1 year total shareholder return of 26.45% points to momentum that investors may be linking to steady nine month earnings progress, the expanded Tata Steel supply deal, and the reaffirmed dividend.
Scan how Linde compares with other industrial and materials players showing strong earnings momentum and contract-driven growth using our curated 33 high quality undervalued stocks.
Linde shares have already moved on the latest earnings and Tata Steel deal, so the real tension now is simple: Is this a fair price to pay, or does patience offer a better entry point?
Most Popular Narrative: 6% Undervalued
On the most followed narrative, Linde screens as slightly undervalued, with a fair value estimate of $544.40 against the recent $514.24 close, which puts the current excitement around earnings and new gas contracts in a tighter valuation frame.
The earlier focus on commercial space, electronics and clean hydrogen is now supported by double digit space related growth contributing to manufacturing. The company has a stated path to more than US$1b of space revenue by 2030 and large hydrogen and CCS projects, which together can add higher value revenue streams and support margin mix.
See why 120 investors see Linde as 6% undervalued.
Result: Fair Value of $544.40 (UNDERVALUED)
Still, the narrative around Linde can crack if European industrial demand weakens further or if the U.S. homecare review fails to reduce the current margin drag.
Find out about the key risks to this Linde narrative.
Another View: Linde on richer earnings multiples
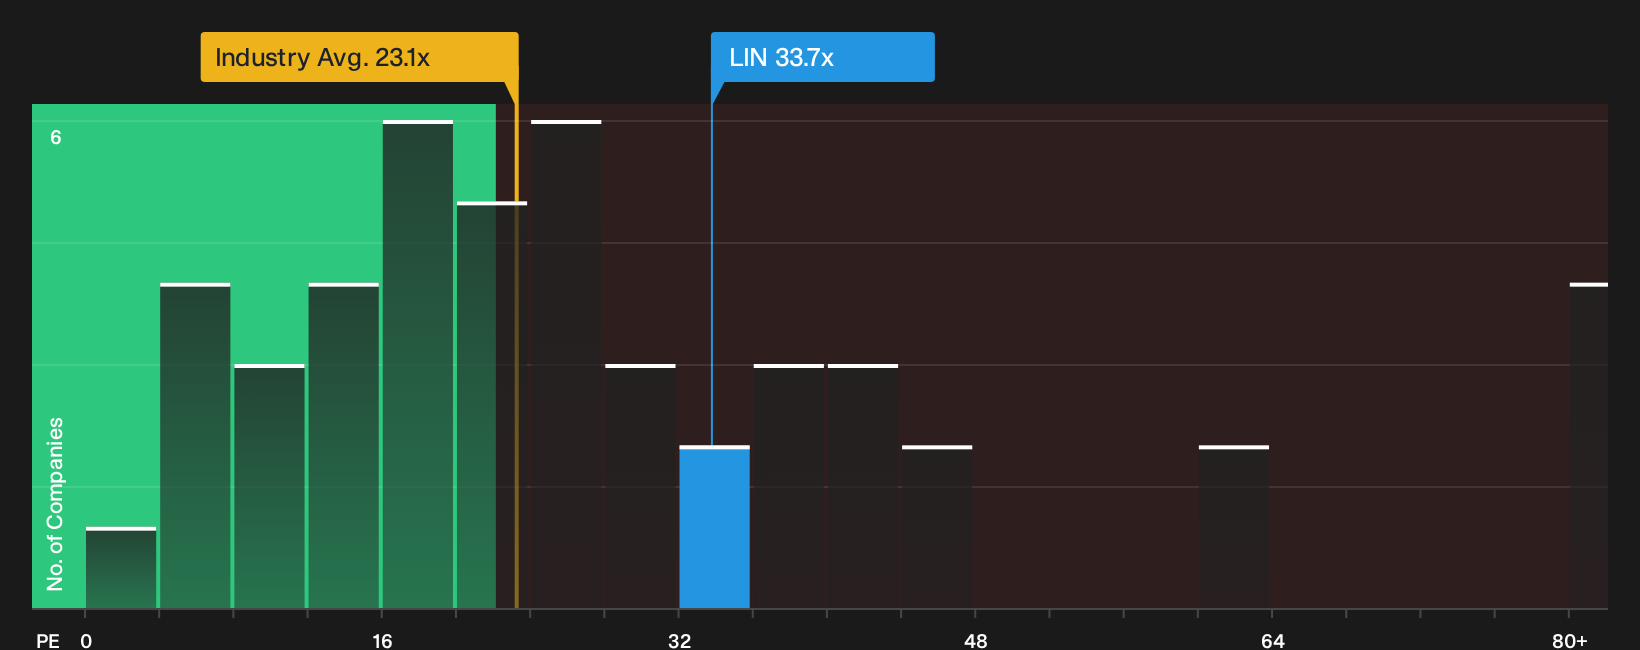
The DCF based fair value of $544.40 presents Linde as modestly undervalued. However, the market is paying a premium P/E of 33.7x compared with a fair ratio of 22.8x, the US Chemicals industry at 23.1x and peers at 30.1x. This raises the question of whether that additional valuation is a source of comfort or a margin of risk.
For a closer look at how this earnings multiple compares with sector norms and the fair ratio the market could move toward over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of mild undervaluation and rich P/E multiples around Linde feels mixed to you, that is the point, and it is why momentum can shift quickly as sentiment adjusts. To weigh the potential upside against the areas that concern investors, take a moment to review the balance of 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Linde?
Once you have a view on Linde, the smartest next step is widening your opportunity set using focused stock lists built from clear, data driven rules.
- Target potential mispricings early by scanning a tightly filtered set of opportunities through the 19 high quality undiscovered gems.
- Prioritise resilience by checking companies that pass strict balance sheet and fundamentals checks using the list of solid balance sheet and fundamentals (24 results).
- Reduce portfolio shocks by focusing on businesses with historically steadier profiles sourced from the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com