


Garmin (GRMN) has put fresh numbers on the table, pairing strong third quarter results with higher full year revenue guidance of about US$8.15b and a completed share buyback tranche that signals management confidence.
Despite the stronger outlook and new product launches in cycling and subscription services, Garmin’s share price has eased in the short term, with the stock down 6.9% over the past week and 11.3% over 90 days. This comes even as the year-to-date share price return of 34.7% and a 3-year total shareholder return of about 147% point to longer running momentum that investors are now reassessing against the higher guidance and ongoing Auto OEM and outdoor segment risks.
Scan how Garmin’s guidance, recurring revenue push and recent pullback compare with other resilient hardware and subscription plays in our hand picked 19 high quality undiscovered gems.
Garmin now trades below its recent highs despite upgraded guidance and new subscription and cycling launches. Does that pullback leave enough potential upside in the valuation to compensate for pressure in Auto OEM and outdoor?
Most Popular Narrative: 9.7% Undervalued
Garmin’s most followed narrative pegs fair value at $302, which sits above the latest close at $272.67 and frames the current pullback as a discount relative to those long term assumptions built on recurring services and Fitness strength.
The launch of the Garmin Connect+ premium service, which offers AI based health and fitness insights, is likely to boost subscription based revenue growth and improve overall margins through higher margin services.
The acquisitions of TrainingPeaks and TrainHeroic, which add endurance and strength training platforms around Garmin wearables, are expected to deepen the service ecosystem and create more recurring revenue streams that can support gross margin and operating margin over time.
See why 49 investors see Garmin as 10% undervalued.
Result: Fair Value of $302 (UNDERVALUED)
Still, Garmin’s story can fray if Outdoor weakness persists and if higher memory costs bite harder than expected, which could squeeze the high margin subscription thesis.
Find out about the key risks to this Garmin narrative.
Another View: Garmin On Richer Earnings Multiples
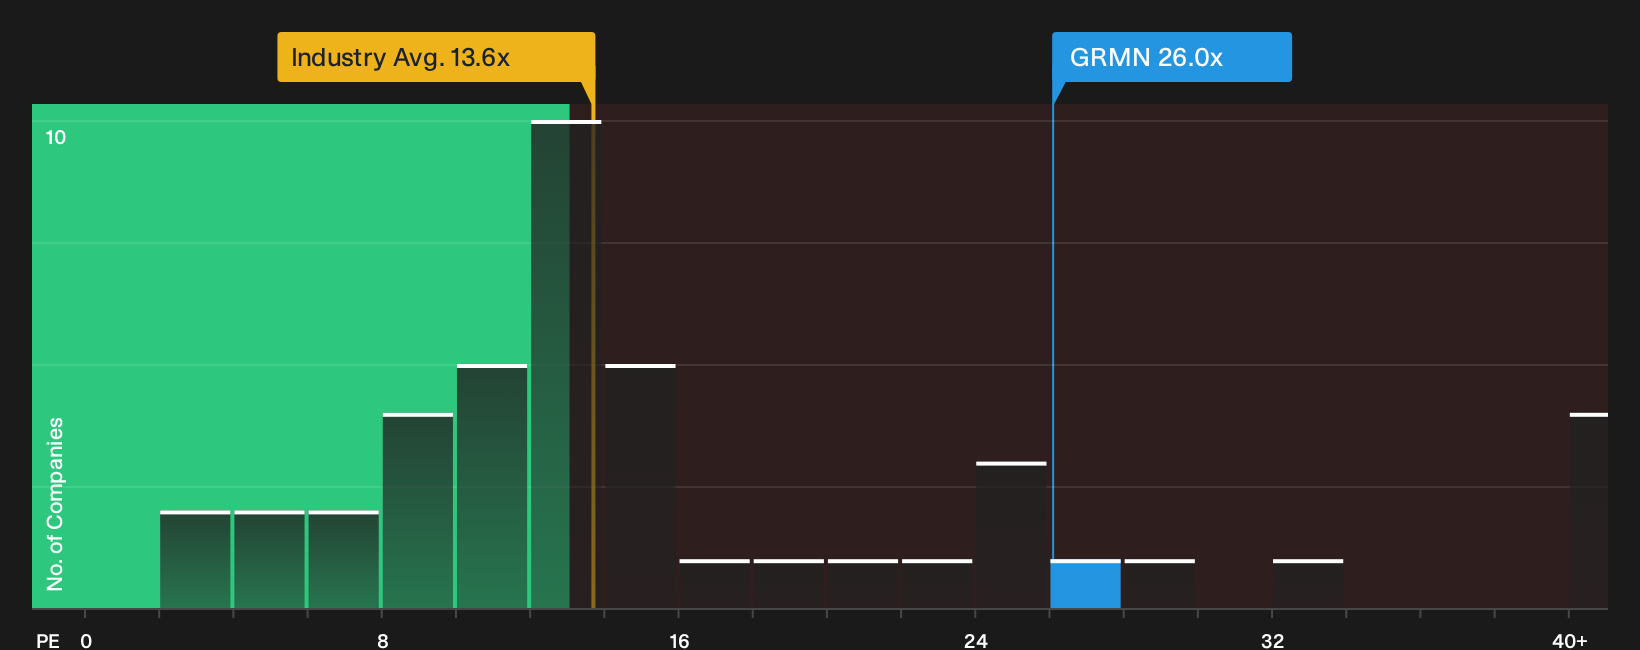
Garmin screens as undervalued on the fair value estimate, yet the current P/E of about 26x tells a different story. That level sits well above the US Consumer Durables sector on 13.6x and even above the stock’s own fair ratio of 25.4x, which points to limited room for disappointment. Is that premium something you are comfortable paying for this story?
For a closer look at how this pricing compares to earnings power over time, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Garmin’s valuation and risk reward profile are hard to ignore, so move quickly, review the underlying data, and pressure test the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Garmin?
If Garmin’s mixed setup has you thinking about diversification, use this moment to line up a few fresh candidates before the next wave of earnings resets expectations.
Stretch your watchlist with potential high quality bargains by scanning the 33 high quality undervalued stocks that combine solid fundamentals with room for sentiment to catch up.
Strengthen your core holdings by reviewing a list of solid balance sheet and fundamentals (24 results) that can help cushion your portfolio when conditions get choppy.
Dial back portfolio stress by hunting through 29 resilient stocks with low risk scores that score well on resilience so you are not scrambling after the next surprise hits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com