


Investor attention has turned to Hydro One (TSX:H) ahead of its third quarter 2026 results on November 10, with sentiment shaped by recent commentary on financial trends and ongoing electricity infrastructure spending.
Recent trading has leaned positive, with Hydro One’s share price up 8.68% over the past month and the 1-year total shareholder return at 10.49%, while a weaker 90-day share price return of 4.73% suggests momentum has been rebuilding only in the short term.
Scan how Hydro One compares with other grid and utilities plays by reviewing our curated list of 42 power grid technology and infrastructure stocks in the current market backdrop.
Bulls see Hydro One’s recent 8.68% move as confirmation of a steady, regulated earner, while bears point to financing costs and modest value scores. The key question is whether the current price still offers a reasonable deal on fundamentals.
Most Popular Narrative: 2.5% Undervalued
Hydro One’s most followed narrative pegs fair value at CA$56.67 per share, slightly above the last close of CA$55.24. This frames the current debate around how much of its long-term grid buildout is already reflected in the price.
Hydro One’s proposed $37b of transmission and distribution investments for 2028 to 2032, aimed at modernizing aging infrastructure and connecting about 6,000 MW of new demand, would add materially to the regulated rate base and support future revenue and earnings growth.
See why 35 investors see Hydro One as 3% undervalued.
Result: Fair Value of CA$56.67 (UNDERVALUED)
Still, the narrative around Hydro One can shift quickly if regulators push back on cost recovery or if funding that C$37b buildout increases pressure on earnings per share.
Find out about the key risks to this Hydro One narrative.
Another View: Hydro One Through The P/E Lens
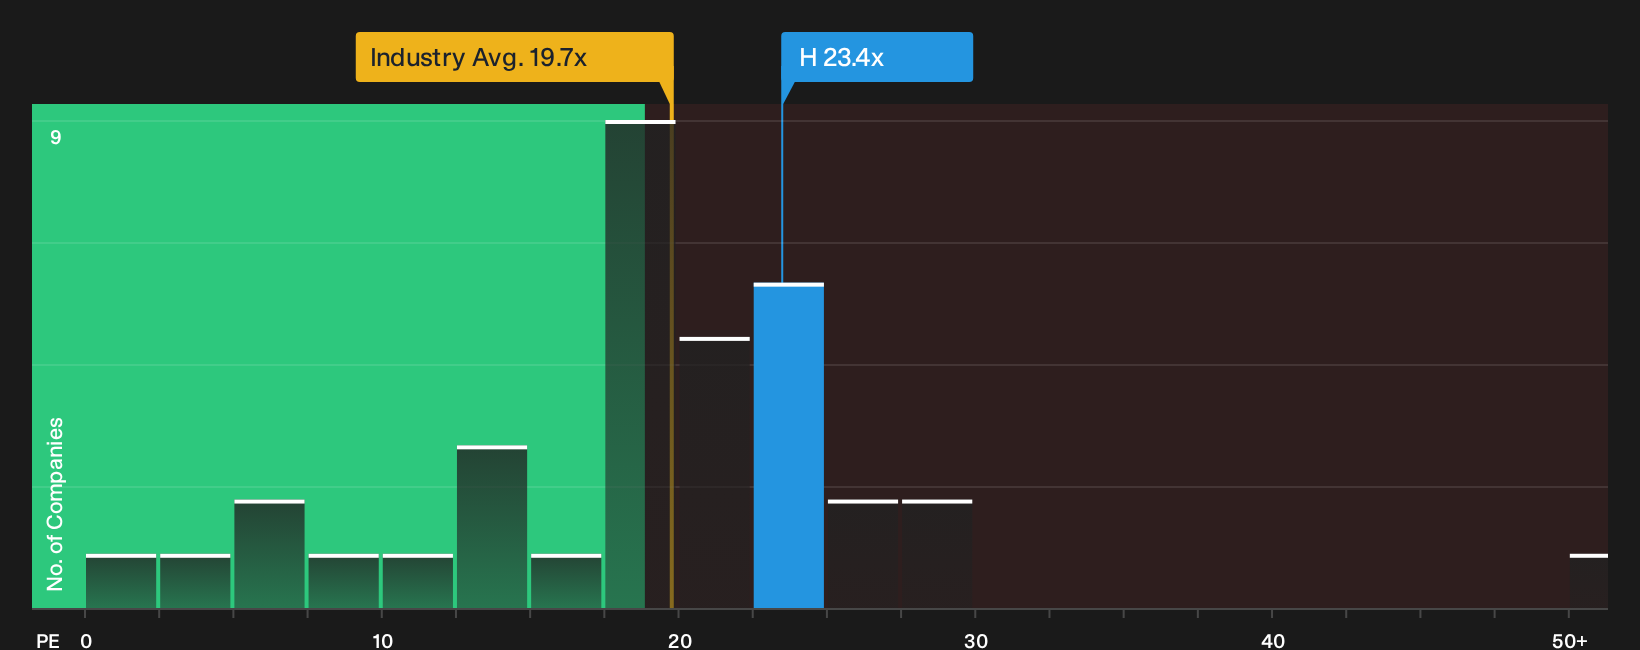
While fair value around CA$56.67 suggests Hydro One is modestly undervalued, the earnings multiple tells a tougher story. The stock trades on a P/E of 23.4x compared with 19.7x for the North American electric utilities group and 21.7x for peers, even though the fair ratio points to 30.9x. That mix of premium versus sector but discount to the fair ratio leaves a simple question for investors: Is this a safety premium worth paying, or valuation risk that needs a margin of safety?
To see how the current pricing stacks up against that fair ratio view and where the pressure points might be if sentiment shifts, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Hydro One story so far. If you want to move quickly and build your own stance from the ground up, consider weighing both sides of the equation through 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Hydro One?
Hydro One may anchor your watchlist, but keeping your edge means constantly refreshing the rest of your lineup with fresh, high quality opportunities.
- Target potential mispricings by scanning a focused set of opportunities with the 4 high quality undervalued stocks tailored to strong fundamentals and sensible pricing.
- Build a more resilient portfolio by tapping into the 9 resilient stocks with low risk scores that filters for businesses with steadier profiles and fewer red flags.
- Spot under-the-radar opportunities early by working through the 8 high quality undiscovered gems before other investors start paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com