


Columbia Financial has delivered a strong share price run over the past year, and the gains put fresh attention on a basic question for investors. Is the current price supported by what the bank actually earns today, rather than by optimism alone?
- The stock has returned 65.4% over the past year, which makes the link between that jump and the company’s earnings power impossible to ignore.
- Recent earnings following the Northfield acquisition added scale, higher loan balances and a stronger net interest margin, which can reshape how investors think about Columbia Financial’s profit potential per share.
- The analysts covering Columbia Financial have run their own numbers. See what analysts think Columbia Financial's shares could be worth.
The issue now is whether the earnings that Columbia Financial generates today are enough to justify the price that the market is asking for the stock.
If you are evaluating Columbia Financial based on its earnings, it may be useful to see how other businesses compare on similar metrics by reviewing 33 high quality undervalued stocks.
Does Columbia Financial Look Pricey on Earnings?
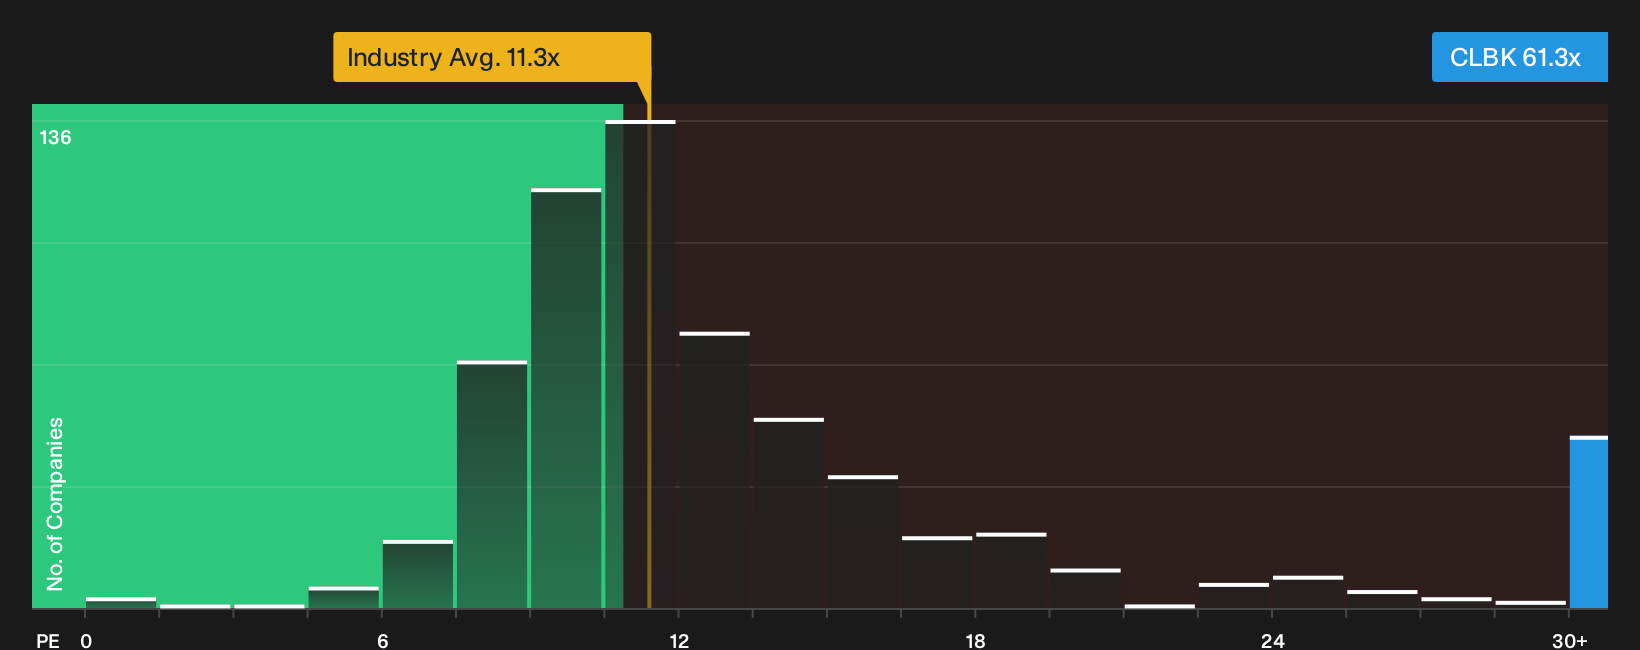
P/E is a useful yardstick for Columbia Financial because banks are often judged on the earnings power of their loan and deposit franchises. On that metric, the stock trades on a P/E of 61.3x, compared with an industry average of about 11.3x for banks and a peer group closer to 10.9x. That is a sizeable gap, which means each dollar of Columbia Financial’s earnings is being valued far more highly than the sector norm.
The fair multiple implied by the valuation model, which blends factors such as profitability, risk profile and scale, sits well below the current P/E, so the shares screen as overvalued on this framework. Despite the Q3 uplift from the Northfield acquisition and a higher net interest margin, the current P/E already reflects a significant level of optimism about how durable those earnings will be. For anyone considering the stock, the key question is whether Columbia Financial’s future results can support what a 61.3x earnings tag is asking the business to deliver over time. Explore the numbers behind Columbia Financial's P/E valuation.
The Columbia Financial Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St take the valuation puzzle around Columbia Financial and explain what would need to happen to growth, margins and earnings for the share price to look materially higher or lower than it does today. They use a set of plain, alternative paths that each link a number to a clear view of how the bank's prospects and risks might evolve over time so you can revisit those assumptions as fresh information arrives.
A clear, written narrative on Columbia Financial gives you a reference point that ties the recent Northfield acquisition, the larger balance sheet and the 2.96% net interest margin to explicit assumptions about earnings power per share. It turns those expectations into numbers you can later check against how integration costs, loan growth and core profit actually unfold over time.
Share your own Narrative for Columbia Financial and set out the assumptions behind your valuation.
One last Columbia Financial check before you stop at the share price
Before you call your view complete, it is worth weighing who is steering Columbia Financial and how their pay packets line up with your interests. See who runs Columbia Financial and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com