


TG Therapeutics has delivered a striking run in recent years, and the pace of that move puts fresh scrutiny on what investors are paying for its earnings today. With new clinical data in multiple sclerosis gaining attention, the central question is whether the current share price lines up with what the business is earning now rather than what might be possible far down the road.
- Over roughly three years, TG Therapeutics has produced a very large share price gain of about 7x, which puts meaningful weight on whether its earnings profile can support that kind of re-rating.
- Fresh results around BRIUMVI dosing and early data on the azer cel program may support expectations for future revenue and margin potential, which filters directly into how much investors are willing to pay per dollar of profit.
- The analysts covering TG Therapeutics have run their own numbers. See what analysts think TG Therapeutics's shares could be worth.
The issue now is whether TG Therapeutics' current valuation is justified by its earnings when set against the Fair Ratio benchmark.
If you want to test the same earnings based valuation question that hangs over TG Therapeutics against a wider field, scan through the 33 high quality undervalued stocks
.Does TG Therapeutics Look Undervalued on Earnings?
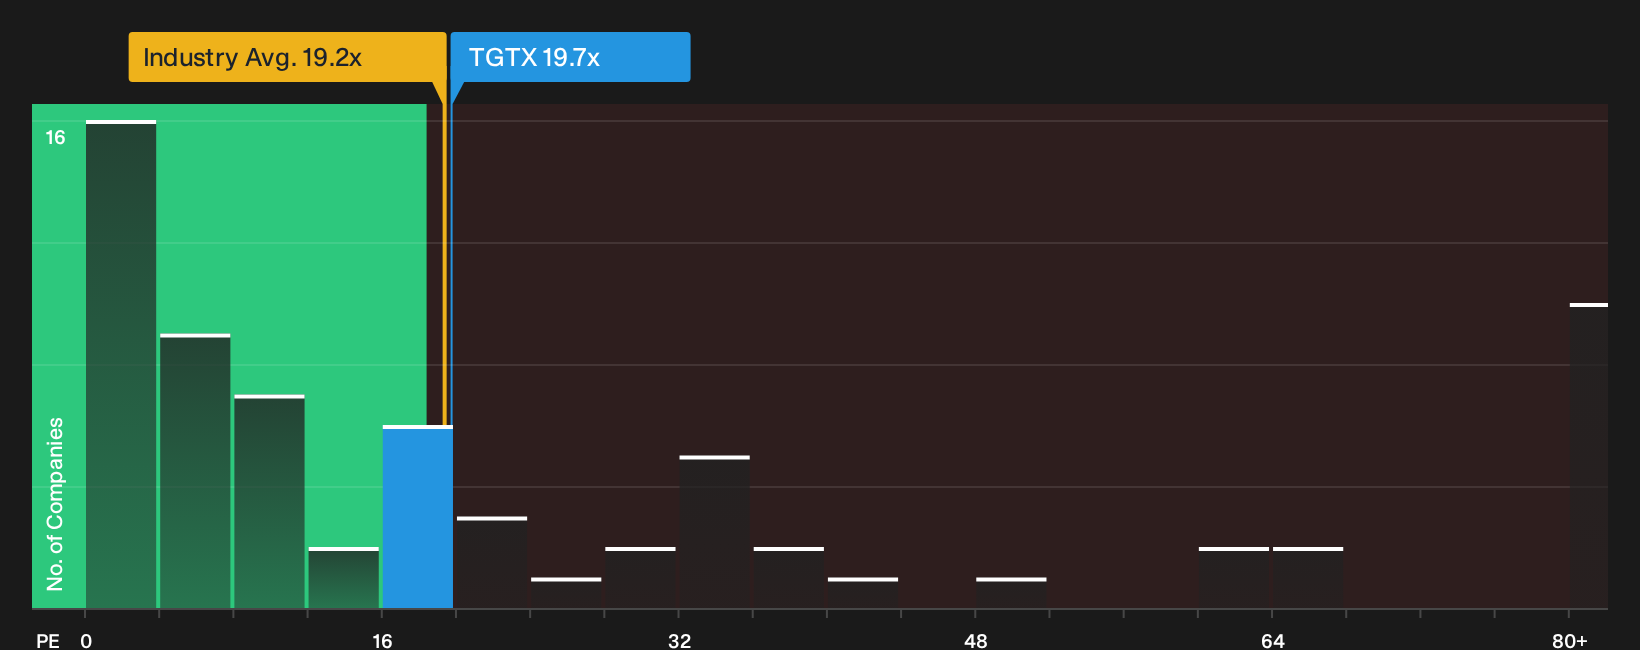
P/E fits TG Therapeutics because investors are mainly weighing how much they are paying for each dollar of current profit as BRIUMVI and the MS pipeline gain attention. The stock trades on roughly 19.7x earnings, which is close to the broader biotech sector average of about 19.2x and well below the peer group nearer 60.0x. That comparison indicates the share price does not reflect the same rich premium that many higher multiple biotech stocks carry.
Because a tailored Fair Ratio suggests TG Therapeutics could warrant a higher P/E than where it trades today, the current multiple screens as undervalued on this framework. The recent BRIUMVI and azer cel data have sharpened the story around MS, yet the P/E still sits below what this model implies might be appropriate for the business profile. Explore the numbers behind TG Therapeutics's P/E valuation.
The TG Therapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for TG Therapeutics pick up where the valuation puzzle leaves off. They spell out which future paths for growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price, and show the assumptions that sit behind a single ratio or model so you can watch in real time whether those conditions actually play out on Simply Wall St's Community page.
The Simply Wall St community is split on TG Therapeutics, with one camp seeing an emerging autoimmune platform and the other worried that costs and governance risks are doing too much of the heavy lifting in the current price.
Bull case: 12% undervalued
"The planned launch of subcutaneous BRIUMVI remains a key upcoming catalyst, as it targets the 35 to 40% of the anti CD20 multiple sclerosis market…"
Discover why this Narrative puts TG Therapeutics at 12% undervalued.
Bear case: 112% overvalued
"Although TG Therapeutics reports high gross margins on BRIUMVI and growing operating income, the recent earnings miss where diluted EPS of $0.05 fell well short of expectations…"
Explore why this Narrative puts TG Therapeutics at 112% overvalued.
One more piece of the TG Therapeutics puzzle that is easy to miss
Everything so far has focused on what TG Therapeutics earns today, yet there is a separate set of expectations that professional analysts have mapped out for the next few years. Explore where analysts expect TG Therapeutics to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com