


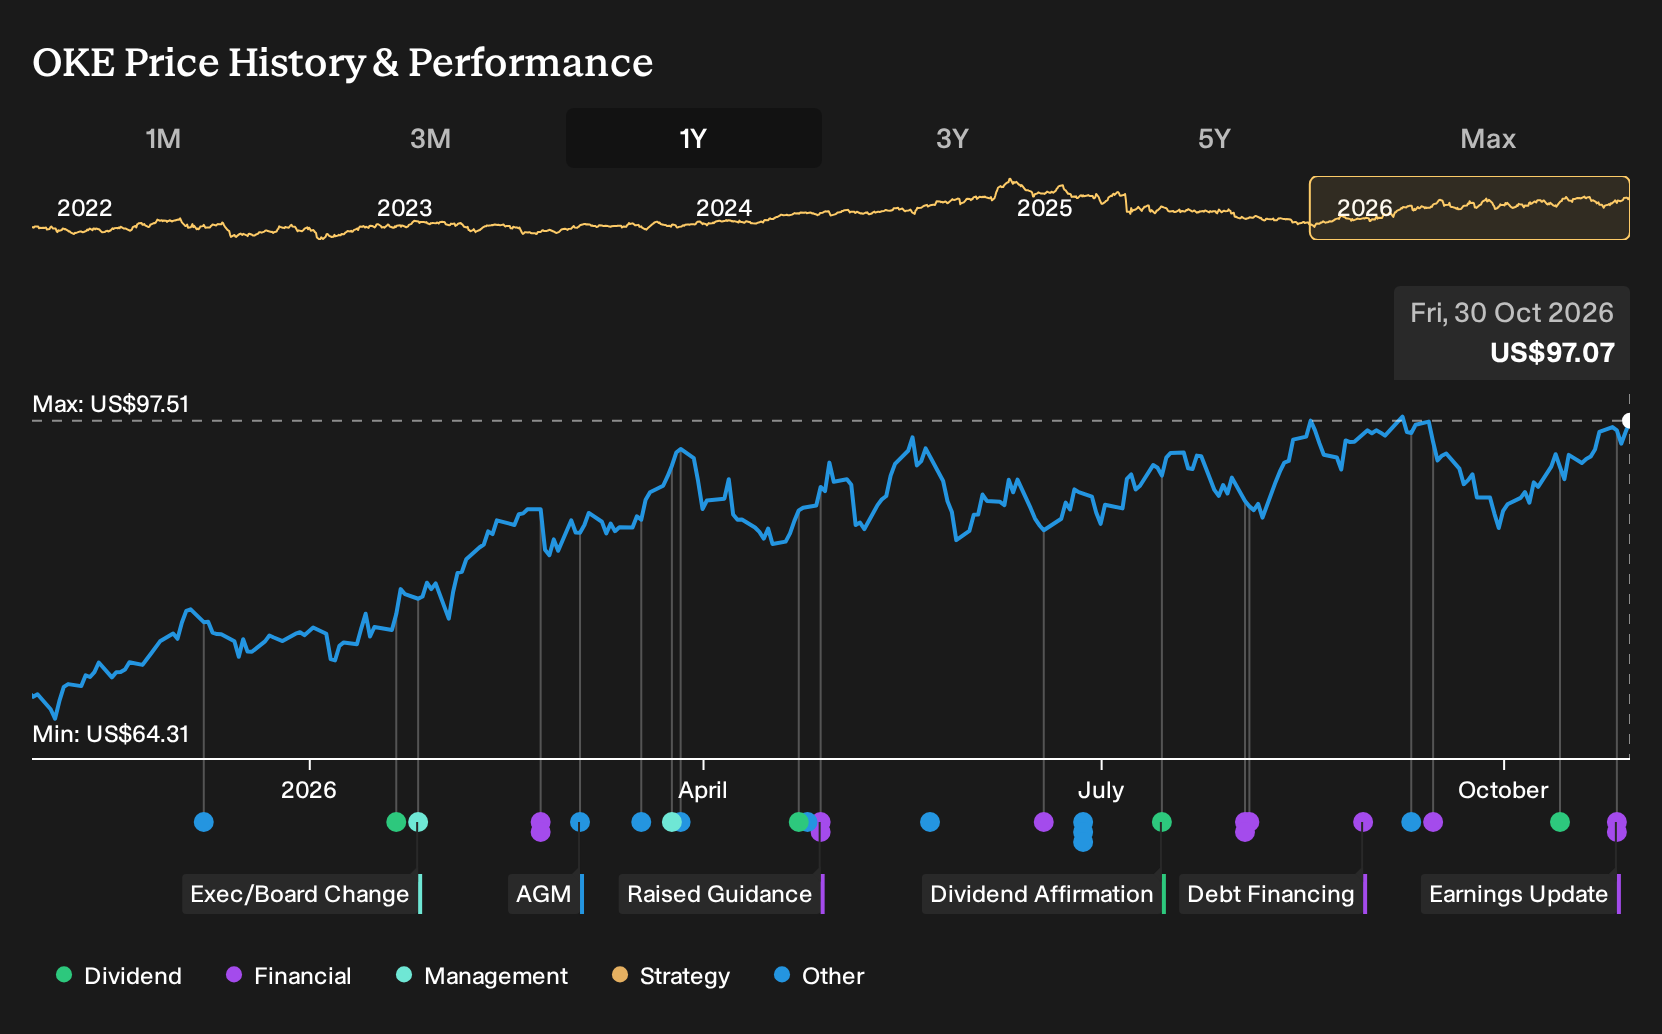
- ONEOK, Inc. reported third quarter 2026 revenue of US$12,455 million and net income of US$1,350 million, with higher basic and diluted earnings per share from continuing operations than the same period in 2025.
- The full year 2026 guidance now points to net income between US$4.09b and US$4.27b, reflecting management’s confidence in the durability of ONEOK’s fee based midstream earnings profile.
- We will now see how ONEOK’s investment narrative could be influenced by this stronger earnings result and the raised 2026 profit guidance.
Scan for other midstream and infrastructure plays that are showing similar earnings momentum to ONEOK by using our curated 42 power grid technology and infrastructure stocks.
ONEOK Investment Narrative Recap
To own ONEOK, you need to be comfortable with a fee based midstream model that leans on volume growth, export infrastructure and integration of assets like Brazos Midland rather than big commodity bets. The latest quarter shows higher revenue and net income, which supports that operating story but does not erase segment specific pressures in Natural Gas Pipelines and NGL margins.
The raised 2026 net income guidance sharpens the near term focus on execution in the Permian and on cost and mix discipline in NGLs. The biggest current risk still sits in weaker spreads and less favorable product mix. This could cap margin progress if market conditions move against ONEOK for longer than management currently assumes.
The most relevant fresh data point for this story is the updated 2026 earnings outlook. Management now guides to net income of US$4.09b to US$4.27b and a diluted EPS midpoint of US$6.30. This connects directly to the third quarter performance and indicates management’s confidence in the durability of the current earnings run rate.
For you as a shareholder, that guidance ties back to the same operational swing factors already on the table. Higher volumes from Permian expansions, Brazos Midland integration and export projects need to offset headwinds in pipeline spreads and NGL mix. If those projects ramp more slowly or require extra capital, the path from this guidance range to future cash flow could look less straightforward.
ONEOK's current earnings sit at US$3.7b and analysts expect earnings to reach US$4.4b by 2029. This implies an increase of about US$0.7b, while revenues are projected at US$40.4b in 2029, with analysts assuming revenue will remain fairly flat over the next few years.
Uncover why ONEOK's fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on ONEOK focuses on a much more optimistic take on Brazos and Texas City. Before this earnings beat and higher 2026 guidance, the most bullish analysts were already penciling in US$55.2b of revenue and US$4.9b of earnings by 2029. That is a very different story. Use this result as a prompt to compare several viewpoints and stress test your own investment thesis.
Explore 4 other ONEOK fair value estimates, including one that suggests there could be as much as 80% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ONEOK research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ONEOK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ONEOK's overall financial health at a glance.
Looking For More Investment Ideas Beyond ONEOK?
If the updated ONEOK story has sharpened your thinking, use that momentum to widen your opportunity set with a few focused screeners tailored to very different investing angles.
- Prioritize financial resilience by filtering for companies with stronger balance sheets and cleaner fundamentals through our list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricings by scanning a curated universe of quality businesses that currently look attractively priced using the 33 high quality undervalued stocks.
- Lean into income ideas by searching for higher yielding companies that pair sizeable payouts with underlying business strength via the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com