


Dividend announcement and what it signals
Tsakos Energy Navigation (NYSE:TEN) caught income investors’ attention after its strategy meeting, announcing a first semi-annual dividend of US$1.00 per share in January 2027, a 100% lift from the 2026 first semi-annual payout.
Against that dividend backdrop, Tsakos Energy Navigation’s recent trading has been strong, with the share price at US$53.85 after a 90 day share price return of 38.68% and a year to date share price return of 146.00%. The 5 year total shareholder return of 695.21% points to powerful longer term momentum.
Scan beyond Tsakos Energy Navigation and compare this dividend move with other companies on our hand picked 5 dividend fortresses to see how income opportunities stack up across the market.
After a rapid rerating and with a sharply higher semi annual payout on the way, does Tsakos Energy Navigation still offer a rewarding balance between potential upside and shipping cycle risk at today’s valuation?
Most Popular Narrative: 14% Undervalued
Tsakos Energy Navigation’s most followed narrative pegs fair value at $62.50, above the last close at $53.85, which frames the current rally as still leaving a valuation gap tied closely to how the tanker cycle and fleet renewal play out.
Tsakos Energy Navigation is committing around $3.1–3.2b to a 20–26 vessel newbuilding pipeline while also adding modern secondhand ships. This increases future capital employed and can lift revenue and earnings expectations well beyond what current contracted cash flows support.
See why 13 investors see Tsakos Energy Navigation as 14% undervalued.
Result: Fair Value of $62.50 (UNDERVALUED)
Still, this fair value story can break if tanker markets soften faster than analysts expect or if Tsakos Energy Navigation’s large vessel program puts pressure on returns.
Find out about the key risks to this Tsakos Energy Navigation narrative.
Another View: Tsakos Energy Navigation Through The DCF Lens
There is a catch. While the popular narrative tags Tsakos Energy Navigation as undervalued on a fair value of $62.50, the Simply Wall St DCF model points the other way, with an estimate of future cash flow value around $37.93 that makes the current $53.85 price look expensive.
This gap matters because it reflects very different assumptions about how long today’s earnings power and tanker conditions can last. If cash flows settle closer to the DCF path rather than the earnings multiple story, how comfortable are you paying up for a shipping business that screens rich on that model?
Look into how the SWS DCF model arrives at its fair value.
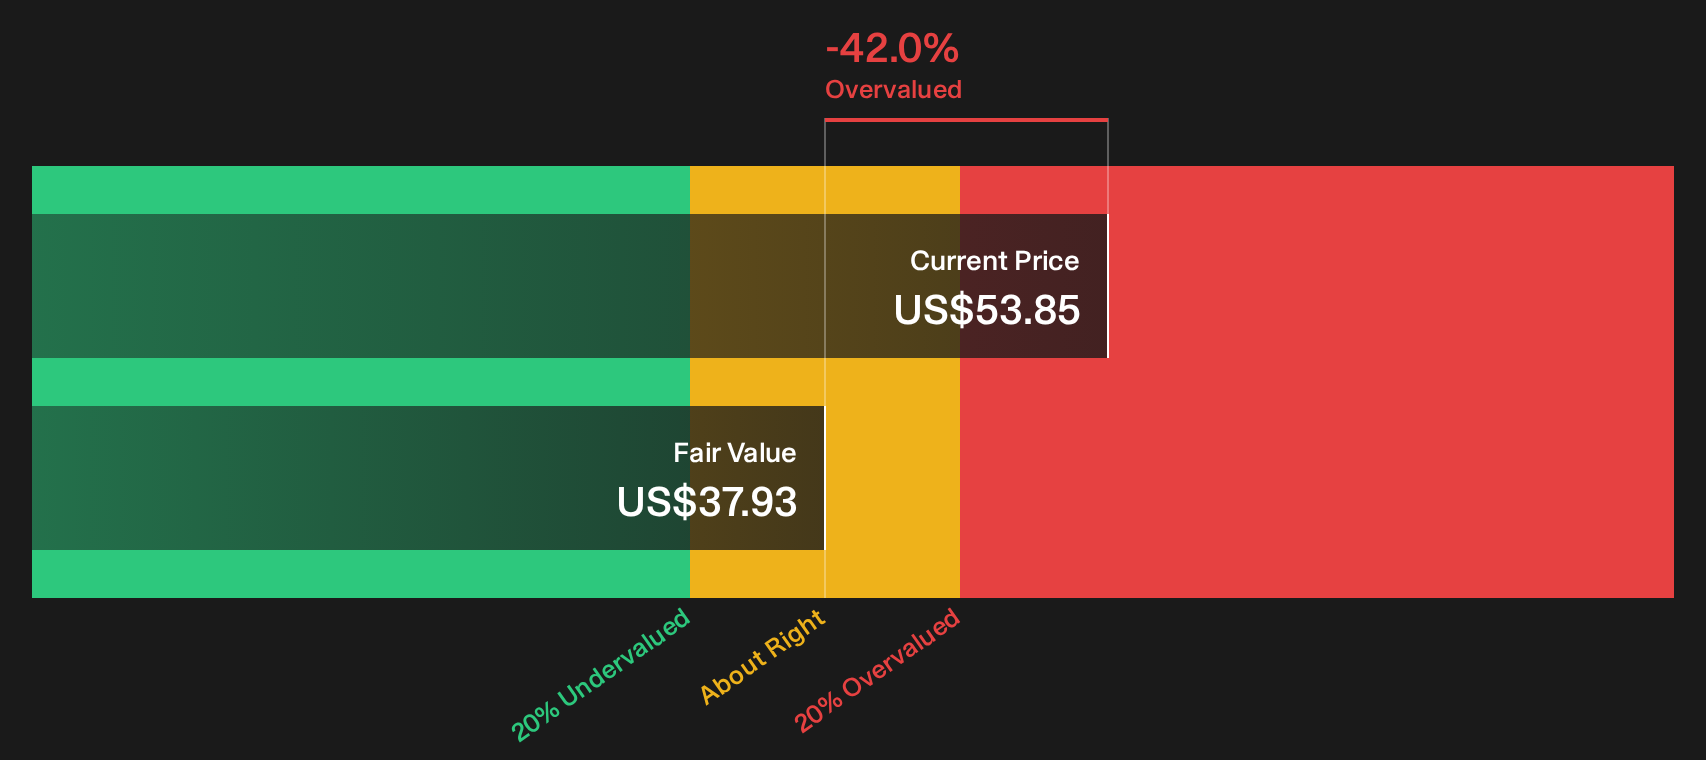
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tsakos Energy Navigation for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Tsakos Energy Navigation so far, or just a complex setup that needs context. Act while the data is fresh, weigh both sides carefully and ground your view in the 3 key rewards and 4 important warning signs.
Looking for more ideas beyond Tsakos Energy Navigation?
Do not stop with Tsakos Energy Navigation. Broaden your watchlist with fresh ideas sourced from objective screeners so you are not caught chasing yesterday’s winners.
- Target financial resilience and consistent balance sheets by scanning a list of solid balance sheet and fundamentals (24 results) that highlights businesses with fundamentals many investors overlook.
- Hunt for quality at a reasonable price by reviewing a 33 high quality undervalued stocks short list that filters for strong cash flows and supportive balance sheets.
- Identify potential income ideas before the crowd by focusing on a curated 8 elite penny stocks with strong financials that spots smaller companies with stronger financials than their size suggests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com