


Why Paymentus Holdings’ Q3 Update Matters Now
Paymentus Holdings (PAY) is in focus as investors look ahead to its Q3 2026 earnings release and call today after the market close, with attention on revenue trends and pricing pressures.
The scheduled update follows a period where Paymentus has reported real-time, omnichannel bill payment growth, alongside pressure from larger clients on pricing. This quarter’s commentary on contracts and margins may shape how investors view the company’s biller-focused platform.
Paymentus Holdings enters this Q3 update with the share price at $32.82 and a recent pattern that mixes short bursts of optimism with heavier swings in sentiment. The stock has a 1 month share price return of 6.45% and a year to date share price gain of 15.28%. However, the 3 month share price return is down 26.41%, which signals that momentum has cooled ahead of the results even as the 3 year total shareholder return of 117.49% and 1 year total shareholder return of 14.72% keep the longer story firmly in positive territory.
Compare Paymentus Holdings with other payment and fintech platforms that could be setting up their next move through the 19 high quality undiscovered gems.
After a 3 month pullback that sits against a much stronger 3 year return, Paymentus Holdings now prompts a simple question. Does the current setup still tilt risk and reward toward buyers before earnings reset the valuation narrative?
Most Popular Narrative: 18% Undervalued
Paymentus Holdings’ most followed narrative pegs fair value at $40.14 versus the latest close at $32.82, so the market price sits well below that estimate while analysts model the story using a 7.28% discount rate.
The AI native Service Commerce stack, including patented BillWallet, Billeo and AI360 products that already show early user adoption without marketing spend, positions Paymentus Holdings to capture new software and AI driven payment use cases. These can add higher margin revenue streams and support adjusted EBITDA growth.
See why 12 investors see Paymentus Holdings as 18% undervalued.
Result: Fair Value of $40.14 (UNDERVALUED)
Still, if large enterprise clients push harder on discounts and investor confidence weakens again, the bullish Paymentus Holdings narrative could quickly look stretched.
Find out about the key risks to this Paymentus Holdings narrative.
Another View on Paymentus Holdings’ Valuation
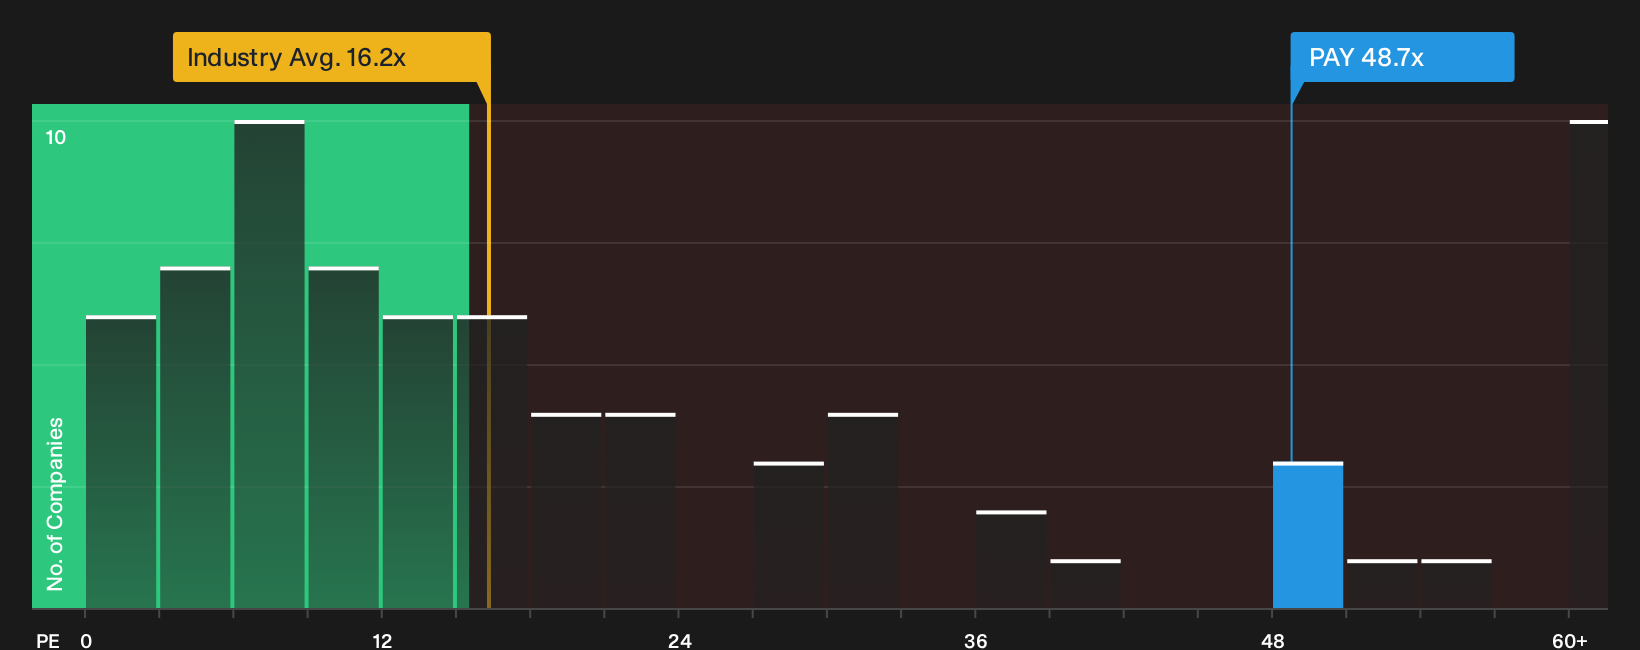
The story looks very different when you shift from analyst fair value to plain P/E math. Paymentus Holdings trades on a 48.7x P/E. That is far above both peers at 33.4x and a fair ratio of 16.5x. If sentiment cools, the share price could move toward those lower anchors instead.
To see how that premium compares visually and what it might mean for valuation risk, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Paymentus Holdings is mixed, with optimism on long term potential and concern around risks pulling in the opposite direction. Use the tools available and pressure test the data yourself before taking a stance, starting with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Paymentus Holdings?
If Paymentus Holdings has your attention, do not stop there. Broaden your watchlist with a few focused ideas that target quality, value and resilience across the market.
- Target steady compounding potential by reviewing a curated 33 high quality undervalued stocks that combines quality fundamentals with valuations that may leave some upside on the table.
- Prioritise durability and financial strength by scanning a list of solid balance sheet and fundamentals (24 results) that can help you sidestep weaker businesses when conditions get tougher.
- Spot opportunities before the crowd by checking a 19 high quality undiscovered gems that highlights lesser known companies with fundamentals that already stack up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com