


Webull Corporation has seen its share price come under heavy pressure, and that slide puts fresh focus on a simple question for investors who care about valuation. Do the current earnings of Webull make the present price look well supported, or is the market asking too much from the business today?
- Over the past 3 years the stock has fallen 52.4%, which puts earnings firmly in the spotlight as investors weigh whether that drop has already reset expectations or not.
- Recent news ranging from a securities fraud class action focused on China ties to new AI powered tools and extended hours options trading can influence how durable Webull's profit engine looks, and how predictable future earnings may be.
- There is a second opinion on Webull worth weighing. See what analysts think Webull's shares could be worth.
The issue now is whether Webull's current share price is adequately explained by what the company is earning today and what those earnings suggest about its long term profitability.
If you are weighing Webull's recent volatility and legal headlines against its earnings story, it can help to compare it with other companies screened for 33 high quality undervalued stocks
Does Webull Look Pricey on Earnings?
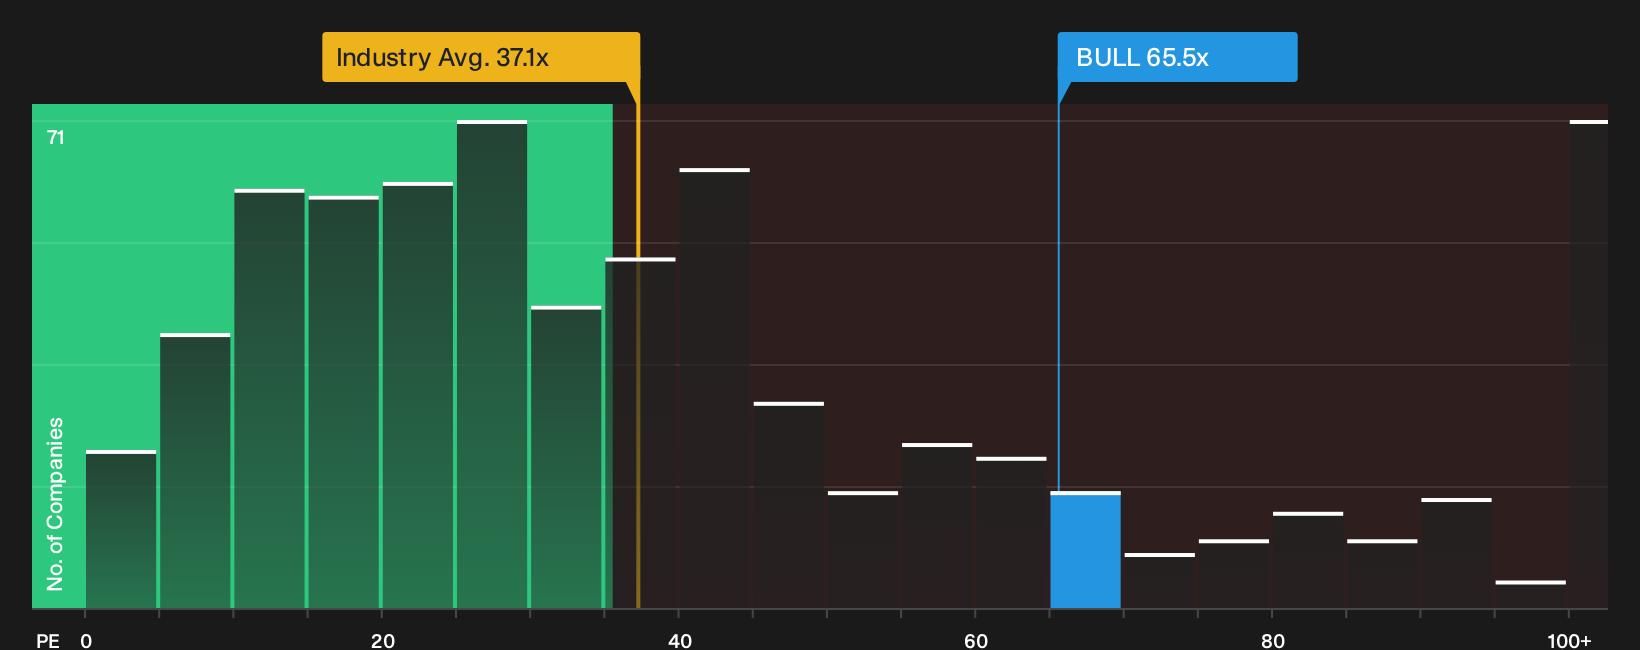
The P/E ratio works well for Webull because earnings are currently positive and give you a concrete yardstick for what the market is paying. Right now the stock trades on roughly 65.5x earnings, which is well above the Capital Markets industry average near 37.1x and also higher than the peer group around 15.0x. On simple comparison, the market is attaching a much richer earnings tag to Webull than to many similar businesses.
The Fair Ratio model, which blends factors like growth profile, profitability, size and risk, points to a lower P/E than where the shares trade today, so on this framework Webull screens as overvalued. Because the securities fraud class action over alleged China ties raises questions about regulatory and reputational risk, that premium multiple asks you to pay up for a business facing extra uncertainty rather than a clean story. Explore the numbers behind Webull's P/E valuation.
The Webull Narrative: What Would Justify Today's Price?
Narratives pick up where Webull's valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to hold for the stock to look meaningfully cheap or expensive versus today's price. Each one treats Webull's implied fair value as a hypothesis about the business that can be revisited over time, so you can see how the story holds up as new information arrives on Simply Wall St's Community page.
One of the top community narratives on Webull: 54% undervalued
"The successful launch and acceleration of subscription-based offerings such as Webull Premium and paid analytics products are already exceeding targets..."
Discover why this Narrative puts Webull at 54% undervalued.
One more Webull signal to check before you decide
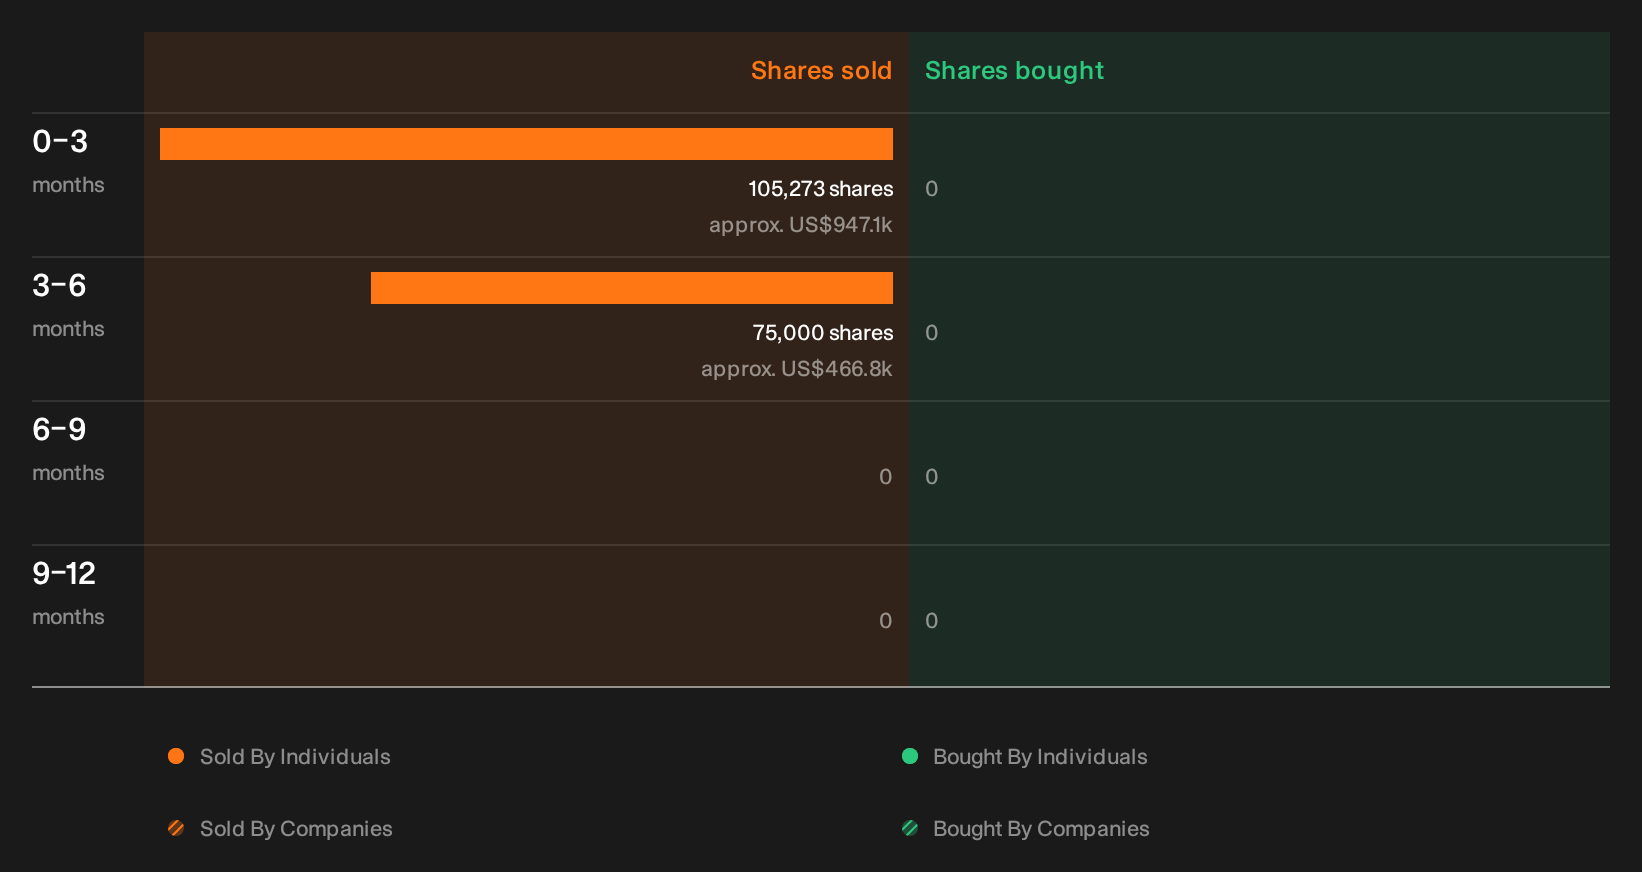
Before you lean too heavily on Webull's earnings multiple or narrative, it is worth pausing on what company insiders have been doing with their own holdings, and what that activity might suggest for you. See the recent insider selling flagged for Webull.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com