


Event backdrop and why Sanmina matters now
Sanmina (SANM) recently bought ZT Systems' manufacturing business and was moved from the S&P SmallCap 600 to the S&P MidCap 400. These shifts highlight its role in cloud and AI infrastructure hardware.
Recent trading has been choppy. The share price fell 4.23% in the last session and is down 22.88% over 30 days, even though the year to date share price return is 4.05% and the 1 year total shareholder return sits at 20.93%. This suggests that short term momentum has cooled while longer term holders have still been rewarded.
Scan how other AI infrastructure manufacturers are positioned by comparing Sanmina with the hand picked 54 AI infrastructure stocks that are also tied into cloud and data center build outs.
The stock has rerated sharply after a long run of gains, and Sanmina now anchors a bigger role in AI hardware. Do the current fundamentals still justify taking equity risk at this price, or not?
Most Popular Narrative: 36% Undervalued
Sanmina closed at $165.74, while the most followed narrative anchors fair value at $260. This frames the recent pullback as a valuation gap rather than a broken story.
The integration of ZT Systems into Sanmina is now contributing several billions of dollars of annualized revenue, and management continues to point to a path toward at least US$16b of revenue in fiscal 2027. If executed, this would materially lift overall revenue and earnings power.
See why 19 investors see Sanmina as 36% undervalued.
Result: Fair Value of $260 (UNDERVALUED)
Still, the Sanmina story can change quickly if the current US$2.2b inventory build runs into softer AI rack demand, or if insider selling and governance concerns trigger a sharp P/E reset.
Find out about the key risks to this Sanmina narrative.
Another View: What the SWS DCF Model Says About Sanmina
While the crowd narrative anchors Sanmina around a $260 fair value, the SWS DCF model points in a very different direction. On that cash flow view, the stock at $165.74 trades well above an estimated value of $45.75, which frames current pricing as rich rather than discounted. That kind of gap raises the question of which story you rely on more: the earnings and AI rack narrative, or the cash generation math.
For a closer look at how this cash flow view is built and what is baked into the assumptions, Look into how the SWS DCF model arrives at its fair value.
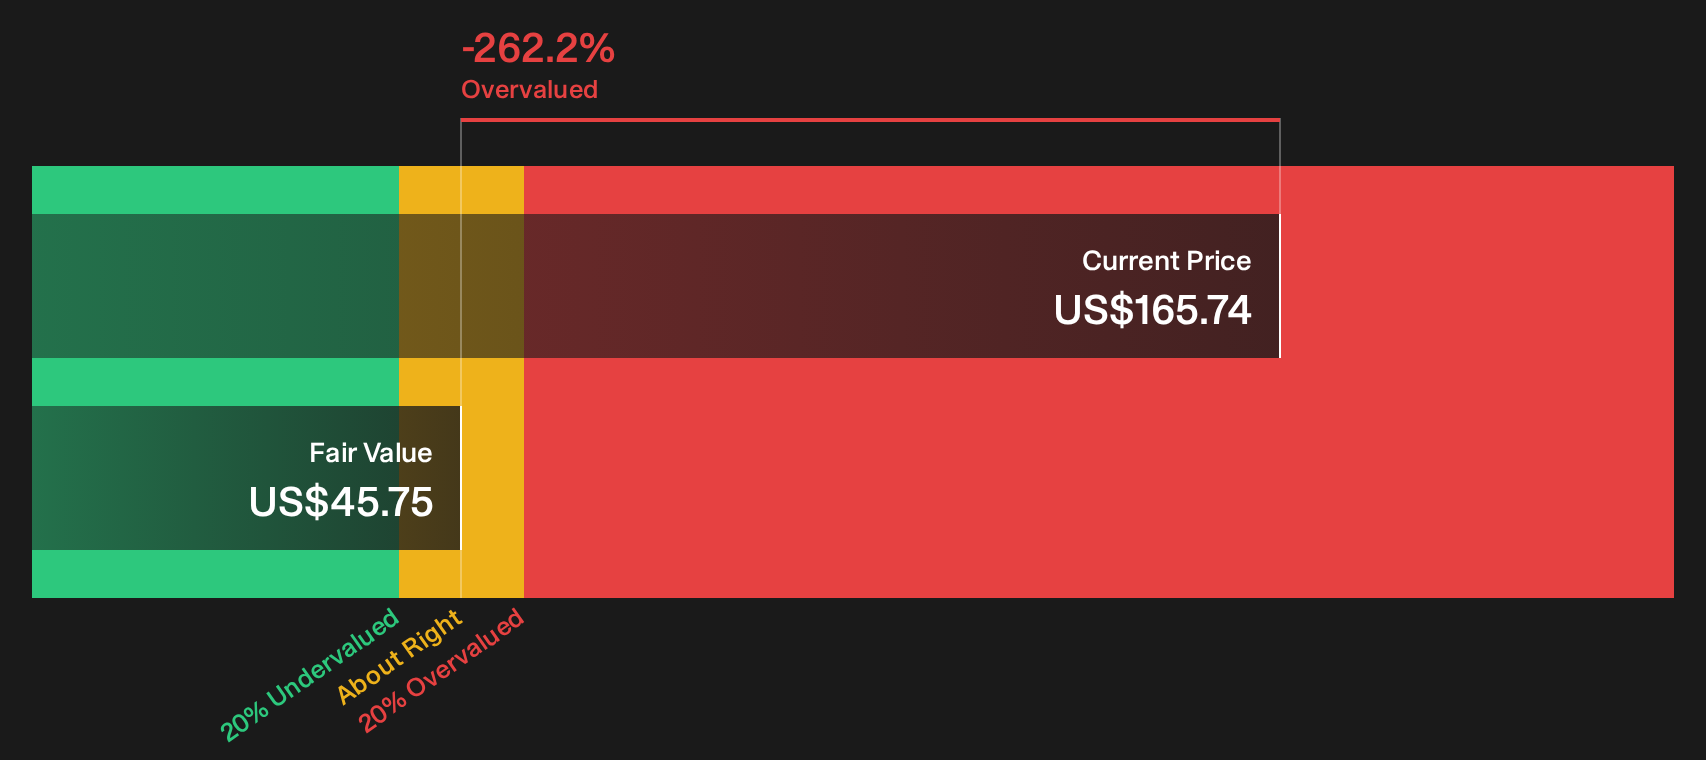
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sanmina for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals across Sanmina can feel confusing, so move fast, review the key upside and downside factors for yourself, then weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sanmina?
If Sanmina has sharpened your focus on opportunity and risk, do not stop here. Broaden your watchlist with other ideas before the next move leaves you behind.
- Target resilient compounding potential by reviewing companies with robust finances and clean balance sheets through the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced potential by scanning the 33 high quality undervalued stocks that combine stronger fundamentals with more appealing entry prices.
- Prioritize stability and cash returns by checking out the 5 dividend fortresses that focus on higher yields backed by sturdier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com