


PPL Corporation has delivered a solid share price run over the past few years, which puts fresh attention on what investors are paying for its earnings today. With the stock changing hands around US$35.65, the key issue is how that price lines up with the utility's current profit power rather than its past share chart.
- PPL has returned about 56.5% over the past 3 years, which puts real weight on whether the current earnings profile can carry that kind of share price level.
- The group's regulated utility model can support relatively steady earnings, so the question becomes how much investors are being asked to pay for that stability through the P/E and related profit multiples.
- Your read on PPL is one view; the desks covering it have another. See what analysts think PPL's shares could be worth.
The issue now is whether PPL's present valuation is adequately supported by its earnings performance and the profit stream investors expect from here.
If you are weighing PPL against other options on the same theme of earnings and value, a focused starting point is a stock screen built around 33 high quality undervalued stocks.
Where Does PPL Sit on Earnings?
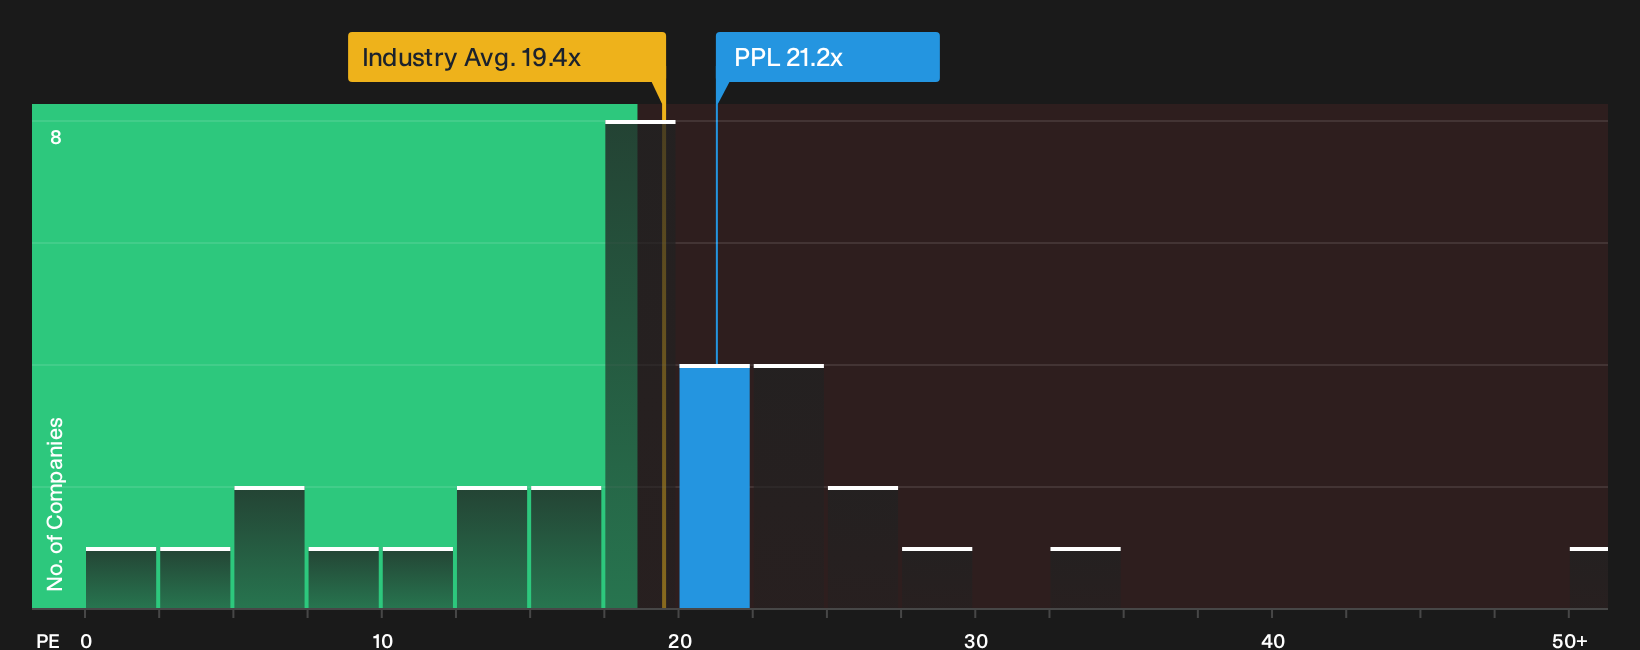
P/E works well for PPL because investors mainly focus on the steady earnings profile of a regulated electric utility. On that yardstick, the stock trades on a P/E of about 21.2x, compared with an Electric Utilities sector average near 19.4x and a broader peer group around 14.1x. So you are paying a higher price for each dollar of current earnings than the typical utility peer.
The fair-value framework that blends PPL specific factors such as margins, risk profile and size points to a P/E level that is close to where the shares are now, so the current multiple sits slightly above that reference but not by a wide margin. For anyone weighing an entry or adding to a position, the key question is whether the earnings profile and dividend stream feel solid enough to justify paying a premium to the sector and to the peer basket on this metric. Explore the numbers behind PPL's P/E valuation.
The PPL Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the PPL valuation puzzle leaves off and explain which earnings, growth and margin paths would need to occur for the share price to look materially higher or lower than today. Each scenario links a specific catalyst and risk mix to an implied fair value for PPL's equity, so you can track over time which version of the story seems to be getting closer to reality on the Community page.
One of the top community narratives on PPL: 11% undervalued
"The current valuation implies the market is discounting PPL's load and capex pipeline and is not fully pricing in the earnings contribution..."
Discover why this Narrative puts PPL at 11% undervalued.
One more angle on PPL that can change how you see the whole story
Valuation only tells you what the market pays for PPL today. The real steering wheel sits with the leadership team and how their rewards line up with your interests. See who runs PPL and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com