


Hornbeck Offshore Services (HOS) has drawn fresh attention after recent trading left the share price at US$7.08, with the stock down roughly 7% over the past month and about 31% year to date.
The recent stretch of weaker momentum, with share price returns declining 6.7% over the past month and 31.5% year to date, points to fading enthusiasm around Hornbeck Offshore Services as investors reassess both its growth potential and its perceived risk profile.
Scan beyond Hornbeck Offshore Services and compare it with a hand picked 33 high quality undervalued stocks that combines compressed prices with solid fundamentals.
Hornbeck Offshore Services now trades at a steep gap to both analyst targets and one estimate of fair value after a sharp year to date slide. Is that discount a margin of safety or a warning sign?
Price-to-Earnings of 17.6x: Is it justified?
Hornbeck Offshore Services changes hands at a P/E of 17.6x, which sits below both the US Energy Services sector average of 24.6x and the 66.1x peer group mean. At a last close of $7.08, that gap suggests the market is applying a lower earnings multiple to HOS than to many comparable stocks.
The P/E ratio links the current share price to the company’s earnings per share and gives you a quick sense of how much investors are paying for each dollar of profit. For a marine transportation and offshore services operator like Hornbeck Offshore Services, this gauge often reflects expectations around contract visibility, vessel utilization, and how durable current profitability might be.
HOS posts high quality earnings and a Return on Equity of 21.3%, while earnings grew 4.5% over the past year and have risen at an annual rate of 31.9% over five years. Revenue is also forecast to grow 32.5% per year, although earnings growth forecasts of 12% per year sit below the wider US market at 17.2%. This can help explain why investors are not willing to pay sector level multiples for those profits.
The comparison is stark. A 17.6x P/E on HOS against 24.6x for the US Energy Services industry and 66.1x for peers points to a clear valuation gap. It suggests the market is either discounting the firm’s higher debt load and new leadership team or giving little credit to its current growth profile relative to other operators.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 17.6x (UNDERVALUED)
Still, the Hornbeck Offshore Services story can change quickly if offshore activity softens or if higher debt costs begin to squeeze those current earnings.
Find out about the key risks to this Hornbeck Offshore Services narrative.
Another View on Hornbeck Offshore Services: Cash Flows Tell a Bigger Story
The earnings multiple paints Hornbeck Offshore Services as cheap, but the SWS DCF model goes much further. On that framework, HOS at $7.08 trades well below an estimated future cash flow value of $30.87. That is a very wide gap. Is it a cushion or a value trap in disguise?
Look into how the SWS DCF model arrives at its fair value.
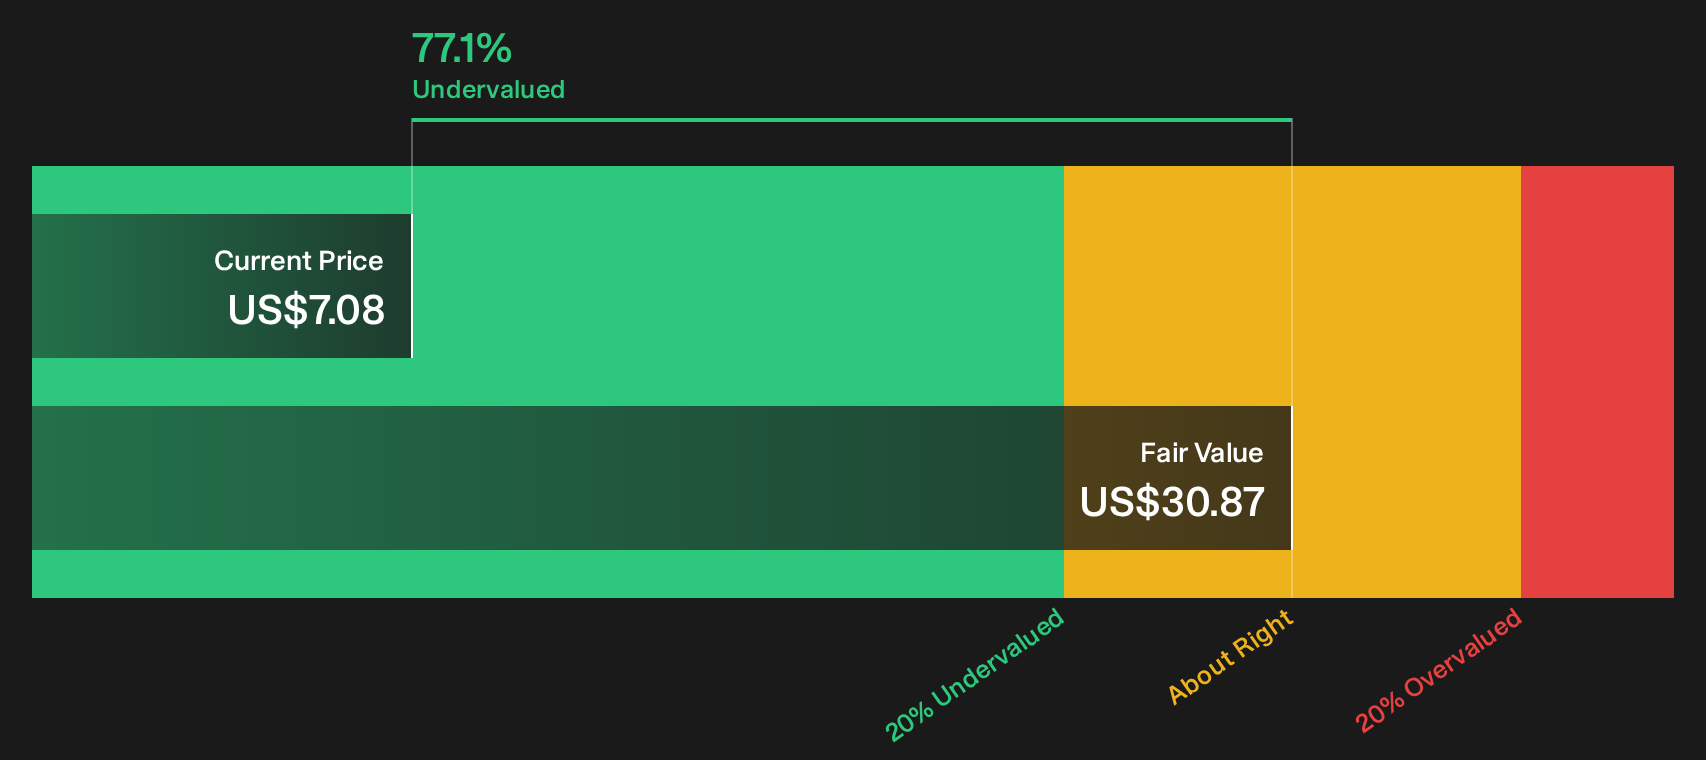
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hornbeck Offshore Services for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Hornbeck Offshore Services looks mixed, so if you care about the full picture, move fast and test the data yourself. To weigh both the concerns and the upside case side by side, check the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Hornbeck Offshore Services?
If Hornbeck Offshore Services has you thinking harder about valuation and risk, use that momentum and line up a few fresh ideas before the next move passes you by.
- Spot potential turnaround stories early by scanning the 8 elite penny stocks with strong financials that already show stronger financial footing than most micro caps.
- Target quality at a discount by combing through the 19 high quality undiscovered gems that pair resilient fundamentals with underfollowed tickers.
- Dial down portfolio swings by focusing on the 29 resilient stocks with low risk scores that keep balance sheets and risk scores front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com