


- Axon Enterprise has launched Axon Body 5 and Axon Body 5 Pro, AI era body cameras with 25x processing power, upgraded connectivity, and longer battery life, aimed at pulling more intelligence and real time support directly into the field.
- The new devices are built to run multiple AI tools on camera, tying officers’ hardware more tightly into Axon’s subscription software ecosystem, such as Axon Fusus, Draft One, Axon Assistant, and Guardian.
- The focus now turns to how Axon Enterprise’s investment narrative could be reshaped by Axon Body 5’s AI heavy, software centric design.
See how Axon Enterprise fits into the broader AI policing trend by comparing it with 54 AI infrastructure stocks that could be gearing up for their own breakout moments.
Axon Enterprise Investment Narrative Recap
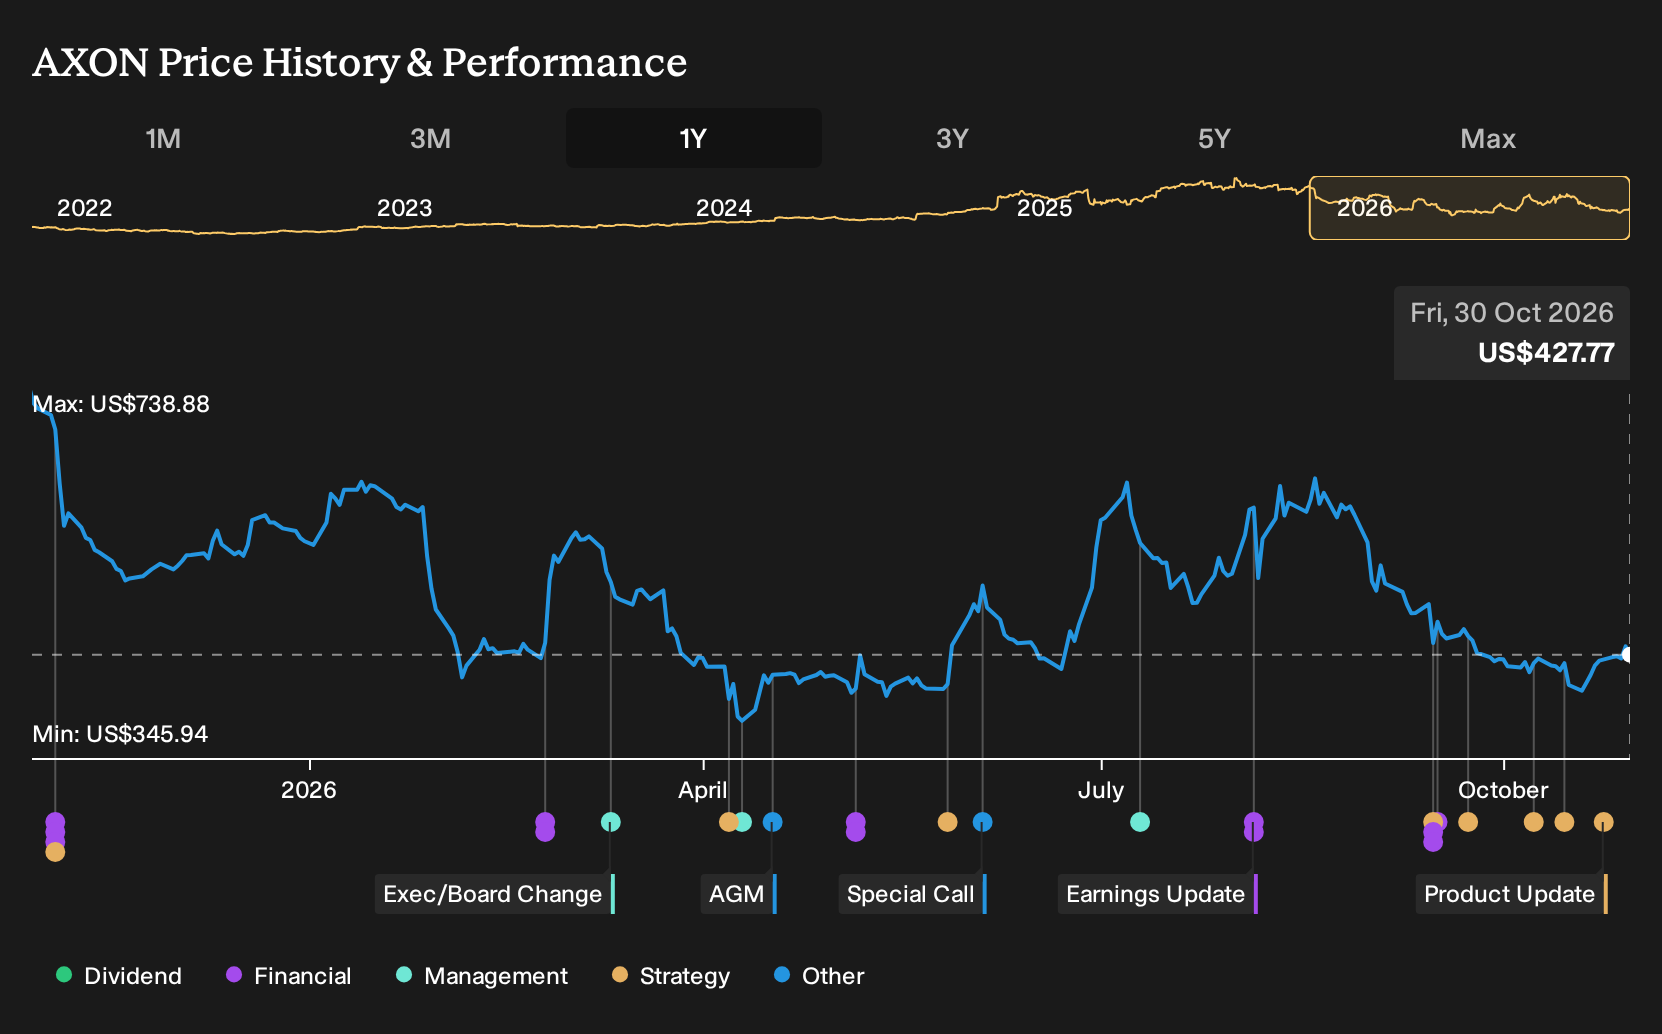
To own Axon Enterprise, you need to be comfortable with a public safety technology firm that is leaning hard into AI heavy, subscription centric tools while still being tied to government budgets and funding cycles. The immediate story hinges on whether demand for premium bundles like the AI Era Plan keeps translating into high value, recurring contracts despite near term cost pressures and mixed recent share price performance.
The Axon Body 5 launch fits that belief cleanly and makes the November 5 earnings call an even more important check on bookings, ARR, and connected device margins. The biggest near risk remains margin pressure from hardware, including counter drone and memory costs, and how effectively Axon Enterprise deploys its recent US$1b convertible note proceeds.
The most relevant piece of context for Axon Body 5 is the rapid uptake analysts already see in newer Axon Enterprise offerings such as Draft One, Axon Assistant, and Axon Body 4, all tied into AI Era Plan revenue growth. Body 5 and Body 5 Pro extend that approach by putting more processing power at the edge and linking directly into Axon Fusus and Guardian.
For catalysts, that matters because it can deepen software usage per customer rather than just adding another camera refresh. The more that agencies move from basic contracts to premium AI bundles that rely on devices like Axon Body 5, the more important execution on uptime, data control, and real world performance becomes, both for renewals and for Axon Enterprise’s ability to support margins over time.
What Axon Enterprise’s AI push means for the stock setup
Axon Enterprise's AI centric camera launch drops into an equity story that analysts already frame around fast top line expansion and steadily higher profitability. Consensus models point to revenue climbing at about 28.8% per year over the next three years, with profit margins edging from 6.2% today toward 6.5% as the mix of subscription software and premium bundles grows.
On earnings, the current snapshot sits at US$199.3 million, with analysts looking for around US$444.1 million by 2029. That implies earnings a little more than doubling, roughly a 2.2x step up, supported by expectations for more agencies to adopt Axon Enterprise platforms such as Axon Fusus, Draft One, and Axon Assistant alongside higher end hardware like Axon Body 5 and Axon Body 5 Pro.
Those same forecasts feed into a long term view of how the stock might be priced. The consensus framework assumes Axon Enterprise could be valued on a P/E of 171.6x those 2029 earnings, compared with about 160.0x on earnings today and 33.9x for the broader US Aerospace & Defense industry based on the report. That is a steep multiple, so it rests on the idea that Axon can keep layering more recurring spend, AI tools, and connected devices into each public safety customer relationship.
Valuation work in the report also bakes in share issuance and the cost of capital. Analysts expect the share count to rise roughly 2.95% each year for the next three years, and they discount future cash flows back using an 8.04% rate. Alongside the recent US$1b 0% convertible note, that puts a lot of emphasis on how effectively Axon Enterprise channels fresh capital into projects that support revenue, earnings per share, and returns on invested funds.
Axon Enterprise's narrative projects US$6.9b revenue and US$444.1 million earnings by 2029. This requires 28.8% yearly revenue growth and an earnings increase of about 2.2x from US$199.3 million.
Uncover why Axon Enterprise's fair value indicates a 59% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view zeros in on regulatory pushback rather than hardware margins. The most cautious Axon Enterprise analysts already modeled about US$6.7b revenue and US$535.1 million earnings by 2029, yet still saw only modest upside. That is a far more restrained story than consensus, and the Axon Body 5 launch could push those expectations in either direction. Readers should treat this as a cue to compare several narratives, not just one headline number.
Explore 4 other Axon Enterprise fair value estimates, including one that suggests it could be worth just $438.43.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Axon Enterprise research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Axon Enterprise. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Axon Enterprise's overall financial health at a glance.
Looking for more Axon Enterprise sized investment ideas?
If Axon Enterprise has sharpened your focus on where growth, resilience, and balance sheet strength intersect, it can help to scan a wider field of candidates that fit your own risk and income preferences using the Simply Wall St Screener.
- For investors hunting for early stage opportunities with stronger fundamentals than the typical micro-cap, consider casting a wide net across the 8 elite penny stocks with strong financials that clear the screener's quality filters.
- If you prefer companies that look attractively priced relative to their financial strength, you could sort through the 33 high quality undervalued stocks to see which ones align with your return and risk expectations.
- For those who care most about capital resilience and cleaner balance sheets, it may be worth starting with a list of solid balance sheet and fundamentals (24 results) and then shortlisting the businesses that best match your long term plan.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com