


Fresh trial data for IMDELLTRA in extensive stage small cell lung cancer and Tezspire in eosinophilic esophagitis has put Amgen (AMGN) back in the spotlight for pipeline driven investors.
All this is landing against a powerful run in the Amgen share price, with a 1-month share price return of 15.62%, a 90-day gain of 19.48% and a year-to-date share price return of 42.23%. The 1-year total shareholder return of 61.64% and 5-year total shareholder return of 157.59% point to momentum that recent trial wins, a fresh dividend declaration and new board appointments have helped reinforce.
Scan how Amgen’s surge compares with other healthcare heavyweights using a curated set of list of solid balance sheet and fundamentals (24 results)
Amgen now appears to be a heavyweight with real clinical momentum and a long track record of shareholder returns. After a run to about $466 a share, the more difficult question is whether that strength is already fully priced in.
Most Popular Narrative: 29% Overvalued
On Simply Wall St, the most followed valuation storyline pegs Amgen’s fair value at $359.98, well below the last close of $466.01. This sets up a sharp contrast between recent price strength and what that framework suggests the shares are worth.
The "Amgen 2027 Bull Case" relies on a classic top-line fallacy: assuming that macro obesity market growth and FDA's CNPV (Commissioner’s National Priority Voucher) tailwinds will automatically trigger a re-rating.
The timeline mismatch is real. MariTide's commercial ramp-up will take years post-launch, while Amgen’s high-margin legacy moats (Prolia and Enbrel) are already eroding at a brutal 30%+ YoY clip right now.
See why 7 investors see Amgen as 29% overvalued.
Result: Fair Value of $359.98 (OVERVALUED)
Still, if Amgen executes on MariTide manufacturing and CNPV remains intact, stronger obesity traction or slower legacy erosion could undercut this cautious valuation story.
Find out about the key risks to this Amgen narrative.
Another View: Amgen Through Market Multiples
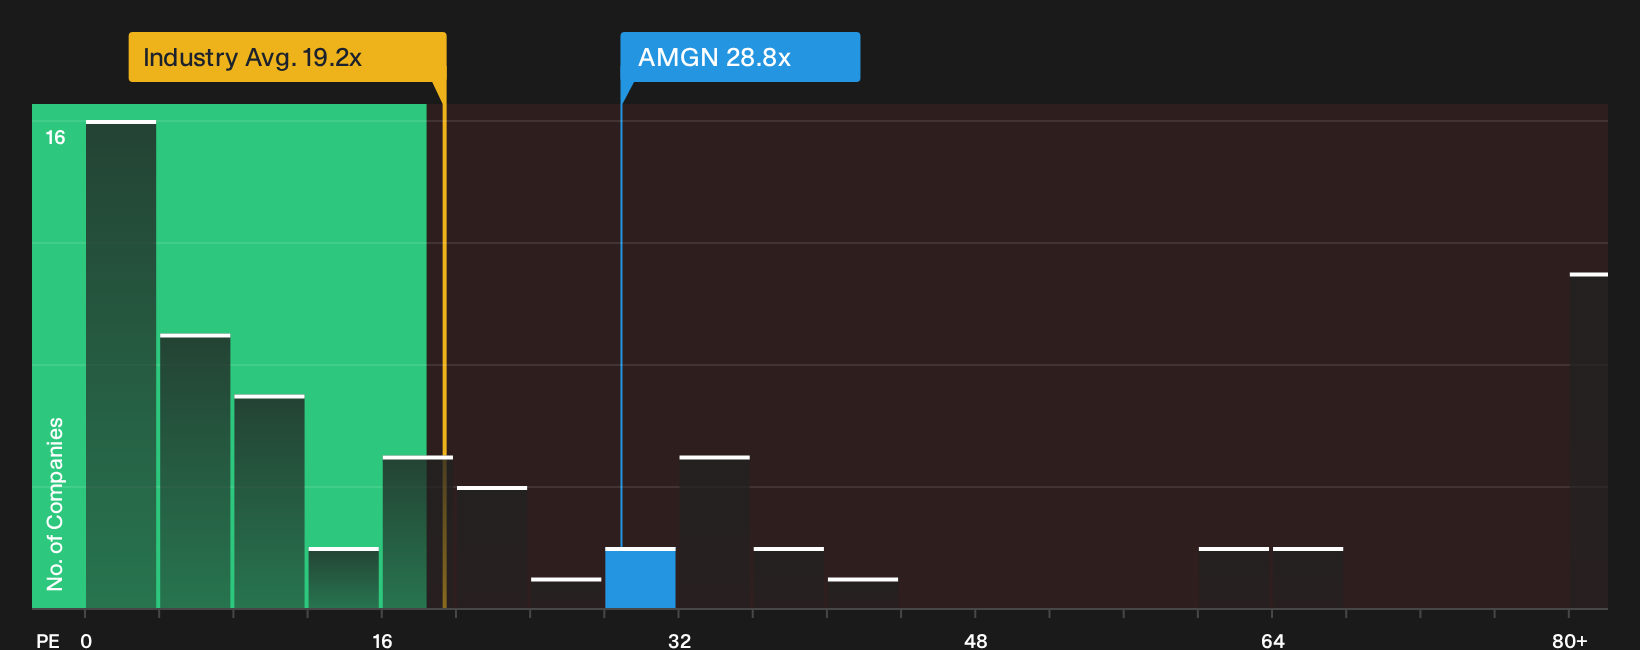
The user narrative calls Amgen 29% overvalued at a fair value of $359.98, yet the market’s own yardsticks tell a different story. On a P/E of 28.8x, the stock trades well below a peer average of 52.5x and below an estimated fair ratio of 34.6x.
That gap suggests investors are already discounting some of the obesity hype and legacy erosion risk, even after the strong share price run. For anyone weighing these cross-currents, the key question is whether the market moves closer to today’s P/E or toward that higher fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of excitement and caution around Amgen feels familiar, treat it as a prompt to dig into the details yourself and move early while sentiment is still forming. To weigh both the concerns and the upside case in one place, start with the 4 key rewards and 1 important warning sign.
Looking for more Amgen sized opportunities?
You have seen what a single stock story can look like when the pieces line up. Do not stop here; widen your opportunity set with a few focused screens.
- Target resilient ideas that aim to protect your capital and steady your portfolio through a 29 resilient stocks with low risk scores.
- Hunt for potential upside where quality and pricing power meet using a focused list of 19 high quality undiscovered gems.
- Build a foundation of sturdier holdings by zeroing in on companies with strong finances through a hand picked list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com