


DXP Enterprises buyback sets the stage
DXP Enterprises (DXPE) has introduced a new catalyst for shareholders after its board approved a share repurchase plan for up to 1,000,000 shares, with a total authorization of US$150 million over 24 months.
DXP Enterprises has had a choppy few months, with the share price down 10.06% over the past 30 days but still up 6.94% on a 90 day share price return. This buyback now lands on top of a strong 61.96% year to date share price return and a very large 3 year total shareholder return of 411.46%. This suggests that momentum has built over time even if near term sentiment has cooled slightly at the latest price of US$174.46.
See how DXP Enterprises compares with other industrial players being closely watched for potential buybacks and re-ratings in our curated list of 33 high quality undervalued stocks.
After a sharp run over three years and a fresh US$150 million buyback in play, DXP Enterprises now forces a choice. Do you lean into the current price, or wait for a cheaper entry that may not come?
Most Popular Narrative: 13% Undervalued
Against the last close of $174.46, the most followed narrative for DXP Enterprises points to a fair value of $200, which implies a meaningful gap that the buyback sits on top of.
The main thing that has to go right is that DXP Water and other higher-value engineered solutions continue to grow as a larger share of sales and margins while the company manages its leveraged balance sheet and integrates recent acquisitions effectively.
See why 9 investors see DXP Enterprises as 13% undervalued.
Result: Fair Value of $200 (UNDERVALUED)
Still, the DXP Enterprises story can change quickly if earnings disappoint again or if its US$842.5 million debt load becomes harder to refinance on current cash flows.
Find out about the key risks to this DXP Enterprises narrative.
Another View: DXP Enterprises On Earnings Multiples
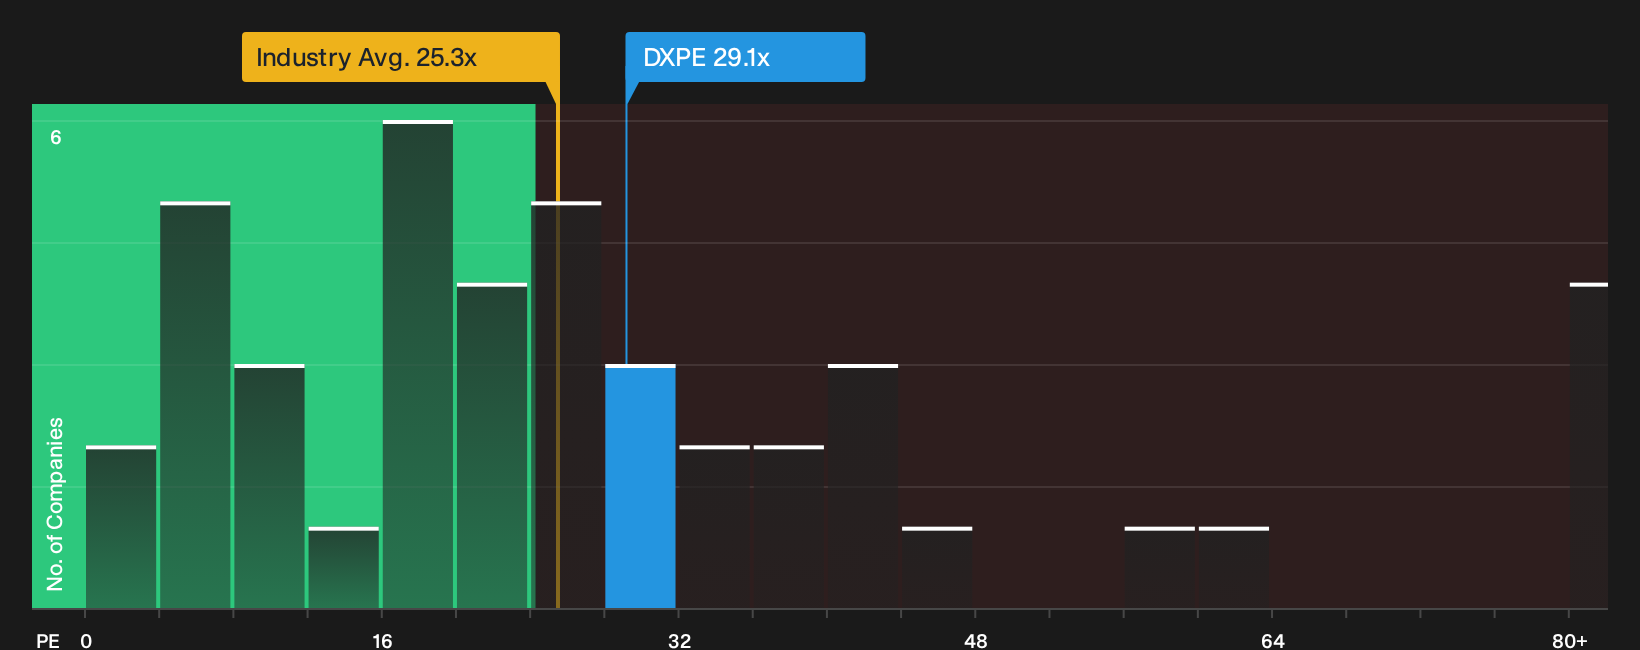
DXP Enterprises screens differently when the focus shifts from fair value estimates to plain P/E math. The stock trades at 29.1x earnings, which is higher than both its own fair ratio of 26.2x and the US Trade Distributors average of 25.3x. That richer tag can mean investors are paying up for quality, or simply paying too much. Which side of that line do you think this sits on?
For a closer look at how this earnings multiple stacks up against peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of buyback enthusiasm and valuation questions leaves you on the fence, move fast and stress test the numbers yourself. The easiest way to weigh both sides is to review its 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond DXP Enterprises?
If DXP Enterprises has your attention, do not stop here. Broaden your watchlist and pressure test your thesis against other opportunities uncovered by the Simply Wall St screener.
- Target financial resilience by reviewing companies with robust balance sheets in the list of solid balance sheet and fundamentals (24 results).
- Hunt for strong businesses that the market may be mispricing through the 19 high quality undiscovered gems.
- Prioritize stability and capital protection by zeroing in on the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com