


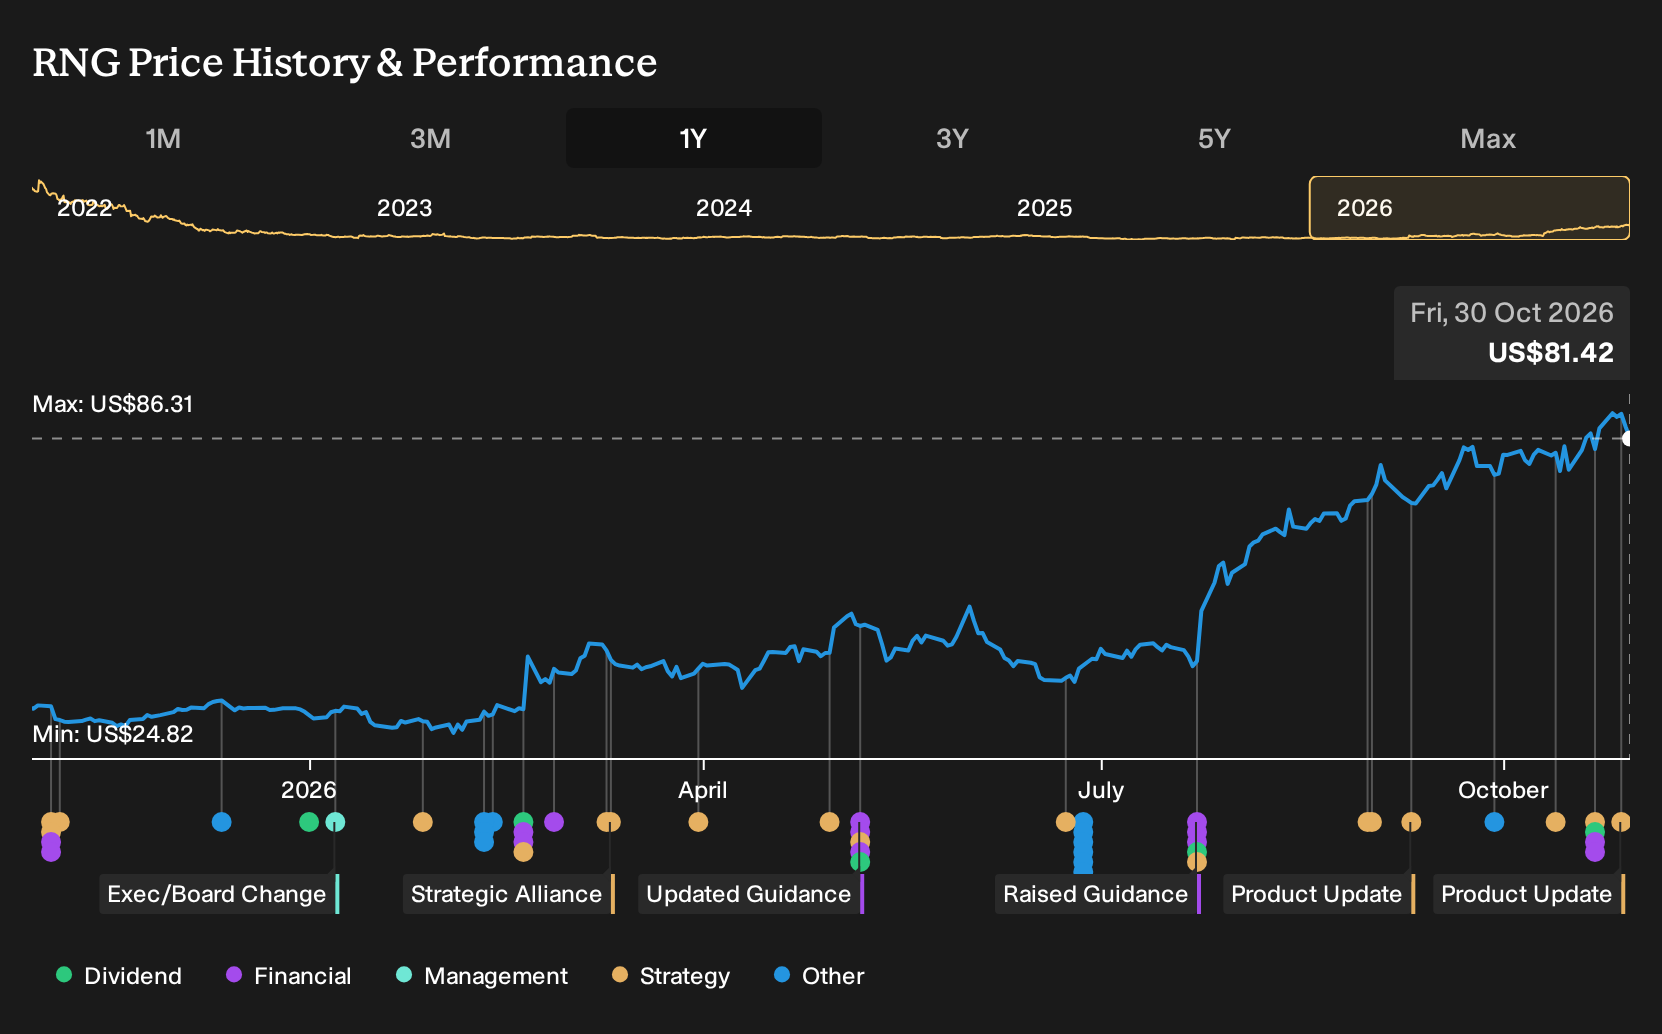
- RingCentral reported third quarter 2026 revenue of US$676.04 million and net income of US$569.7 million, alongside updated full year guidance and a US$0.125 quarterly dividend approved for November 2026.
- The launch of new RingCX AI features that manage AI and human agents as a single workforce, plus AI Onboarding and Teams integration, highlights RingCentral’s focus on efficiency and large enterprise workflows.
- Next, the focus will be on how RingCentral’s investment narrative is shaped by these earnings and expanded RingCX AI capabilities.
Scan how RingCentral’s AI contact center move compares with other potential breakouts in enterprise tech by reviewing our curated list of 54 AI infrastructure stocks.
RingCentral Investment Narrative Recap
To own RingCentral, an investor needs to believe that AI centric contact center tools can offset pressure from bundled suites like Microsoft Teams and Zoom One, and that AI spend eventually supports stable profitability rather than just higher costs. The latest RingCX features keep that thesis focused on execution, not reinvention of the story.
In the near term, the key swing factor is whether RingCX and AIR products see real usage inside large enterprises, because management is investing heavily in AI. The biggest risk remains that competition, slower expected earnings over the next three years, and a high debt load cap how much benefit these new tools actually deliver.
The fresh RingCX AI capabilities look most relevant right now. Supervisors can manage AI and human agents from one dashboard, monitor quality scores on both, and keep full journey analytics across handoffs. That keeps RingCentral squarely in the conversation for contact centers that want automation but still need tight oversight and compliance.
Operationally, this update also ties directly into key catalysts. It leans on the firm’s integrations with Microsoft Teams, supports customers moving to more automated communication flows, and connects to the broader AI Receptionist and AIR Pro stack. The primary execution watchpoint is adoption. If usage lags, heavy AI investment and rising competition could weigh on the story.
RingCentral's narrative projects US$3.1b revenue and US$240.2 million earnings by 2029. This aligns with analyst assumptions of 5.5% yearly revenue growth and an earnings decline of US$422.2 million from US$662.4 million today.
Discover why RingCentral's fair value points to a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate lens focuses on RingCentral’s AI contact center push as a potential earnings accelerator. The most optimistic analysts were already penciling in roughly US$3.1b of revenue and US$586.1 million of earnings by 2029 before this news. You can treat those AI heavy forecasts as a stretch case and explore how opinions differ widely.
Explore 3 other RingCentral fair value estimates, including one that suggests up to 171% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your RingCentral research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for RingCentral. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RingCentral's overall financial health at a glance.
Looking for more RingCentral sized investment ideas?
Once you have a handle on RingCentral, it can help to benchmark it against other opportunities that fit different portfolio roles, from growth at a reasonable price to steadier balance sheet strength.
- If you want potential mispricing with quality in mind, scan a curated set of 33 high quality undervalued stocks that pair solid fundamentals with discounted valuations.
- For investors who care most about resilient finances, compare RingCentral to a list of solid balance sheet and fundamentals (24 results) that can help anchor a portfolio through different market conditions.
- Those hunting for opportunities the crowd may have overlooked can review a focused group of 19 high quality undiscovered gems that combine under-the-radar profiles with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com