


J. M. Smucker (SJM) has affirmed a regular dividend, with the board approving a $1.12 per share payout scheduled for December 1, 2026, to shareholders of record on November 13.
J. M. Smucker’s latest dividend decision lands after a strong share price run, with the stock at $129.90 and a 30-day share price return of 10.85% feeding into a 34.43% year to date gain and a 30.50% 1-year total shareholder return. This suggests momentum has been building even as softer FY27 sales guidance and a slower Sweet Baked Snacks recovery keep risk perceptions in focus.
Compare J. M. Smucker’s income profile with a hand-picked 5 dividend fortresses that may appeal if you are focused on both cash payouts and price momentum.
After a 34.4% year to date surge and a fresh dividend on the way, J. M. Smucker now asks a tougher question of investors. Does the current price still compensate for the guidance and Sweet Baked Snacks risks, once the valuation is unpacked?
Most Popular Narrative: 9% Undervalued
On the most followed view of J. M. Smucker, a fair value of about $142 sits above the recent $129.90 close. This puts the current rally against a still supportive valuation story built around branded growth and cash generation.
The main factor that has to go right is that J. M. Smucker converts momentum in core growth brands and ongoing cost discipline into sustained free cash flow around the current US$1.1 billion level while it continues to deleverage and manage the Hostess turnaround.
Sustained free cash flow around the US$1.1b to US$1.2b level, combined with leverage already at about 2.9x net debt to EBITDA, gives J. M. Smucker additional flexibility to keep reducing interest expense, consider future buybacks or reinvest behind high return brands, which can support future EPS growth.
See why 16 investors see J. M. Smucker as 9% undervalued.
Result: Fair Value of $142 (UNDERVALUED)
Still, softer FY27 net sales guidance and the slow Sweet Baked Snacks recovery, including recent segment profit pressure, could both challenge the current optimism around J. M. Smucker.
Find out about the key risks to this J. M. Smucker narrative.
Another View: J. M. Smucker Through The P/E Lens
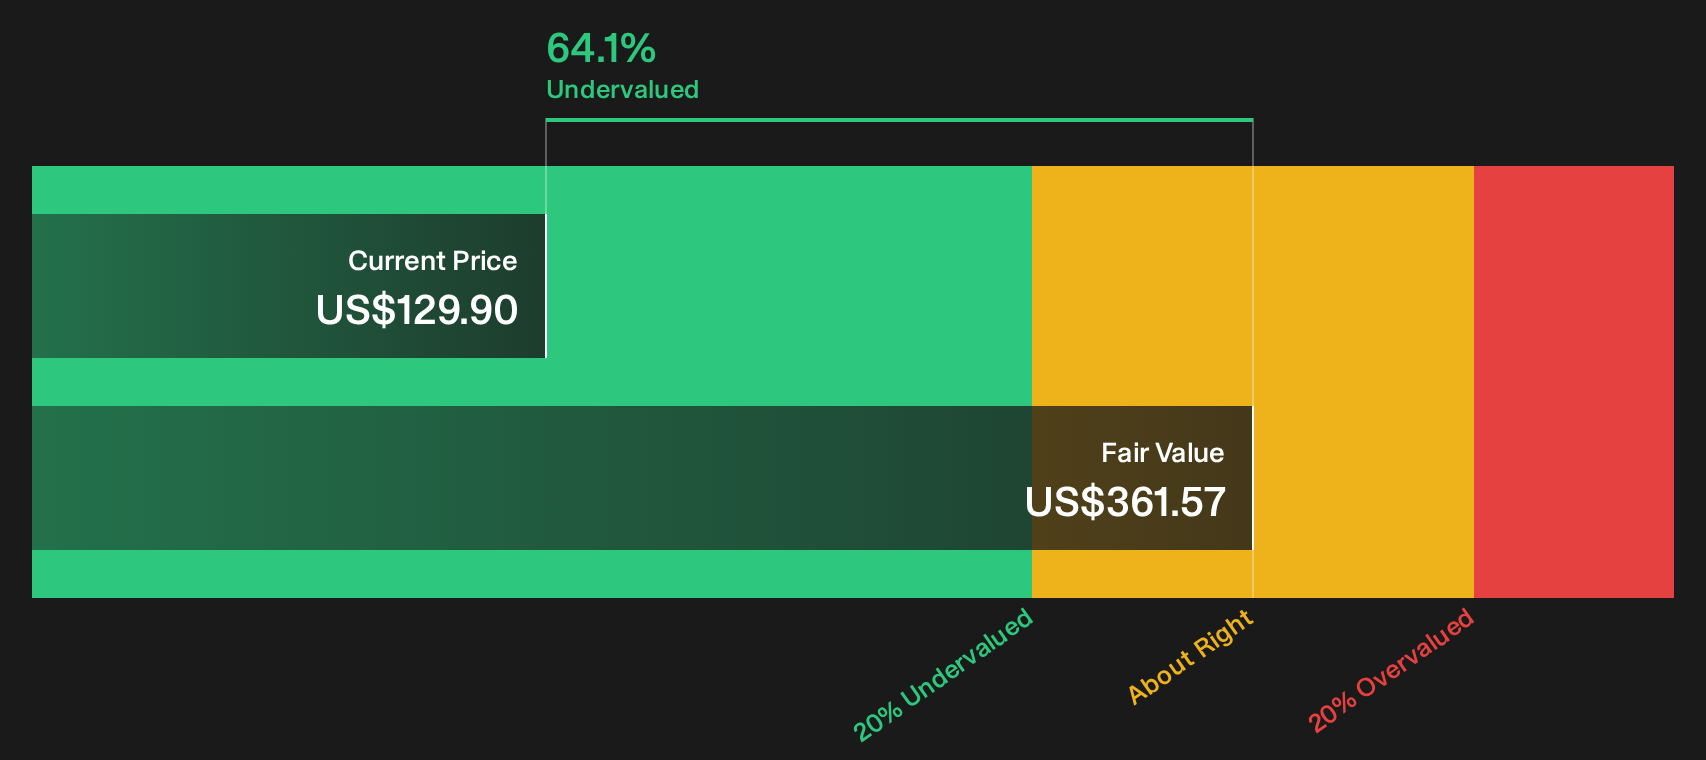
The SWS DCF model points to J. M. Smucker trading below an estimated future cash flow value of about $361.57, which is very different to the $142 fair value narrative. That gap frames a simple question for investors: Is the market too cautious on cash generation, or is the model too generous?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around J. M. Smucker’s valuation and dividend story can feel confusing, so move fast, look through the underlying data and make the call yourself. To sharpen that view, weigh both sides of the ledger with 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond J. M. Smucker?
If J. M. Smucker has sharpened your focus on quality and income, broaden your watchlist now and scan other opportunities before the next move passes you by.
- Target dependable cash flow by reviewing 5 dividend fortresses that combine income potential with robust payout profiles.
- Hunt for value opportunities with the 36 high quality undervalued stocks that filter for quality companies priced below their fundamentals.
- Strengthen your downside protection by checking the 29 resilient stocks with low risk scores that screen for resilience and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com