


Dow Inc. has delivered a powerful share price recovery, and that kind of swing naturally raises a blunt question for investors who care about fundamentals. Is the current US$34.70 price tag properly grounded in what the company is generating in sales today and what it might reasonably earn from them over time?
- Over the past 12 months the stock has returned 56.7%, which puts real pressure on the question of whether the recent share price climb is fully backed by Dow's revenue base.
- Management has paired stronger profitability with debt reduction and tighter working capital, which can shape how much of each dollar of sales eventually turns into cash that supports the equity value.
- There is a second opinion on Dow worth weighing. See what analysts think Dow's shares could be worth.
The issue now is whether Dow's current valuation is adequately supported by its sales when set against the Fair Ratio benchmark.
If you are evaluating whether Dow's rebound remains consistent with its sales, it can help to compare it with other companies filtered through 36 high quality undervalued stocks.
Does Dow Look Undervalued on Sales?
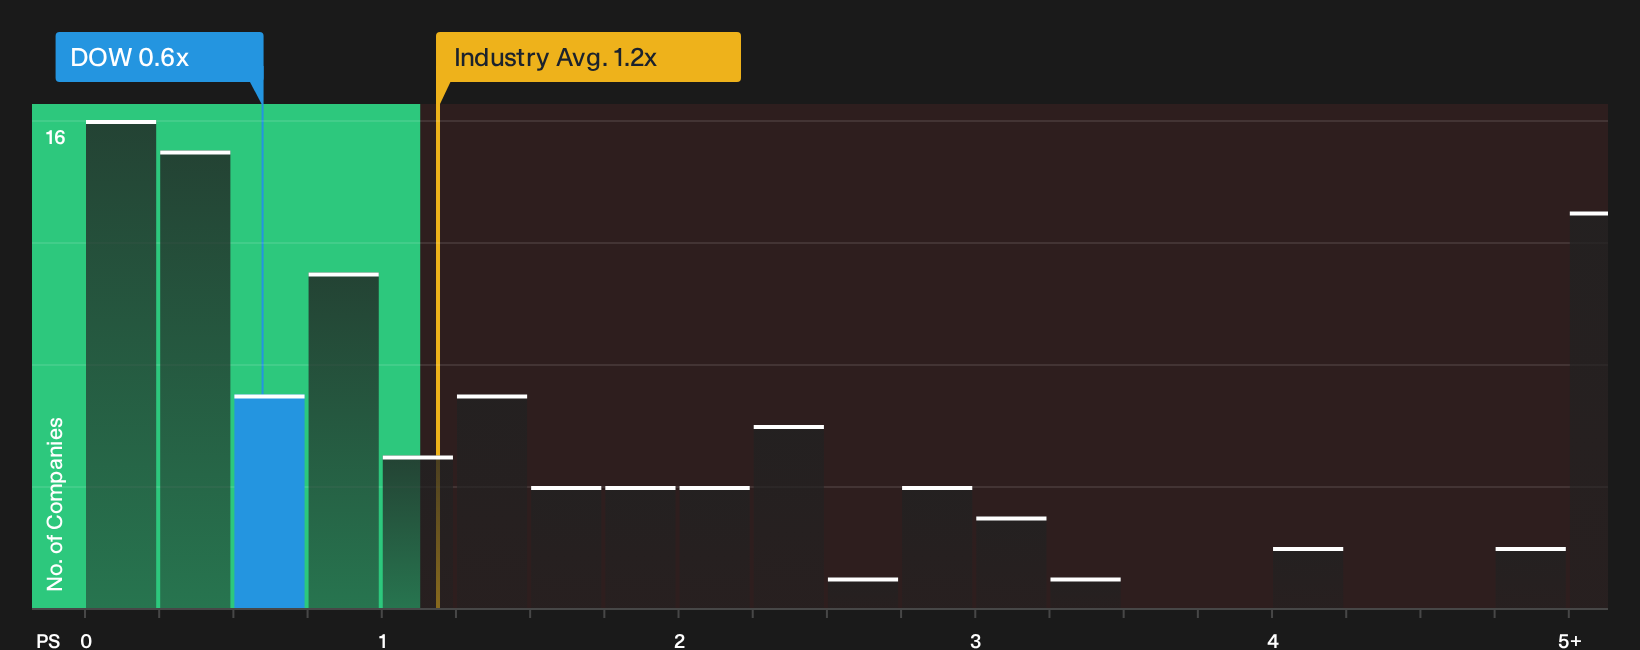
For a business like Dow where earnings can swing around, the P/S ratio gives a clearer view of what investors are paying for each dollar of revenue. At a P/S of 0.6x, the stock trades well below the Chemicals industry average of 1.2x and under the peer group mark of about 1.3x.
The Fair Ratio framework, which blends Dow’s margins, growth profile, size and risk into a tailored P/S reference point, also characterizes the current multiple as undervalued rather than stretched. Because recent Q3 2026 results beat expectations and highlighted tighter cash management and lower debt, this gap indicates that the stronger operating performance has not yet fully narrowed the discount on this sales-based lens. Explore the numbers behind Dow's P/S valuation.
The Dow Narrative: What Would Justify Today's Price?
Narratives pick up where Dow's valuation puzzle leaves off and explain which combinations of revenue growth, profit margins and earnings paths would need to occur for the stock to be priced meaningfully higher or lower than it is today on Simply Wall St's Community page. Each scenario links its number to a specific view on how Dow's growth, profitability and risk profile might evolve, which gives you something concrete to revisit as fresh results and filings are released.
Community views on Dow are split between investors who see more upside in the self help program and those who think oversupply and spending already cap the share price.
Bull case: roughly fairly valued
"Dow has increased its 2026 outlook for self help benefits to more than US$1.3b and continues to target over US$3b of largely structural improvements by 2029..."
Discover why this Narrative puts Dow at roughly fairly valued.
Bear case: 16% overvalued
"Bearish analysts expect Dow's exposure to traditional petrochemical chains and ongoing macro volatility, including weaker polyethylene pricing, to keep pressure on earnings and limit the benefit from self-help programs..."
Explore why this Narrative puts Dow at 16% overvalued.
One more angle on Dow that could change how you see the stock
Valuation only tells part of the Dow story, and internal checks have picked up potential trouble spots that deserve a closer look before you lean on any price multiples too heavily. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com