


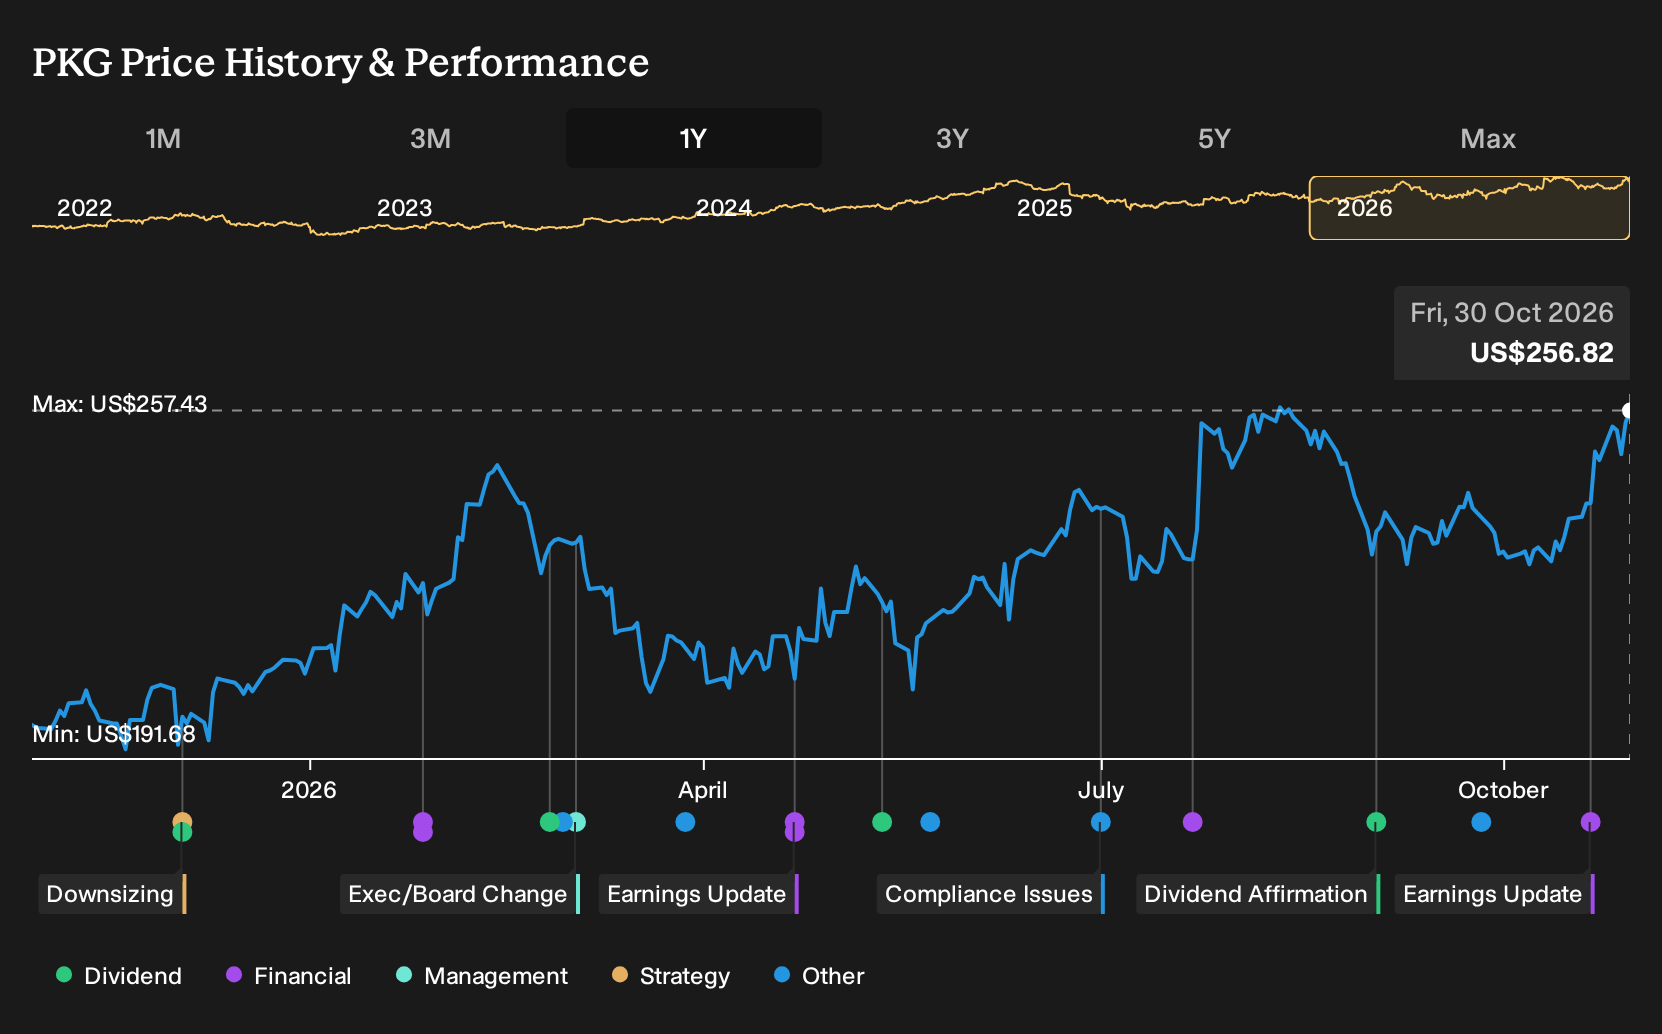
Packaging Corporation of America spent this past year announcing an unprecedented US$140 per ton containerboard price hike and pushing through the Greif acquisition while investors argued over whether these moves signaled new strength or late-cycle risk. Investors who held Packaging Corporation of America over the past year are up 34.6%, including dividends. If you were weighing a purchase back on 2025-10-30, what exactly did you need to believe about pricing power and corrugated demand before any of that news hit the tape?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Packaging Corporation of America has already moved. See which of 36 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing Up On Packaging Corporation of America
The shares cost US$196 at the start of the period, so any decision on Packaging Corporation of America hinged on which story about its future you found more convincing.
The bullish narrative put Fair Value at US$216, which is 10% above the start price, and relied on the idea that the Glendale box plant and pricing adjustments could support 4.9% revenue growth and a 12.0% profit margin over three years.
The bearish view pointed to a Fair Value of US$152 and treated digital disruption as a real threat, with concerns that heavier regulation and reusable models could steadily erode traditional corrugated demand.
What The Results Changed For Packaging Corporation of America
Packaging Corporation of America reported Q3 2026 revenue of US$2.60b and net income of US$260.8m, compared with Q3 2025 revenue of US$2.31b and net income of US$228.4m. Net margin edged from 9.9% to 10.0%, which provided some support for the bullish pricing power narrative, although the improvement was marginal enough that it did not fully settle the cautious view on long term corrugated demand.
The key moving part here was the assumption about stronger margins from price and mix. For a different stock, that kind of claim can be treated as a testable bet, with revenue, profit and margin tracked side by side each quarter rather than focusing only on the share price.
What Packaging Corporation of America’s Run Leaves You Paying For Today
Packaging Corporation of America now trades at US$257 after a 34.6% gain over the past year. The selected Narrative’s Fair Value sits below the current price, which reflects a more cautious stance on how much of the recent progress is already reflected in the valuation.
That Narrative leans on real pricing power yet keeps circling back to cost pressure and heavy capex. At today’s price, you would need to judge whether mill upgrades and Greif integration efficiencies can outrun ongoing freight and recycled fiber inflation.
"Although Packaging Corporation of America has been able to lift net sales, the Q2 2026 margin compression, with operating margin at 11.7% versus 15.4% a year earlier, signals that higher freight and recycled fiber costs could keep outpacing pricing actions and volume. This would keep pressure on net margins and earnings."
The price and this Narrative do not agree. → Uncover what this Narrative says Packaging Corporation of America is actually worth
Before The Next Story Makes Headlines
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 35% below our estimate - convert subsea project opportunities into higher margin, long duration service contracts.
- Company 2 - 36% below our estimate - target rising AI data centre budgets with integrated GPU hardware and software solutions.
- Company 3 - 48% below our estimate - turn large backlogs of complex projects into modular construction and recurring services revenue.
That is three of the list. See all 24 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com