


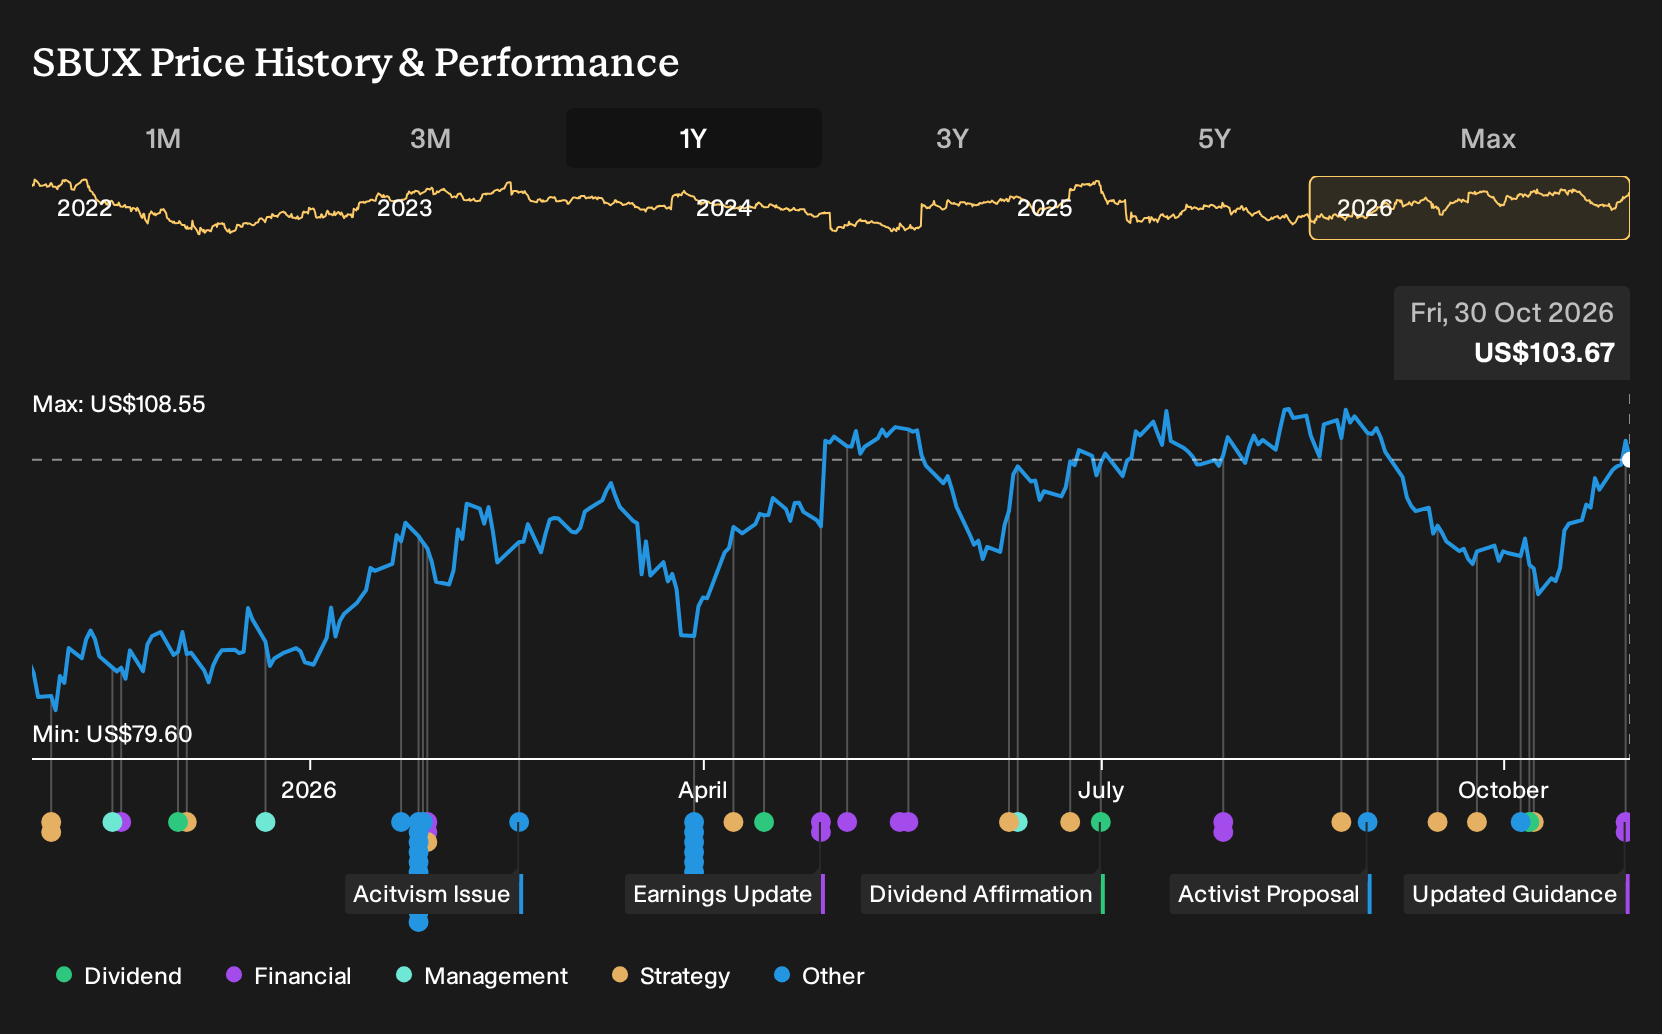
- Starbucks reported fourth quarter 2026 revenue of US$9,141.2 million and net income of US$677.2 million, alongside full year earnings per share from continuing operations of US$2.21.
- The company paired this earnings update with guidance for a slight revenue decline in fiscal 2027 as it shifts China to a licensed joint venture model and outlined a plan to add nearly 40,000 international stores.
- We will now explore how Starbucks' investment narrative could shift as investors weigh its joint venture shift in China against the planned global store expansion.
See how Starbucks’ earnings reset and its China shift compare with other consumer stocks making big moves by running them through our 36 high quality undervalued stocks.
Starbucks Investment Narrative Recap
To own Starbucks, you need to believe its premium coffee model, store upgrades and rewards ecosystem can support healthy earnings even as the footprint and format evolve. The latest quarter showed full year revenue of US$37.9b and net income of US$2.5b, which keeps attention on whether the Back to Starbucks cost work can keep margins moving in the right direction.
The near term swing factor is how cleanly Starbucks executes the China shift to a licensed joint venture while still growing profit per share. Guidance for about a 1% revenue decline in fiscal 2027 ties directly into that. The biggest risk remains cost pressure from labor, legal and remodel spending that slows margin progress.
The most relevant update here is Starbucks’ 2027 guidance. Management expects consolidated net revenue to decline about 1% year over year, largely because China moves to a licensed joint venture model, and still guides to diluted EPS of US$3.07 to US$3.17. That combination puts the spotlight on mix and efficiency, not just headline sales.
For you as a shareholder, the key question is whether the capital light China structure, the planned international buildout and North American remodels together can support that earnings range without stretching the balance sheet or labor model. Execution against the US$2b cost savings plan and handling of unionisation and regulatory issues sit right next to the guidance as live catalysts and risks.
Starbucks' narrative projects US$42.3b revenue and US$4.8b earnings by 2029. This assumes 3.3% yearly revenue growth and a US$2.8b earnings increase from US$2.0b today.
Uncover why Starbucks' fair value indicates a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle focuses on Starbucks’ remodel costs rather than the China joint venture. The most pessimistic analysts were already assuming revenue of about US$42.5b and earnings near US$4.9b by 2029, yet still saw limited upside. The key takeaway is that views can differ widely, so it is worth comparing several forecasts.
Explore 6 other Starbucks fair value estimates, including one that suggests as much as 22% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Starbucks research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Starbucks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Starbucks' overall financial health at a glance.
Looking For More Investment Ideas Beyond Starbucks?
If you want to put Starbucks in context, it can help to line it up against other businesses with different balance sheet profiles, income streams and risk levels. The Simply Wall St Screener lets you do that quickly by filtering the market down to only the types of stocks that suit your approach.
- If capital preservation sits high on your list, start by scanning a 29 resilient stocks with low risk scores that score well on resilience and lower overall risk.
- For investors who care most about financial strength, focus on companies with robust funding and cleaner accounts through our list of solid balance sheet and fundamentals (24 results).
- If you are hunting for lesser known opportunities with strong fundamentals, cast a wider net across a 19 high quality undiscovered gems that might not be on every investor's radar yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com