


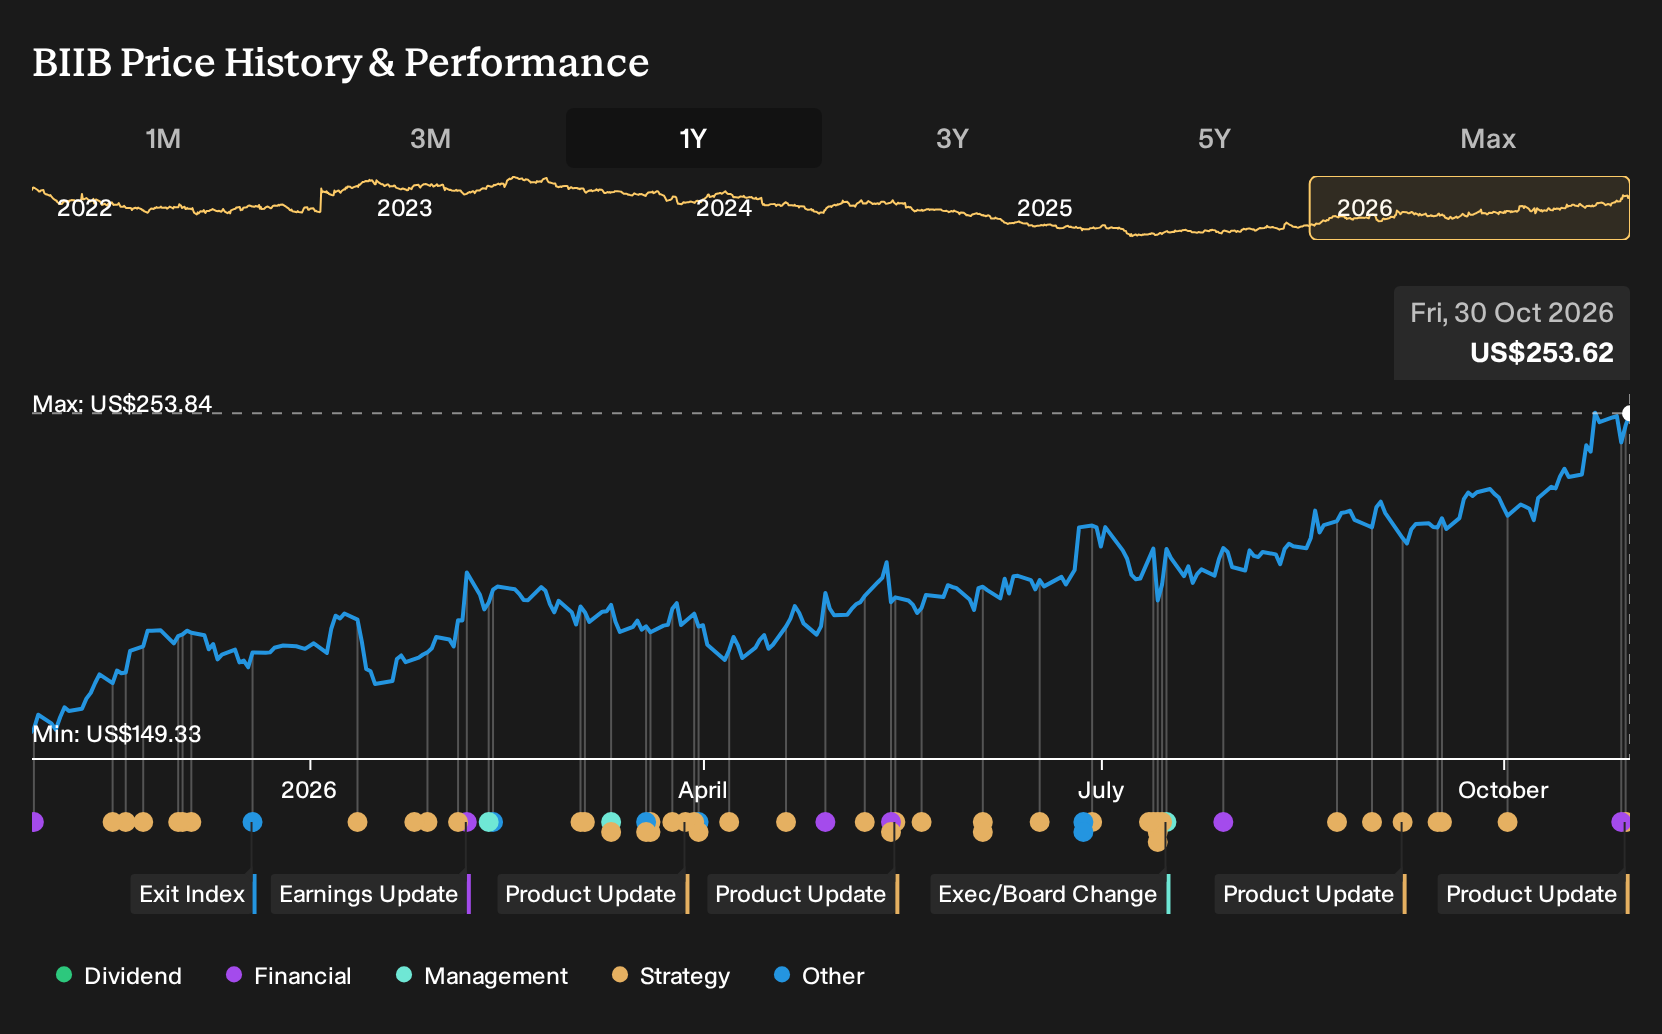
If you had been weighing Biogen in late October 2025, you were choosing between a bullish case built on new Alzheimer’s and rare-disease therapies and a bearish view focused on pricing pressure and generic erosion. For Biogen shareholders, the return over the past year was 67.5%, including dividends. If that decision were on your desk again today, how much weight would you give to pipeline optimism versus concerns about policy and competition?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Biogen is not the only name tied to this theme. Zero in on 33 healthcare AI stocks and compare how each one is priced.
The Two Stories Biogen Investors Were Arguing About
Biogen shares cost US$150 at the start, and investors had to decide whether that price better matched optimism about new therapies or worries about policy pushback and generic rivals.
The bullish narrative pointed to a fair value of US$170, which sat 13% above the start price. It leaned on assumptions that revenue would decline 2.1% a year while profit margin rose to 22.4%, supported by therapies such as LEQEMBI, SKYCLARYS and ZURZUVAE.
The bearish view put fair value at US$115, or 23% below the start price. That case expected revenue to fall 5.0% annually and highlighted pressure from drug pricing scrutiny, reimbursement hurdles and competition from generics and biosimilars.
What The Results Changed For The Biogen Debate
Biogen’s later Q3 2026 figures gave the bullish camp fresh product evidence through launches like LEQEMBI IQLIK and the completed Apellis deal, yet the numbers told a harsher story. Revenue reached US$2,804.1m compared with US$2,534.7m a year earlier. The business swung from a US$466.5m profit to a loss of US$20.6m, and net margin moved from 18.4% to -0.7%. The period cut both ways.
The key lesson is to track whether a growth story is flowing through to profitability. When you see new drugs and acquisitions, test the claim against reported net income and margin, not just top line. Also check whether added scale is funding itself or relying on higher costs and extra debt.
What Biogen’s 67% Run Already Assumes
Biogen shares now trade at US$254 after a 67.5% gain over the past year. The selected Narrative’s Fair Value sits below that price and frames the gap around how much confidence you place in newer Alzheimer’s, immunology and nephrology products offsetting pressure on older therapies.
The question today is what must keep going right for that level to hold. A buyer at US$254 has to judge whether Biogen’s broader growth portfolio and expanding pipeline can collectively carry future earnings if payer scrutiny and legacy revenue headwinds persist.
"The numbers imply Biogen’s share price already bakes in successful execution on its growth portfolio, pipeline readouts, and recent acquisitions, leaving limited room for disappointment if assets such as Alzheimer’s and lupus programs do not meet expectations."
One Narrative disagrees with today's price. → See where this Narrative says Biogen should trade
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 30% below our estimate - builds high capacity AI superclusters that major model providers rely on for training.
- Company 2 - 38% below our estimate - shifts freight mix toward heavy haul while deploying AI tools to reduce fraud risk.
- Company 3 - 48% below our estimate - converts a large backlog of data center and modular projects into ongoing service revenue.
Those are three of them. See every one of the 36 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com