


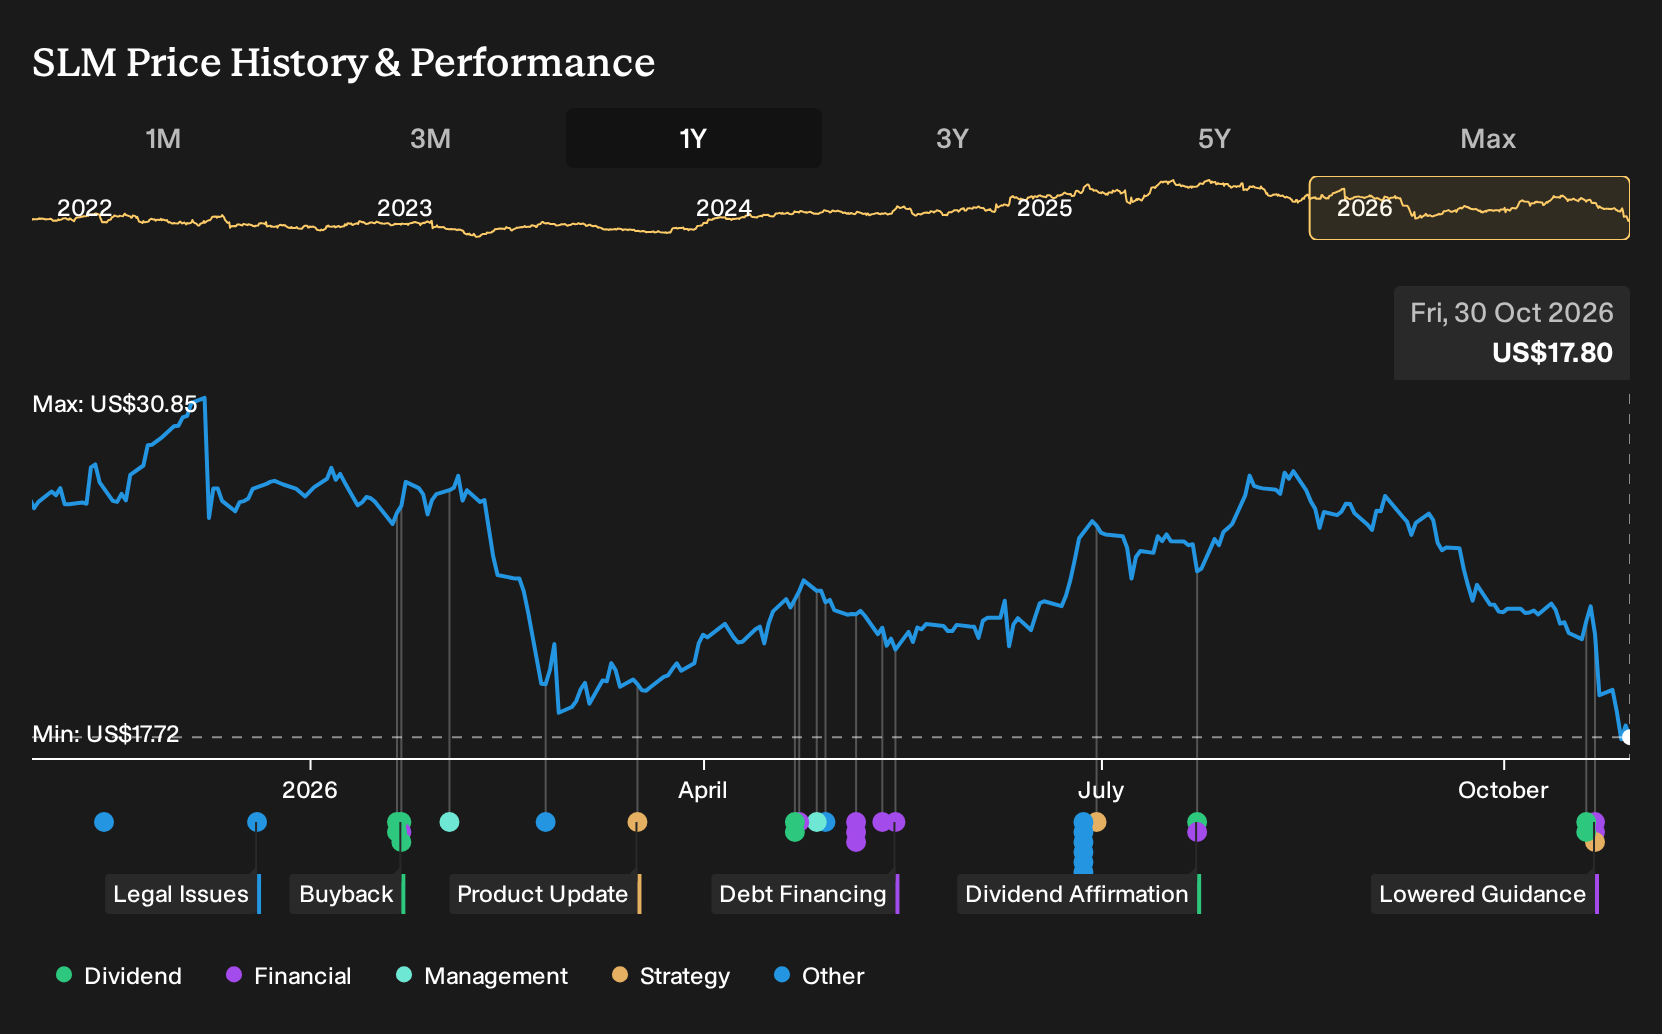
- SLM Corporation reported a third quarter 2026 net loss of US$32.26 million and lowered full year diluted EPS guidance to US$1.95 to US$2.05 from US$3.10 to US$3.20, alongside higher net charge off expectations of US$400 million to US$420 million.
- The combination of weaker earnings, raised credit loss guidance and ongoing share repurchases of 11,173,192 shares for US$389 million creates a tighter margin for SLM to fund growth, absorb loan losses and maintain its capital light business model.
- We will now look at how SLM's reduced earnings guidance reshapes the existing investment narrative built around capital light growth.
SLM Investment Narrative Recap
To own SLM, you effectively need to believe its private education lending franchise can turn reform driven volume into durable earnings while keeping credit issues under control. The cut to 2026 diluted EPS guidance to US$1.95 to US$2.05 signals a tougher operating stretch. The most important short term catalyst now is whether credit trends stabilize as tighter underwriting seasons through the book.
The biggest risk has become credit quality and related provisioning. Higher net charge off guidance of US$400 million to US$420 million points to more stress flowing through the income statement. That combination of weaker profits and heavier losses can limit flexibility for SLM to invest, manage funding costs and support shareholder returns.
The updated net charge off outlook is the announcement that most cleanly ties into this earnings reset. Management now expects US$400 million to US$420 million of net charge offs for 2026, compared with the prior US$365 million to US$385 million range. For you, that shifts attention from growth opportunity to loss content and recoveries.
Higher realized and expected charge offs feed straight into the main risk already on the radar, which is persistent or rising delinquencies compressing net interest margins. If problem loans stay elevated, SLM may need to lean harder on pricing, expense control and its capital light partnerships to keep the private loan story on track and protect the key catalyst of reform driven volume.
SLM's narrative projects US$1.5b revenue and US$626.4 million earnings by 2029. This assumes revenue remains broadly flat over the period and implies an earnings increase of about US$73.6 million from US$552.8 million today.
Uncover why SLM's fair value indicates a 47% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate story around SLM leans hard into sale economics as the key catalyst. Before this guidance cut, the most cautious analysts still penciled in flat revenue near US$1.5b and earnings of about US$613.1 million by 2029. That is a much more pessimistic arc. These older forecasts have not absorbed the fresh credit and EPS reset, so expect opinions to move and consider exploring several viewpoints before deciding how you feel about the risk and reward trade off here.
Explore 2 other SLM fair value estimates, including one that suggests it could be worth just $24.78!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your SLM research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SLM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SLM's overall financial health at a glance.
Looking For More Investment Ideas Beyond SLM?
If SLM's reset guidance has you rethinking concentration in a single lender, it can help to line it up against other opportunities that share some of the same qualities you care about, whether that is value, balance sheet strength or a lower risk profile.
- For readers who want to focus on quality at a discount, compare SLM against a curated 36 high quality undervalued stocks that combine appealing pricing with stronger fundamentals.
- If capital resilience is your priority, measure SLM beside a list of solid balance sheet and fundamentals (24 results) that can better weather credit swings.
- For a calmer ride, weigh SLM against a 29 resilient stocks with low risk scores that may offer a smoother return path.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com