


IDACORP (IDA) raised its 2026 earnings outlook after reporting third quarter results that showed higher sales, revenue, and net income, supported by stronger demand from large industrial customers, including Micron and Meta.
The raised outlook and strong third quarter results have contributed to firm momentum in IDACORP's shares. They trade at US$145.38 after a 9.48% one-month share price return and a 14.20% year-to-date share price gain, alongside a 60.54% three-year total shareholder return that reflects ongoing investor confidence in the story.
Scan how IDACORP’s earnings reset aligns with other regulated utilities targeting grid upgrades and large industrial demand by reviewing our curated list of 42 power grid technology and infrastructure stocks.
After a sharp rerating on stronger guidance and industrial demand, IDACORP now asks investors to decide whether the current price still offers upside for new buyers or primarily rewards those already invested.
Most Popular Narrative: 4% Undervalued
Against a last close of $145.38, the most followed narrative frames IDACORP’s fair value at about $151.44, leaving a modest gap that hinges on how large industrial load and capital spending convert into long term earnings power.
Massive planned capital investments, with IDACORP expecting to spend between US$1.3b and US$1.5b on CapEx in 2026 and around US$7b from 2026 to 2030 on generation, storage and transmission projects such as B2H and SWIP North, are forecast to drive rate base from about US$5.3b in 2025 to around US$11b by 2030 and increase regulated earnings.
See why 4 investors see IDACORP as 4% undervalued.
According to this narrative, that roughly 4% discount to fair value reflects investor debate around execution risk rather than a deep mispricing. The thesis leans on a 7.24% discount rate and assumes IDACORP can keep turning a large capital program and concentrated exposure to Micron and Meta into regulated earnings while managing hydropower variability, funding needs and customer affordability.
For readers, the takeaway is that most of the upside case is already quantified and linked to specific projects, regulatory tools and load contracts. The remaining question is how much confidence to place in those inputs and whether the implied long term profile matches personal assumptions on growth, risk and required return.
Result: Fair Value of $151.44 (UNDERVALUED)
Still, the IDACORP story depends heavily on hydropower conditions and on Micron and Meta ramping as planned. Prolonged drought or project delays could quickly challenge that 4% undervalued view.
Find out about the key risks to this IDACORP narrative.
Another View: IDACORP Through The P/E Lens
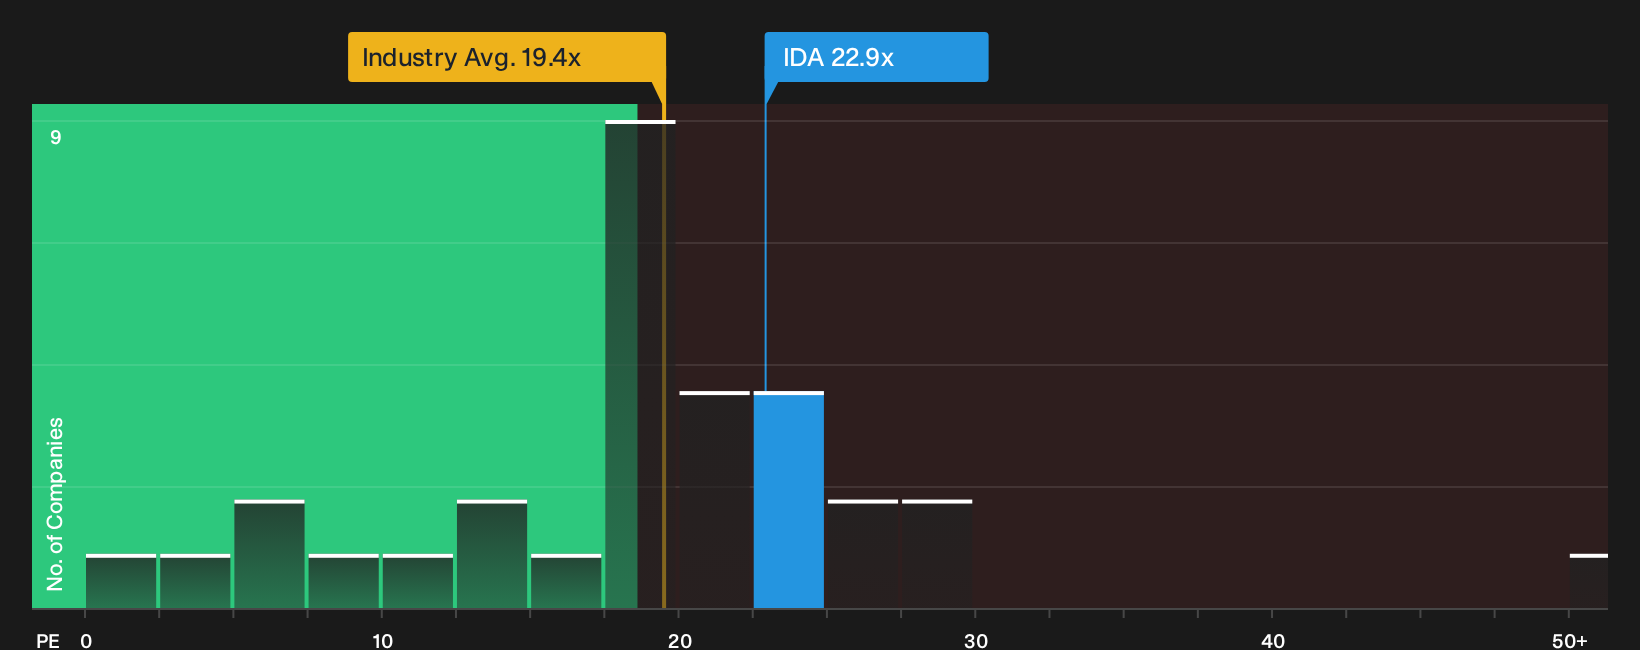
The first narrative leans on cash flow and long range earnings power. A second lens uses IDACORP’s current P/E of 22.9x, which sits above the US Electric Utilities industry at 19.4x, peers at 21.5x, and a fair ratio of 21x. That premium suggests less room for error if growth or regulation disappoints. This raises the question of how comfortable investors might be paying above the sector for a largely regulated profile.
For a closer look at how this pricing gap could close over time, including what the fair ratio implies for upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings on IDACORP so far. If you want to move quickly and base your own view on the numbers, consider the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond IDACORP?
If IDACORP sharpened your focus on regulated utilities, now is a good moment to broaden your watchlist before the next wave of opportunities moves first.
- Spot potential value plays early by scanning a 36 high quality undervalued stocks that line up solid fundamentals with prices that may not fully reflect them yet.
- Anchor your portfolio with resilience and assess a 29 resilient stocks with low risk scores that prioritise sturdier balance sheets and calmer risk profiles.
- Hunt for tomorrow's potential standouts by reviewing a 19 high quality undiscovered gems that have quality metrics but limited market attention so far.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com