


International Petroleum has delivered a powerful long term share price run, and the question now is whether that move is supported by its sales base. With the stock recently closing at C$40.11, investors are asking how much current revenue can carry the valuation from here.
- Over the last 5 years the share price has climbed about 443.5%, which puts a lot of weight on whether the underlying sales justify that kind of rerating.
- The business model is heavily linked to converting commodity production into cash, so any change in realized pricing, volumes or operating costs can quickly alter how much revenue is backing each dollar of market value.
- The analysts covering International Petroleum have run their own numbers. See what analysts think International Petroleum's shares could be worth.
The issue now is whether International Petroleum's current price can be squared with its sales when set against the Fair Ratio benchmark.
If you want more context around a 5 year gain of about 443.5% and a current price near C$40, it can help to compare International Petroleum with other 3 high quality undervalued stocks.
Does International Petroleum Look Pricey on Sales?
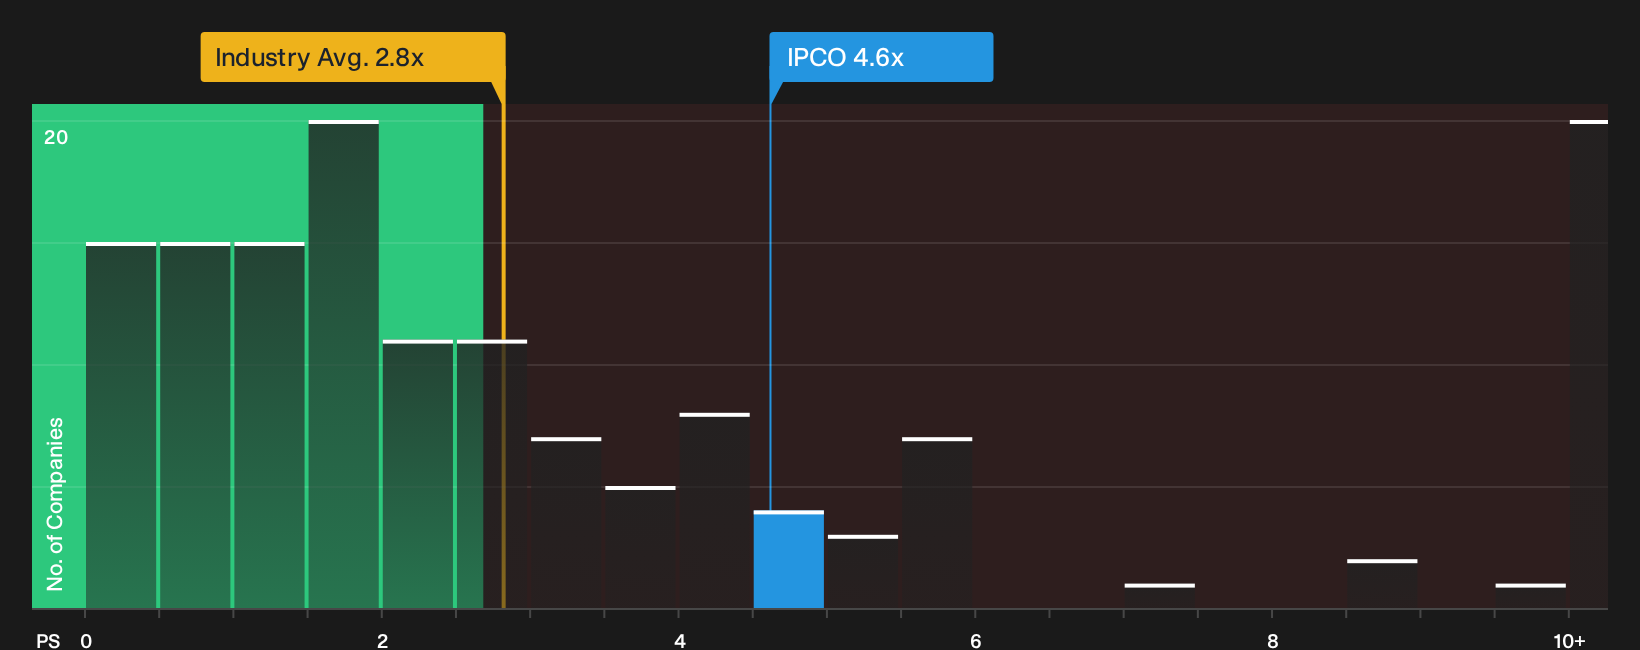
P/S works well for International Petroleum because revenue is tied directly to volumes and pricing, which investors often watch more closely than accounting profit in this sector. On this measure, the stock trades on a P/S of 4.6x, above the Oil and Gas industry average of 2.8x yet below the peer group closer to 6.0x. That combination puts the shares in a kind of middle ground where they are not the highest ticket in the peer set, but no longer priced like a low expectation producer either.
The Fair Ratio model, which weighs International Petroleum's size, risk profile and sector economics, points to a lower P/S than the current 4.6x. That gap signals an overvalued reading on this framework, because investors are paying a richer price per dollar of sales than the tailored benchmark implies. Anyone looking at TSX:IPCO through this lens needs to decide whether its asset base, cash generation potential and commodity exposure justify paying that premium on sales. Explore the numbers behind International Petroleum's P/S valuation.
The International Petroleum Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S puzzle for International Petroleum leaves off by spelling out which paths for growth, margins and earnings would need to play out for the shares to be worth materially more or less than today. Rather than stopping at a single ratio or model output, these short scenarios show the future that figure leans on, so you can watch over time whether International Petroleum's actual progress lines up with those assumptions on the Community page.
Community views on International Petroleum are now split between those who see more upside in the current setup and those who think expectations already look full.
Bull case: 7% undervalued
"The decision to lean on opportunistic share buybacks rather than dividends, supported by a record of repurchasing 77 million shares since 2017..."
Discover why this Narrative puts International Petroleum at 7% undervalued.
Bear case: roughly fairly valued
"Blackrod Phase 1 is nearing completion, with US$820 million already spent out of an US$850 million budget..."
Explore why this Narrative puts International Petroleum at roughly fairly valued.
International Petroleum's price tag is only one piece of the decision
Before you treat International Petroleum's valuation as the whole story, it is worth weighing the specific risk checks that our research has flagged for this business. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com