


Devon Energy’s past 12 months look like a case study in how messy headlines can coexist with strong outcomes. For Devon Energy shareholders, the return over the past year was 62.9%, including dividends. If you had been weighing those AI and midstream efficiency arguments against shale decline risks back on 2025-10-30, would you have had enough on record to hold your nerve through merger noise and activist pressure, or was this mainly luck on timing?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The move put Devon Energy in the middle of this trade. Scan 16 nuclear energy infrastructure stocks for other companies exposed to it.
The Two Devon Energy Stories Investors Had To Weigh
The shares cost US$32.01 at the start of the period, and Devon Energy sat between two very different but credible stories about where the next few years might lead.
The bullish narrative pointed to a fair value of US$45.48, resting on ideas such as 6.3% revenue growth and Devon Energy using AI and real-time data to improve drilling efficiency and capital allocation.
The bearish case argued for fair value of US$26.83, focusing on the risk that heavy reliance on U.S. shale with high decline rates could keep capital needs and costs elevated.
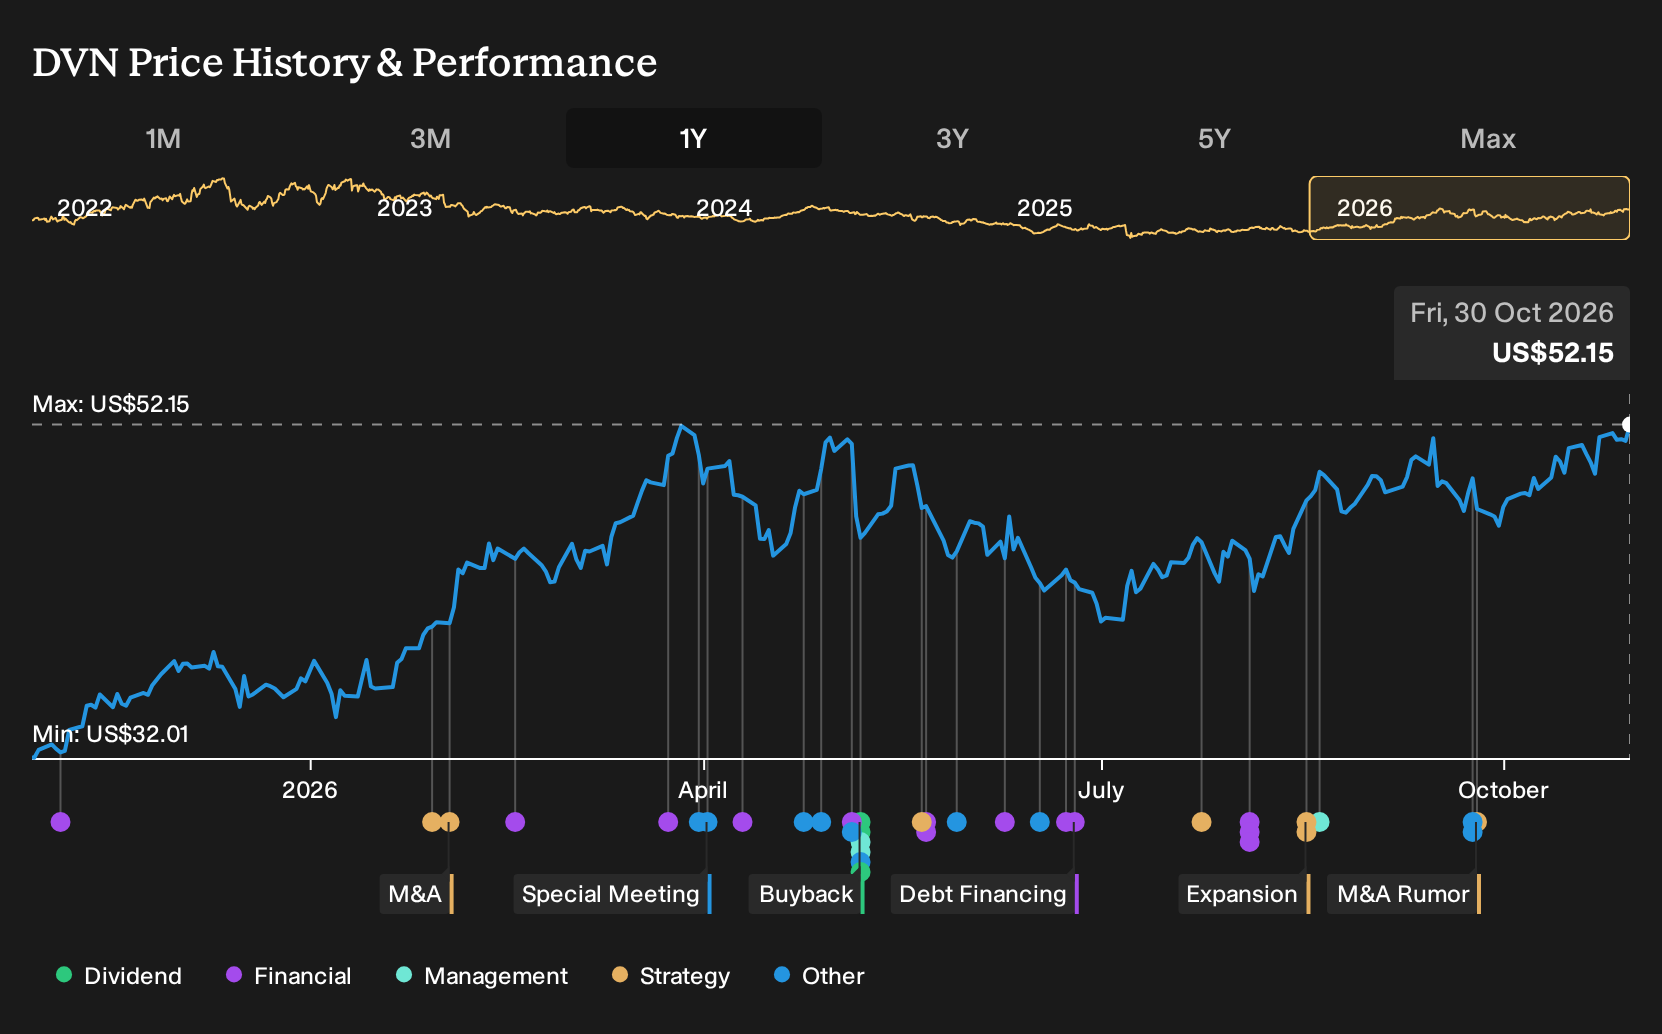
What The Evidence Did To The Devon Energy Debate
The merger with Coterra and the Q2 2026 report, with revenue at US$6.646b and net income excluding extra items at US$1.911b, leaned toward the bullish Devon Energy story that assumed efficiency gains. Net margin moved from 22.2% to 28.8%, which fit the argument that AI, midstream moves and scale could support higher profitability, although activist pressure kept the cautious argument alive.
The lesson is clear. When a thesis hangs on efficiency and capital allocation, do not just watch production headlines. Track net margin and free cash flow against the original assumptions every reporting season.
What Devon Energy’s Price Already Bakes In
Devon Energy now trades at US$52.15, with this Narrative’s Fair Value figure sitting above the current price. The bullish case leans heavily on what disciplined asset sales, higher oil prices and a focused U.S. shale footprint can do for cash generation and balance sheet flexibility.
The argument also leans on AI driven operating gains plus midstream projects that aim to steady realised pricing. A buyer today has to judge whether Devon Energy can genuinely keep pairing tight capital discipline with consistently efficient execution from its U.S. shale portfolio.
"Key Takeaways: Analysts expect Devon Energy to keep using advanced data analytics and targeted midstream projects to support operational efficiency, resilient cash generation, and better access to Gulf Coast export demand. For this bullish undervaluation view to hold, Devon Energy has to keep pairing strict capital discipline and cost controls with consistent execution from its high quality U.S. shale portfolio while it works through portfolio simplification."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking One Step Beyond Devon
Devon focuses on getting hydrocarbons out of the ground efficiently. Your next question might be who manages similar molecules as they move worldwide.
Across the industry, large integrated players handle long distance gas shipments and complex refining. They convert raw output into transport fuels, chemicals and power feedstock.
This integrated model can absorb swings between upstream production, marketing and processing. It also offers more ways to adjust capital when conditions change.
If Devon keeps sharpening its shale execution, attention may shift to these integrated operators. Their choices on projects, divestments and trading could quietly shape Devon's broader landscape.
One Narrative has already put a figure on it. → Uncover the company trading 15% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com