


Oil is back in the spotlight as the Bank of England signals higher rates to tackle inflation fed by steep energy costs. Higher borrowing costs can pressure richly priced shares, which puts extra focus on British companies that generate solid cash and trade below what detailed cash flow models suggest they might be worth. This piece highlights 3 such UK stocks that screen as mispriced on cash flows.
The three stocks covered next are only a sample, since the same cash flow screen surfaced 22 more UK listed companies with similarly interesting stories that are not covered in this article.
If you want to identify and analyze those extra opportunities using the same framework, head straight to the Undervalued Stocks Based On Cash Flows screener.
Shell (LSE:SHEL)
Shell is a large integrated energy group. For this cash flow screen, the focus is on its fuels, lubricants and retail marketing arm, where global service stations and trading activities generate relatively steady cash that anchors the wider business story.
Shell generates revenue across several activities, with about US$146.2b from Marketing and US$142.9b from Chemicals and Products, alongside Integrated Gas at US$53.3b and Upstream at US$47.5b. The group carries a market value of roughly £230.2b.
"With an LNG portfolio exceeding 60 million tons and substantial trading capabilities, Shell is the company that benefits most from the volatility in the global gas market."
The key question is how a single shift in capital discipline and project selection will shape the durability of those cash rich margins.
That capital discipline question sits at the heart of the full narrative for Shell, which maps how Shell's cash engine could accelerate or stall under different investment choices.
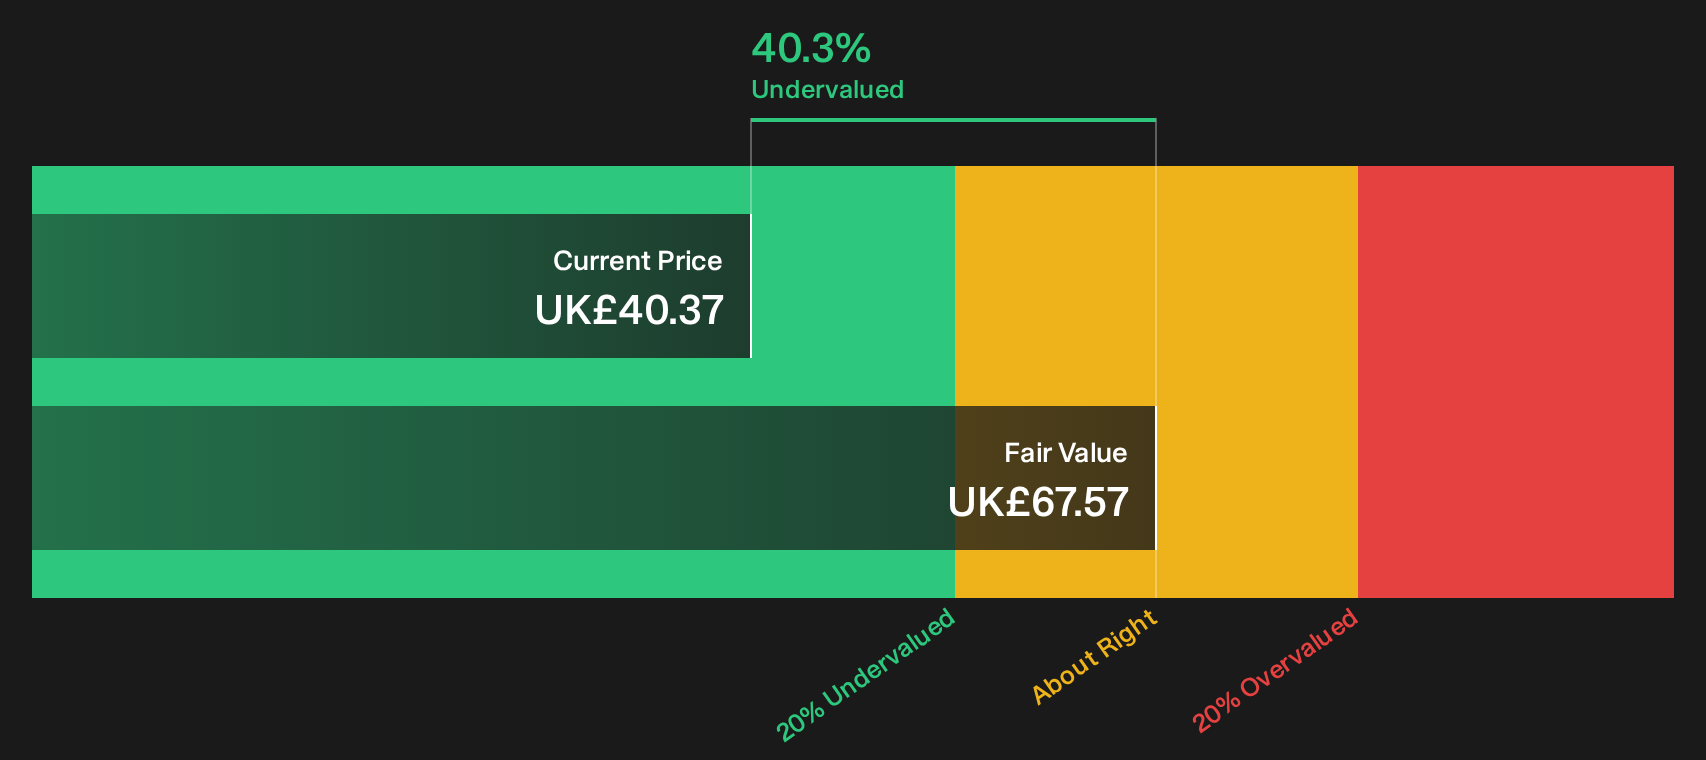
Premier Foods (LSE:PFD)
Premier Foods leans on a broad branded ambient food portfolio in the UK and abroad, which fits neatly with a screener focused on dependable cash flows backed by everyday grocery spending and long established retail relationships.
Premier Foods runs two main divisions, with Grocery producing about £860 million and Sweet Treats around £315 million in revenue, and the business carries a market value of roughly £1.7 billion.
"Planned step up in annual CapEx to £55 to £60m in FY27, directed at automated cake lines, insourced sauce capacity, new process plants and energy projects such as efficient boilers and solar arrays, is intended to lower unit costs and improve factory recovery which can support gross margin and trading profit progression."
The real test for Premier Foods is how one less visible shift in its branded mix ultimately feeds through to cash generation and valuation.
That quiet shift in mix is exactly what the full narrative for Premier Foods unpacks, tracing how capex, pricing and retailer relationships could accelerate or stall Premier Foods' cash story.

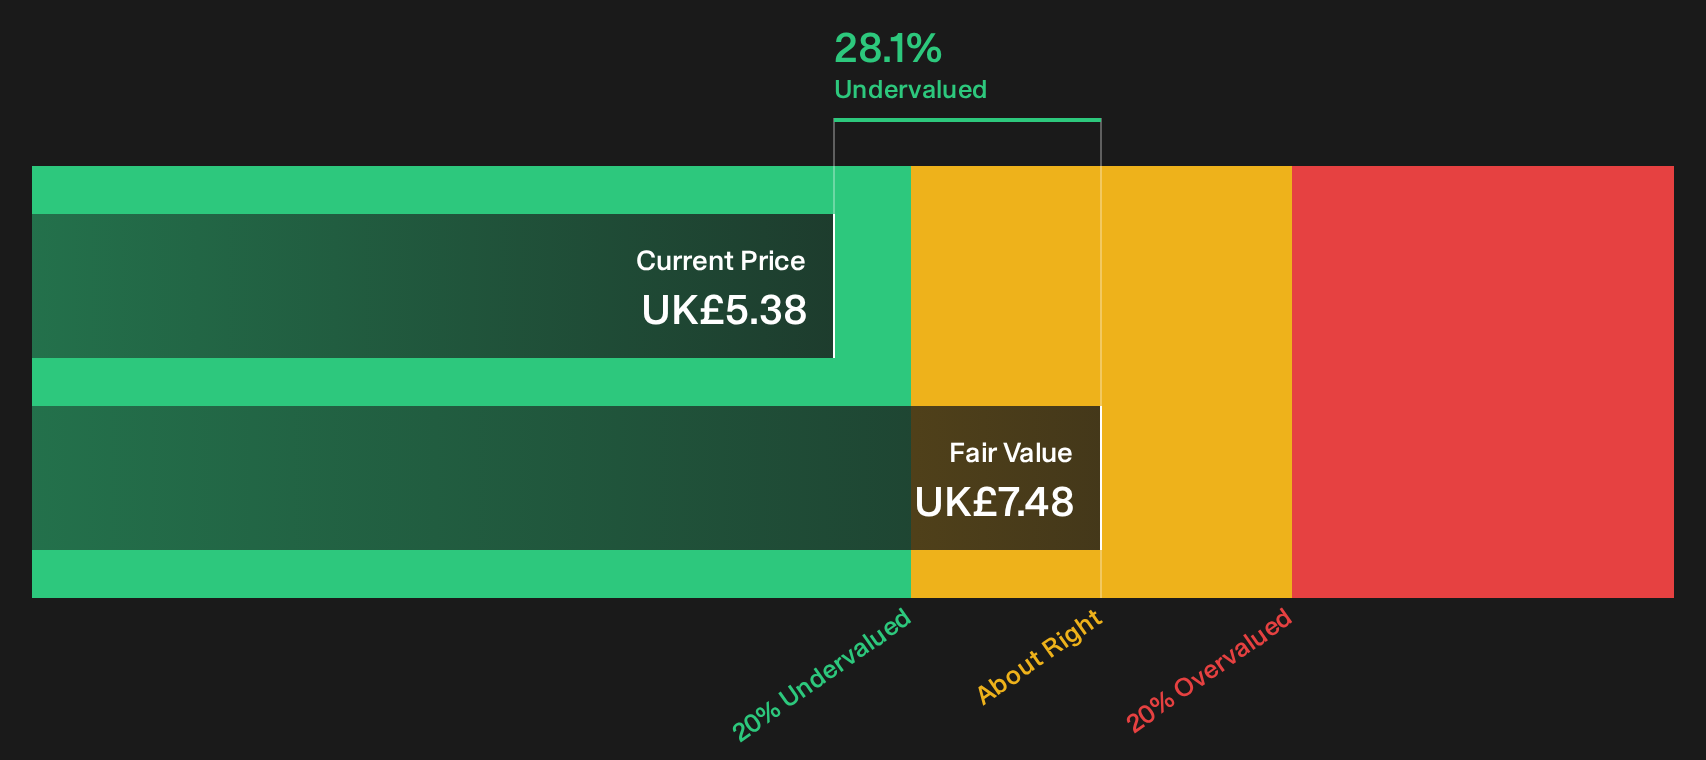
Autotrader Group (LSE:AUTO)
Autotrader Group runs a leading UK online marketplace that connects car buyers, retailers and manufacturers, with most of its cash linked to recurring subscription and advertising fees. The Auto Trader segment generated about £585 million of revenue versus £39 million from Autorama, and the group is valued at roughly £4.2b.
For the Undervalued Stocks Based On Cash Flows screen, Autotrader Group matters because its marketplace model leans heavily on predictable subscription and advertising payments that can be assessed through a discounted cash flow lens. Recent product rollouts are testing how far that engine can stretch.
"Auto Trader Group's continued rollout of Deal Builder, with inquiries and Buying Signals leads converting at least twice as well as average inquiries and around half of deals occurring outside traditional hours, points to further monetisation of higher quality leads that can support retailer revenue and Auto Trader's own ARPR and earnings over time."
The real swing factor for Autotrader Group is how one shift in how retailers adopt and price these tools ultimately feeds through to margins and cash returns.
That adoption question is exactly what the full narrative for Autotrader Group tackles. It maps where Autotrader Group's cash engine could accelerate, stall, or be quietly undervalued by the market.
Seeking Alternatives Before Others Catch On
Fresh ideas move first. Once momentum hits, the best setups can be flying before the crowd even looks. Scan curated opportunities while it matters and get in early.
- Spot reliable income candidates and use the 5 dividend fortresses to zero in on companies where strong cash payouts meet balance sheet resilience before the yields get crowded.
- Track early trend shifts and run through the 4 resilient stocks with low risk scores to pinpoint resilient businesses where steady fundamentals may matter more than share price noise.
- Target future-facing themes and tap into the 54 AI infrastructure stocks to find companies positioned around the hardware and utilities backbone of expanding AI demand.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com