


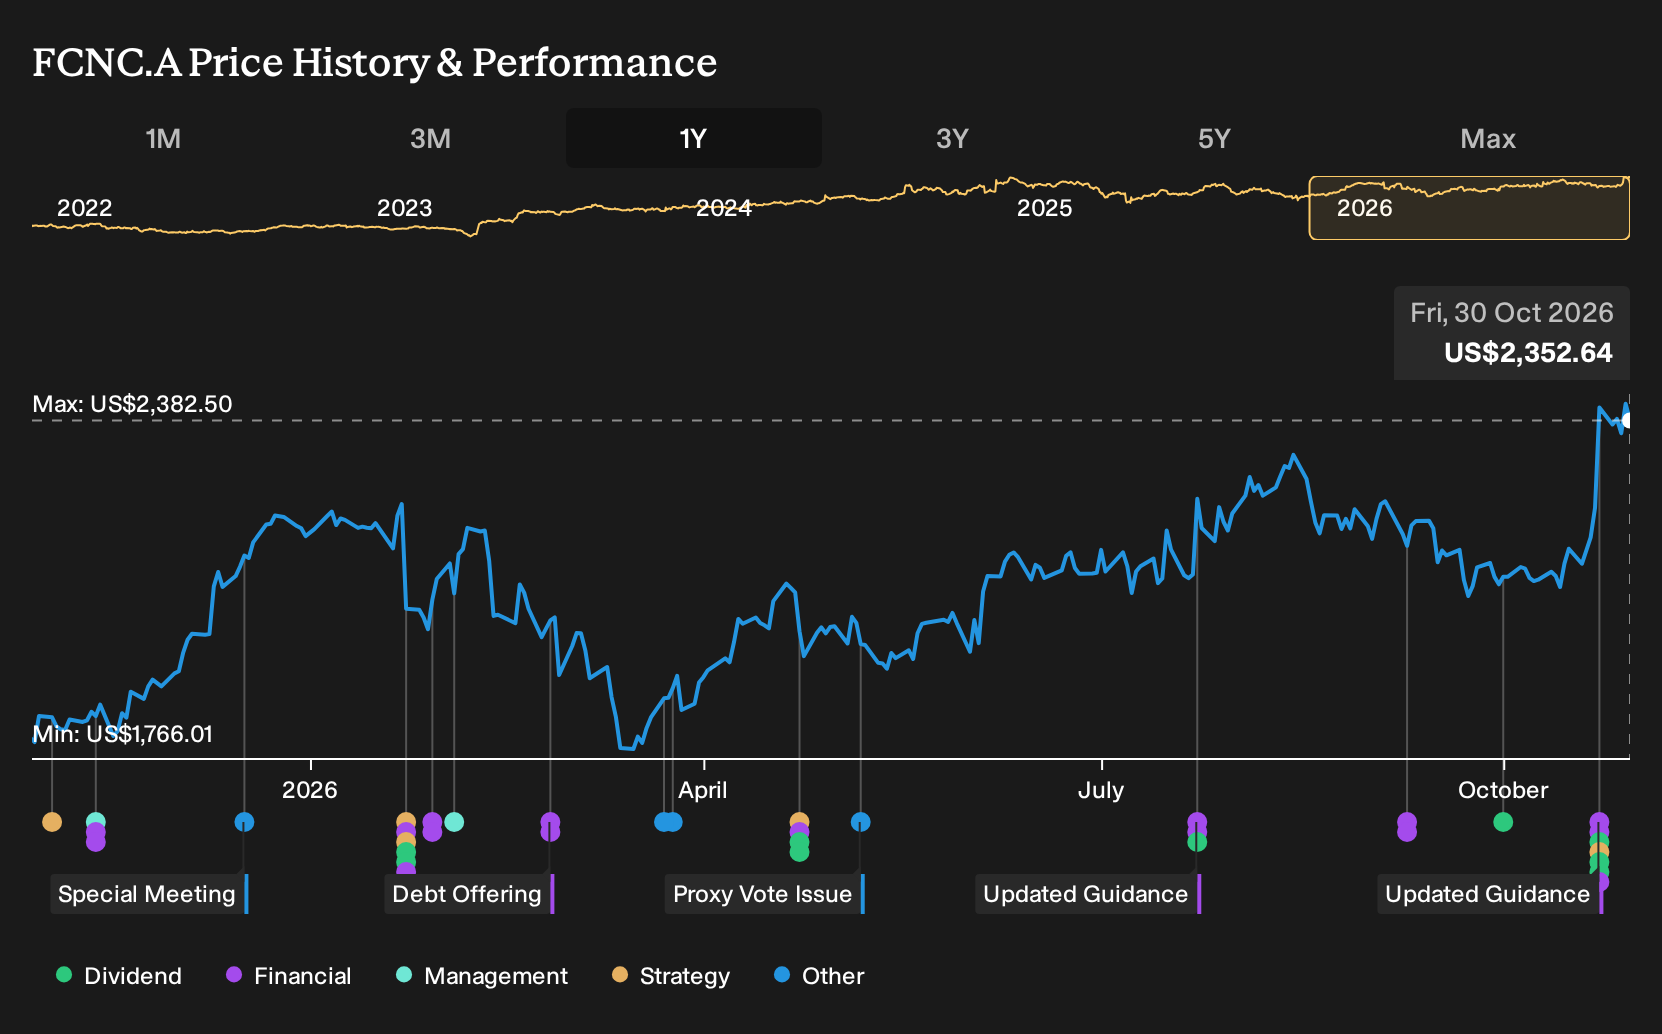
- First Citizens BancShares reported third quarter 2026 results with net income of US$606 million and basic earnings per share of US$51.23, alongside updated guidance and dividend declarations that now sit in the rear view mirror as of November 2026.
- The bank paired raised full year 2026 net interest income guidance with a US$1.2b Class A share repurchase authorization and detailed preferred dividends, highlighting how capital returns are being balanced against credit costs and funding priorities.
- We will look at how First Citizens BancShares' raised net interest income guidance reshapes the investment narrative that analysts outlined earlier.
Compare how First Citizens BancShares is returning capital with other banks by scanning our hand picked 5 dividend fortresses that emphasise income strength and payout resilience.
First Citizens BancShares Investment Narrative Recap
To own First Citizens BancShares, you need to be comfortable with a bank that is still very dependent on net interest income while working against fierce deposit competition and compressed margins. The raised full year 2026 net interest income guidance to US$6.68b to US$6.75b nudges that core earnings engine in a slightly better direction without changing the story. The key near term swing factor remains how fast funding costs stabilise relative to asset yields.
The biggest risk is that deposit pricing pressure keeps margins under strain for longer, limiting any benefit from balance sheet reshaping and loan growth in its commercial verticals. Third quarter net charge offs of US$103 million, only modestly different from US$108 million in the prior quarter, suggest credit quality is not the main near term issue. The near term focus instead stays squarely on execution around funding mix, the FDIC note paydown and expense control.
The new US$1.7b to US$1.77b net interest income range for the fourth quarter links directly to those catalysts. It frames how quickly First Citizens BancShares can turn ongoing FDIC note repayments, deposit remixing and the BMO branch conversion into a steadier earnings base. In the short term, that guidance gives you a concrete yardstick to track whether margin pressure is easing or simply plateauing.
Set against this, the US$1.2b Class A share repurchase authorisation is the announcement that interacts most clearly with the outlook. It sits alongside a US$2.25 quarterly common dividend and a full slate of preferred stock payouts, which together outline a fairly assertive capital return profile. For you as a shareholder, the question is whether earnings, asset quality and funding costs stay aligned with that level of cash being sent out rather than kept on the balance sheet.
How First Citizens BancShares' Long Term Targets Line Up
Analysts frame First Citizens BancShares' longer term story around a gradual build in both revenue and profitability. Their models point to earnings of US$2.4b by 2029 compared with about US$2.3b today. This is paired with modestly higher profit margins as efficiency projects and mix shifts filter through the income statement.
Those earnings forecasts sit alongside an assumed revenue growth rate of 1.3% per year over the next three years and a small step up in margin from 24.1% today to 24.7% by 2029. Forecasts also rely on the share count shrinking by roughly 7% annually, which ties back directly to the current US$1.2b Class A buyback authorisation and any future repurchase activity.
Valuation work in the consensus set effectively asks you to underwrite a 2029 profile that includes US$9.9b of revenue, US$2.4b of earnings and a P/E multiple of 11.0x. This is compared with about 11.5x today and 11.6x for the broader US banks group. With the current share price close to the US$2,384.38 target, the implied upside from those scenarios is limited, so the appeal of First Citizens BancShares for you hinges more on confidence in that earnings path and the durability of the capital return program than on a big pricing gap.
First Citizens BancShares' narrative projects US$9.9b revenue and US$2.4b earnings by 2029. This assumes 1.3% yearly revenue growth and an earnings increase of about US$0.1b from US$2.3b today.
Uncover why First Citizens BancShares' fair value is essentially in line with its current price.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$2,384 to US$3,742 per share, which is a wide gap for First Citizens BancShares. Those private investors have not yet incorporated the latest buyback, dividend moves or net interest income guidance. Opinions clearly differ, so consider several viewpoints before forming your own.
Explore another First Citizens BancShares fair value estimate, including one that suggests as much as 59% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your First Citizens BancShares research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for First Citizens BancShares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Citizens BancShares' overall financial health at a glance.
Looking For More Investment Ideas Beyond First Citizens BancShares?
If you want to stress test your view on First Citizens BancShares or round out your watchlist, it can help to compare it with other opportunities that share similar qualities around income, balance sheet strength, or risk profile.
- For investors who care most about stable payouts, start with a curated set of income heavyweights by reviewing 5 dividend fortresses.
- If capital preservation and steadier return potential matter to you, filter for businesses with more resilient profiles through the 29 resilient stocks with low risk scores.
- To widen the opportunity set beyond well covered blue chips, scan a focused pool of under the radar opportunities by checking out the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com