


Barclays has delivered a striking 3 year share price climb, while recent headlines around job cuts, AI investment and regulatory scrutiny keep the story in flux. That puts fresh focus on whether the current valuation lines up with the bank's earnings power.
- Over the past 3 years the stock has gained 234.6%, so a lot of investor capital is now riding on how durable its profit engine really is.
- The plan to remove about 5,000 roles and lean harder on AI may support lower running costs and potentially reshape how much of each pound of revenue turns into earnings over time.
- The analysts covering Barclays have run their own numbers. See what analysts think Barclays's shares could be worth.
For investors, the debate is whether Barclays' recent share price level is adequately supported by what its current earnings justify.
If you want to stress test whether Barclays' earnings based valuation question also shows up elsewhere in the market, compare it with 14 high quality undervalued stocks.
Where Does Barclays Sit on Earnings?
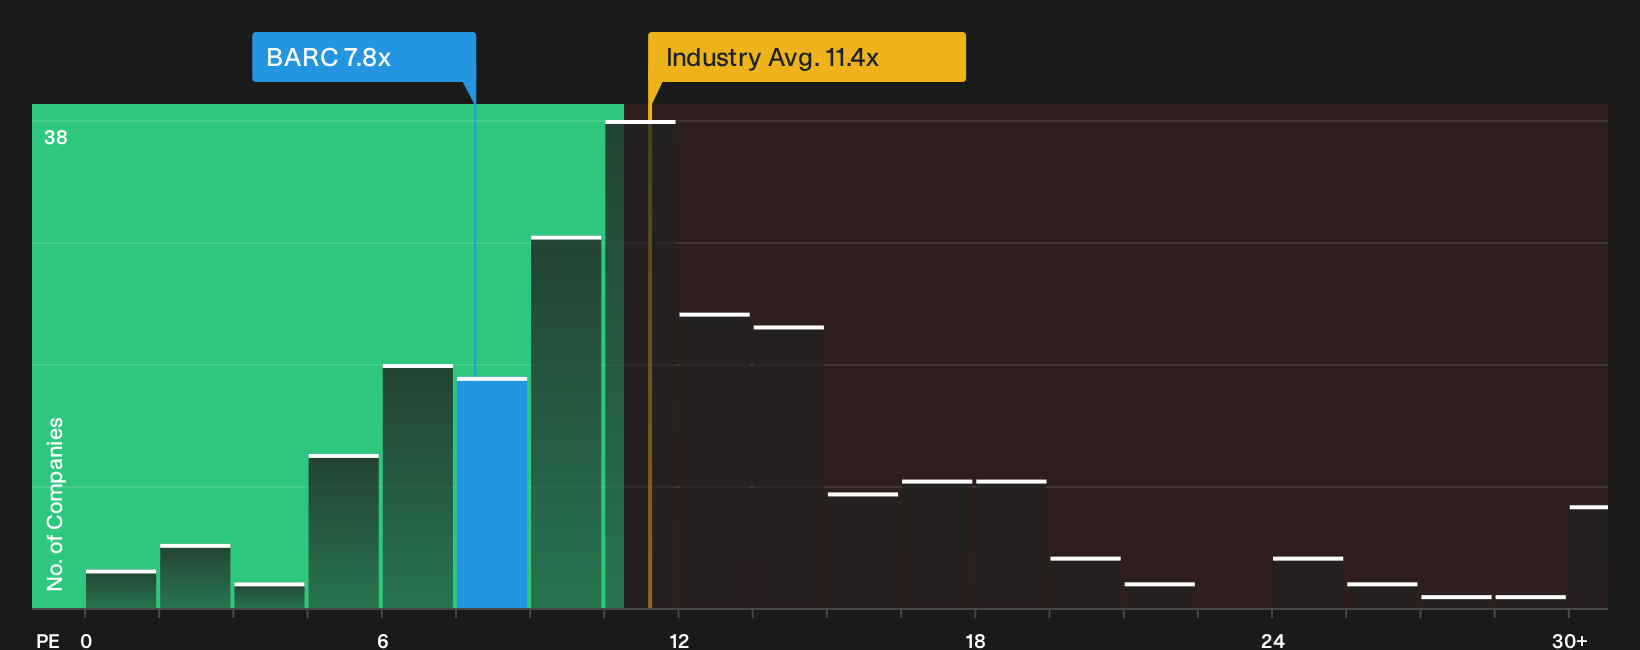
The P/E ratio fits Barclays because earnings remain the key yardstick for banks where balance sheets are tightly regulated. On this metric, the stock trades on about 7.8x earnings, which sits below the wider banks industry on 10.9x and also under the peer group at roughly 9.8x. That points to a lower earnings multiple than many comparable lenders, even before you factor in the share price run of the past three years.
The tailored fair multiple, which blends Barclays specific growth, returns and risk profile, points to a level close to where the shares change hands today. In other words, the current P/E lines up with what that framework would suggest. Because the recent plan for 5,000 job cuts and heavier AI use is aimed at trimming costs rather than inflating near term profits, the gap between price and this earnings based yardstick has not blown out in either direction. Explore the numbers behind Barclays's P/E valuation.
The Barclays Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Barclays give you a clear bridge from the valuation puzzle above to what would need to happen next. Each scenario spells out the earnings, margin and growth assumptions that would need to hold for Barclays' share price to look meaningfully higher or lower than today, and sets out the moving parts behind that view so you can compare those expectations with the results as they come through.
One of the top community narratives on Barclays: 26% undervalued
"Combined with a price-to-earnings ratio of around 10, the price-to-book ratio suggests a puzzling lack of confidence in Barclays' future profitability and earnings durability..."
Discover why this Narrative puts Barclays at 26% undervalued.
Barclays valuation still leaves one crucial angle open
Numbers only tell part of the story for Barclays, because the people setting priorities and the way their rewards are structured can heavily influence how value is created or eroded over time. See who runs Barclays and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com