


SEGRO has rewarded shareholders with a 36.5% gain over the past year, helped by rising rents and solid tenant demand, which naturally raises the question of whether the current share price is still in step with its earnings power. For anyone looking at the stock today, the issue is less about momentum and more about what that recent performance implies for the underlying profit stream.
- A 36.5% one year return puts real weight on the question of whether SEGRO's current earnings profile can support the higher valuation investors are now paying.
- News of a 32% rise in new headline rent to £70 million, stronger occupancy and a planned UK big box joint venture may support expectations for how the business can convert its property portfolio into future income and profit.
- The analysts covering SEGRO have run their own numbers. See what analysts think SEGRO's shares could be worth.
The issue now is whether SEGRO's current share price is justified by the earnings that the business is generating today.
If you want a wider set of ideas built around similar earnings questions, a focused screen of 14 high quality undervalued stocks can be a useful next starting point for your research.
Is SEGRO Getting Expensive on Earnings?
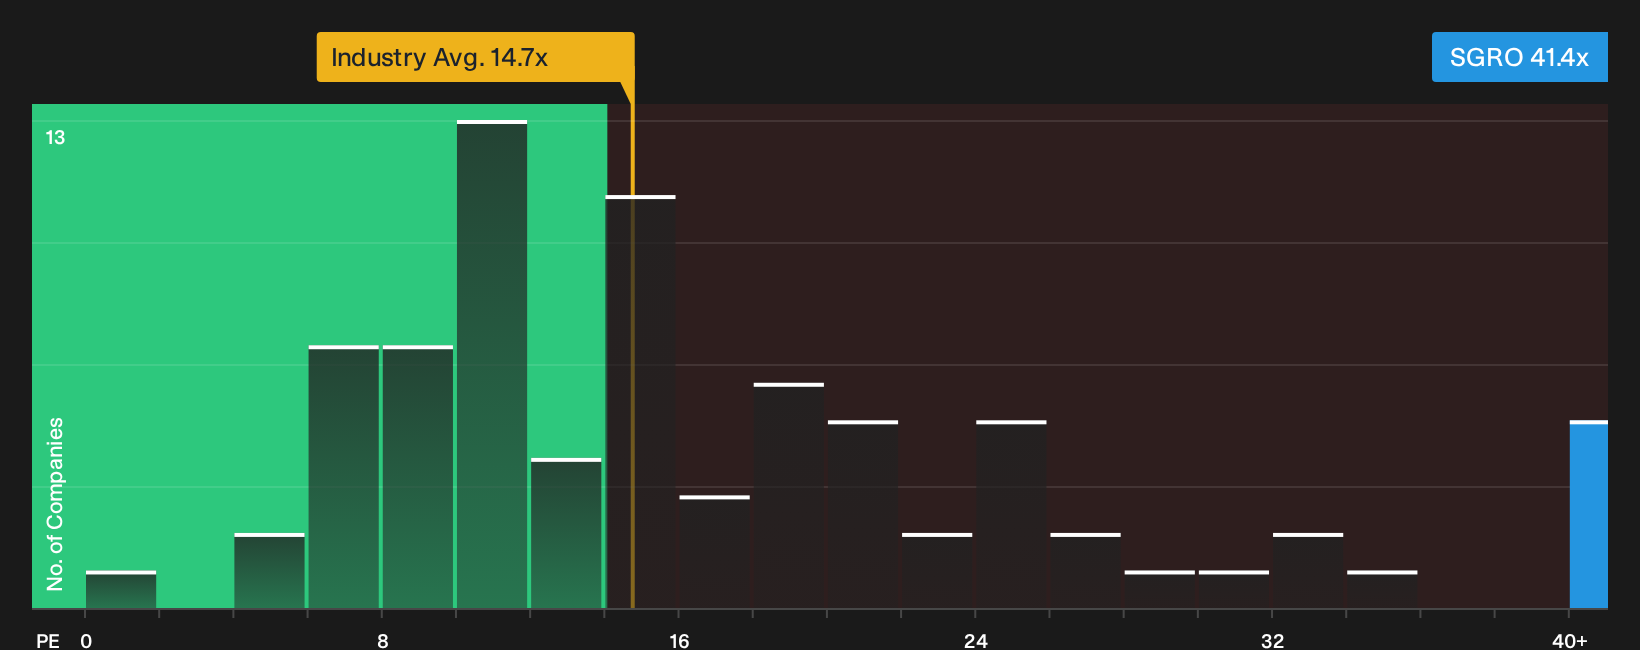
P/E works well for SEGRO because earnings capture how effectively its property portfolio turns rent into bottom line profit. On this yardstick, the shares trade on a P/E of 41.4x, compared with around 14.7x for the wider Industrial REITs group and roughly 14.0x for direct peers. That is a sizeable premium for access to the same broad sector economics.
The valuation model that blends SEGRO’s growth profile, margins, size and risk suggests a lower multiple would be more typical for this kind of earnings stream. As a result, the current 41.4x screens as overvalued against that tailored benchmark. Because the recent jump in contracted headline rent and the planned UK big box joint venture have already pushed sentiment higher, the present P/E implies investors are paying up in advance for a lot of that good news. Explore the numbers behind SEGRO's P/E valuation.
The SEGRO Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up the SEGRO puzzle from here by spelling out which paths for rent growth, margins and earnings would need to play out for the current valuation to look stretched or still conservative. Rather than a single headline multiple or model figure, each one lays out the assumptions sitting behind its view of fair value so you can line those up against SEGRO's actual results as they come through on the Community page.
One of the top community narratives on SEGRO: roughly fairly valued
"Segro's power reserves and high-yield projects, which we characterized as a 'hidden treasure' on its balance sheet, inevitably made the company a highly attractive acquisition target..."
Discover why this Narrative puts SEGRO at roughly fairly valued.
One more SEGRO clue before you decide what to do next
You have seen what the current P/E says about SEGRO today, but professional analysts have mapped out where they think earnings and rent-driven profit could be a few years down the road. Explore where analysts expect SEGRO to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com