


Why Ocular Therapeutix Is Back On Investor Radars
Ocular Therapeutix (OCUL) has drawn fresh attention after a recent special call highlighted plans to seek FDA approval for AXPAXLI through an NDA submission targeted for the fourth quarter of 2026.
The recent special call and focus on AXPAXLI arrive after a mixed stretch for Ocular Therapeutix, with the share price down 41.03% year to date and 18.86% over 90 days, even as the 3 year total shareholder return is up more than 2x.
In the short term, the 7 day share price return of 7.73% contrasts with a 1 day decline of 4.65%. This suggests traders are reacting quickly to clinical and regulatory headlines, while longer term holders have already experienced very different outcomes depending on their entry point.
At a last close of US$6.97, that combination of recent share price pressure and a very strong 3 year total shareholder return points to shifting views on both the growth potential of AXPAXLI and the risks investors see around execution and regulation.
Scan beyond Ocular Therapeutix and size up other biotech names with potential breakout catalysts using our hand picked 19 high quality undiscovered gems list.
The recent swing in Ocular Therapeutix looks torn between improving clinical progress and a reset in expectations. How much of today’s price really reflects the underlying business rather than changing sentiment around AXPAXLI?
Most Popular Narrative: 73% Undervalued
Against a last close of $6.97, the most followed narrative for Ocular Therapeutix points to a fair value of $25.45, which puts recent share price weakness against a much higher long term assumption for AXPAXLI and the broader pipeline.
The anticipated approval of AXPAXLI, potentially the first wet AMD product with a superiority label and longer dosing intervals (every 6 to 12 months), may allow Ocular Therapeutix to capture significant market share in a rapidly growing population of elderly patients with retinal disease, unlocking large revenue growth opportunities as the global prevalence of ophthalmic disorders increases.
See why 12 investors see Ocular Therapeutix as 73% undervalued.
This narrative applies a 7.24% discount rate to analysts' long range forecasts, tying fair value to expectations for AXPAXLI, DEXTENZA and follow on retinal indications rather than to current losses of $301.4 million or today's $52.1 million in revenue. It leaves very little room for disappointment on clinical data, payer decisions or commercialization timing because most of the gap between price and modeled worth comes from assumed execution on those future milestones.
Result: Fair Value of $25.45 (UNDERVALUED)
Still, the whole Ocular Therapeutix story leans heavily on AXPAXLI, so any clinical stumble or tougher than expected payer pushback could quickly unwind that undervalued narrative.
Find out about the key risks to this Ocular Therapeutix narrative.
Another View On Ocular Therapeutix Valuation
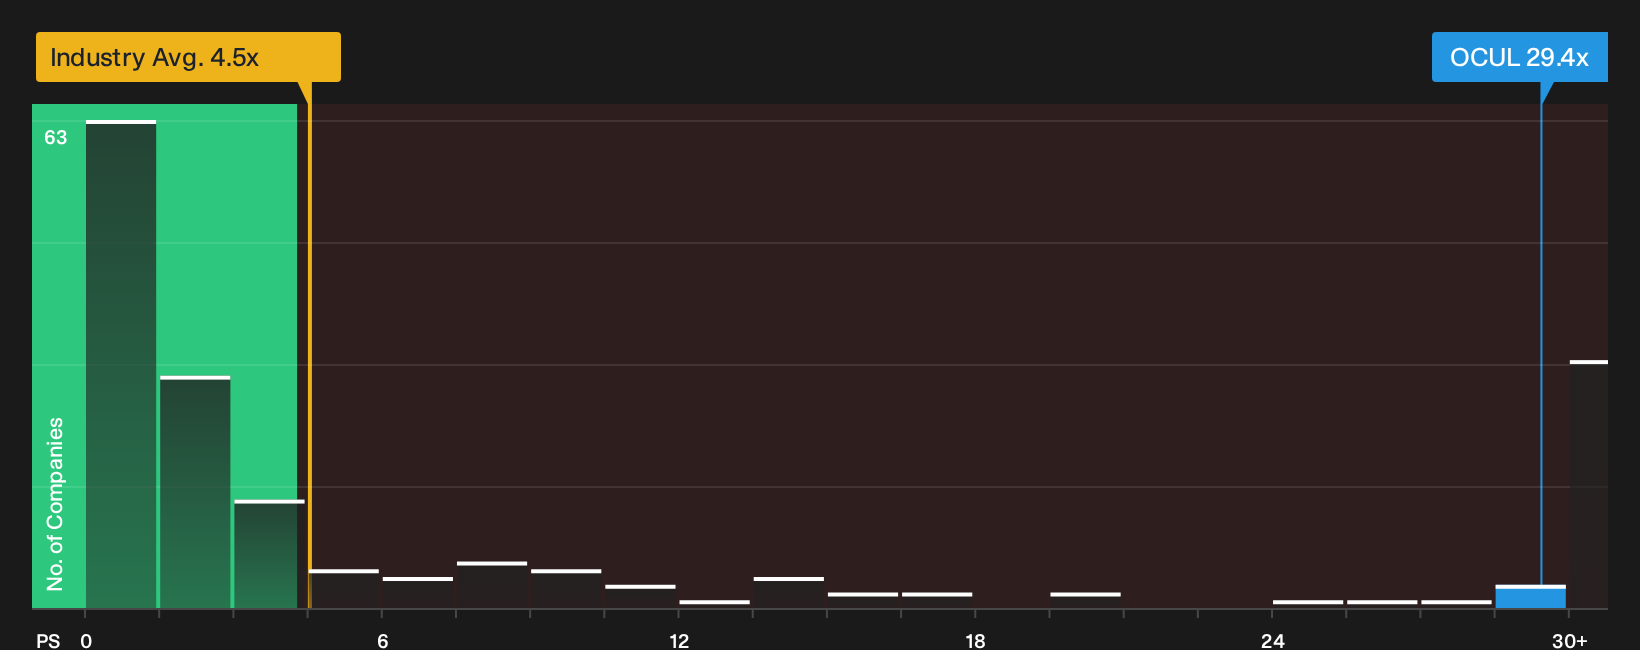
That big 73% gap between Ocular Therapeutix's share price and the implied fair value tells only one story. On simple P/S, the picture flips. OCUL trades around 29.4x sales versus 4.5x for the US Pharmaceuticals group, a peer average of 6.2x, and a fair ratio of just 0.2x. That kind of premium leaves very little margin for error if the pipeline underdelivers.
To see how that rich sales multiple compares with the underlying assumptions, have a look at See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Conflicted about whether Ocular Therapeutix is a turnaround story or a crowded trade at this price, given both clear risks and clear potential rewards. Act quickly, review the full picture, and weigh the 2 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Ocular Therapeutix?
If Ocular Therapeutix has you rethinking risk and reward, broaden your watchlist now using focused screeners that surface clear, data-backed ideas before the crowd moves.
- Target resilience first and cut portfolio stress by leaning on the 29 resilient stocks with low risk scores that filters for companies with steadier profiles.
- Identify potential value and avoid overpaying by scanning the 36 high quality undervalued stocks that highlights businesses trading below their assessed worth.
- Strengthen your core holdings with balance sheet quality by using the list of solid balance sheet and fundamentals (24 results) that focuses on financial durability and fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com