


Krystal Biotech (KRYS) is back in focus after reporting third quarter and nine month 2026 earnings, alongside a new share repurchase program of up to US$400 million authorized by its board.
Recent trading reflects that story. Krystal Biotech’s share price has climbed 34.58% year to date, and the 1 year total shareholder return of 67.95% suggests strong longer term momentum, with the new US$400 million buyback and earnings update adding fresh fuel to that move.
Scan how Krystal Biotech compares to other potential breakout ideas by checking a curated 19 high quality undiscovered gems with strong fundamentals that have not yet attracted broad attention.
Krystal Biotech now combines a profitable genetic medicine platform with a US$400 million buyback and a share price near US$332. The real tension is simple: is that quality already fully reflected in the valuation?
Most Popular Narrative: 15.3% Undervalued
Set against Krystal Biotech’s last close of $332.29, the most followed narrative points to a fair value of $392.11. This frames the buyback and current momentum as only part of a bigger story driven by cash generation and pipeline breadth.
Advancement of Krystal Biotech toward a multiproduct genetic medicines company through late stage programs such as KB803, KB801, KB407, KB111, KB707 and KB408, supported by HSV 1 platform technology designations, could broaden the revenue base beyond Vyjuvek and spread fixed costs across multiple products.
See why 35 investors see Krystal Biotech as 15% undervalued.
Result: Fair Value of $392.11 (UNDERVALUED)
Still, pricing pressure on Vyjuvek in Europe and the higher spending needed for KB707 and other late stage programs could challenge the bullish Krystal Biotech narrative.
Find out about the key risks to this Krystal Biotech narrative.
Another View: Krystal Biotech Through The P/E Lens
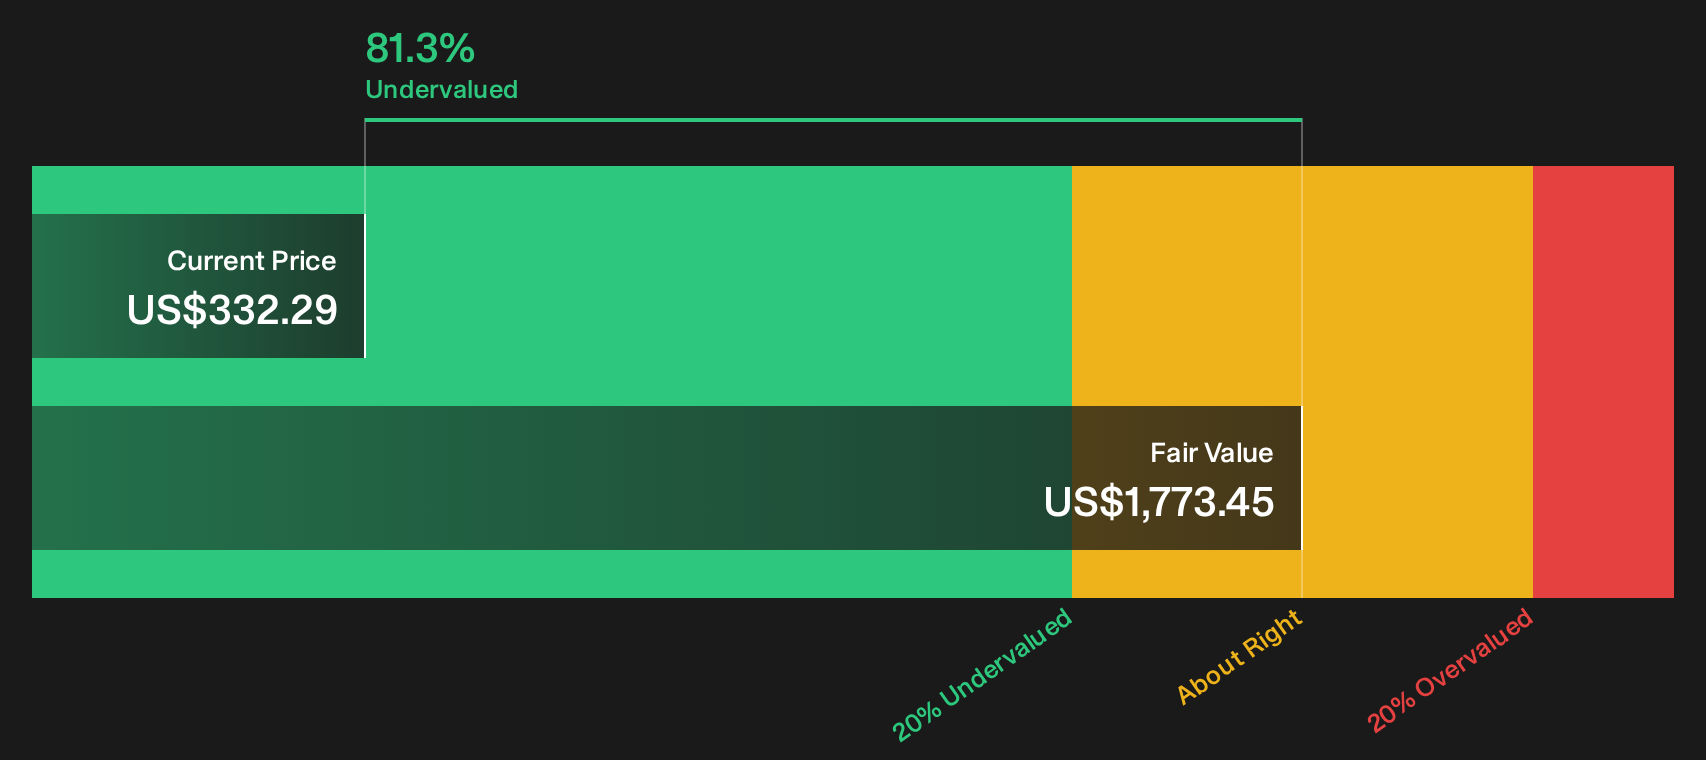
The SWS DCF model points to Krystal Biotech trading well below an estimated future cash flow value of $1,773.45, which aligns with the idea of underpricing. A simple P/E check tells a different story. The stock trades at 40.7x earnings versus 19.2x for the US Biotechs industry and a fair ratio of 34x, which implies investors are already paying a premium that could shrink if sentiment cools.
To see how this cash flow based view is constructed, and where the assumptions matter most, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Krystal Biotech so far. Risks and rewards are both in play, so move quickly, review the data, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Krystal Biotech?
If Krystal Biotech has your attention today, do not stop there. Broaden your watchlist with data driven ideas that could reshape how you allocate your next dollar.
- Target potential mispricing by scanning a 36 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Strengthen your income stream by reviewing a 5 dividend fortresses focused on companies combining higher yields with ongoing payout support.
- Reduce portfolio stress by reviewing a 29 resilient stocks with low risk scores tailored to resilient businesses with lower risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com