


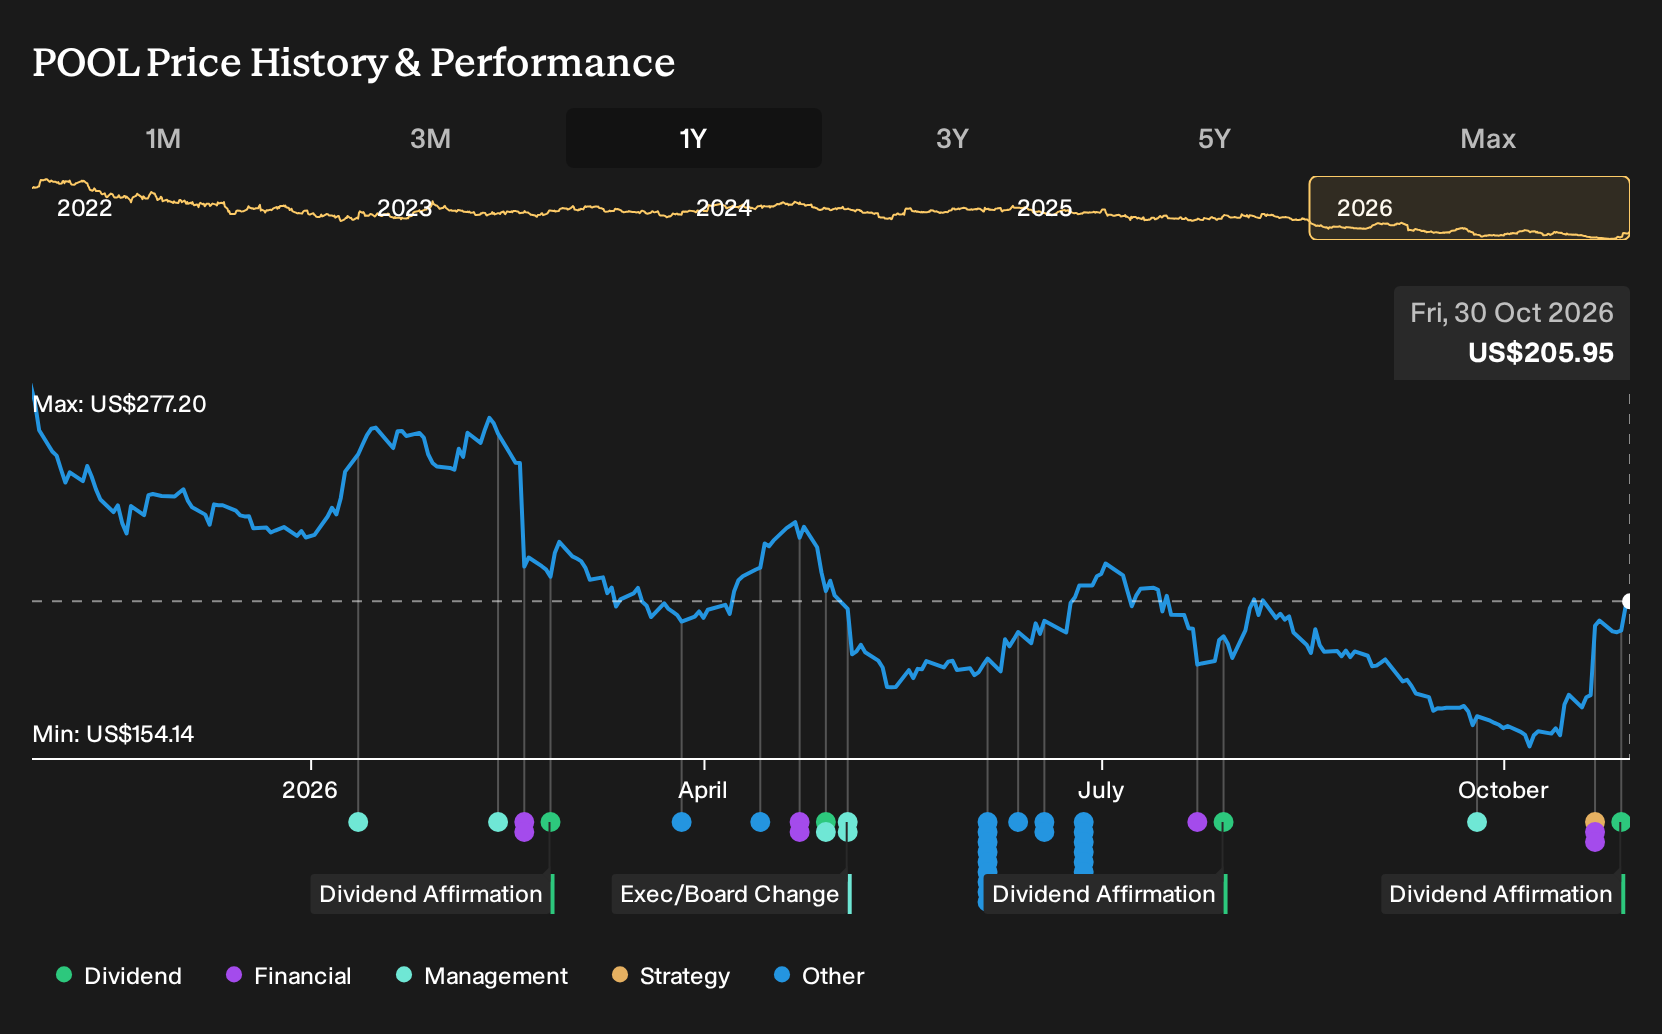
- Pool Corporation reported third quarter 2026 sales of US$1,504.96 million and diluted EPS from continuing operations of US$3.40, confirmed full year 2026 earnings guidance of US$10.66 to US$10.96 per diluted share, and affirmed a quarterly dividend of US$1.30 per share that was paid on November 25, 2026.
- Management reiterated a programmatic M&A approach that targets operational fit and culture, using acquisitions, dividends and share repurchases alongside a conservative leverage profile to support Pool Corporation's existing markets and capabilities.
- We will look at how Pool Corporation's confirmed 2026 earnings guidance may influence the investment narrative around recurring demand and capital allocation.
Scan beyond Pool and compare its mix of earnings guidance, dividends and M&A activity with a curated 19 high quality undiscovered gems that share strong fundamentals but attract less attention.
Pool Investment Narrative Recap
To hold Pool, you need to believe its large installed base and maintenance-heavy sales can keep earnings relatively steady even when new pool construction or discretionary upgrades slow. The confirmed 2026 EPS guidance of US$10.66 to US$10.96 suggests management still sees the current demand mix and gross margin pressures as manageable in the near term.
The biggest swing factor right now is whether freight costs, customer mix and Horizon softness ease or stay sticky. The latest quarter showed flattish diluted EPS year on year, so the update does not fundamentally shift that risk-reward balance. It is more a confirmation than a reset.
The most relevant piece of news for you is Pool confirming its full-year 2026 diluted EPS range alongside the third quarter report. That guidance gives a reference point for how management is thinking about freight expenses, Horizon irrigation weakness and the mix toward larger customers that has already weighed on gross margin by roughly 30 basis points.
For catalysts, this guidance sits next to management's focus on POOL360 adoption, higher-margin private label products and a slower buildout of new sales centers. The earnings range, paired with the affirmed US$1.30 quarterly dividend and ongoing capital returns, keeps attention on execution, cost discipline and the ability to keep turning the recurring maintenance base into consistent cash generation.
Pool's narrative projects US$5.9b revenue and US$461.4 million earnings by 2029. This assumes 3.2% yearly revenue growth and an earnings increase of about US$63.6 million from US$397.8 million today.
Uncover why Pool's fair value indicates a valuation gap that is roughly in line with its current price.
Exploring Other Perspectives
One alternate angle on Pool Corporation focuses on slower digital traction. The most bearish analysts were modelling revenue growth of about 2.8% a year and 2029 earnings of roughly US$432.4 million before this guidance and dividend news. That is a more cautious story than consensus. It is your cue to compare different forecasts side by side.
Explore 2 other Pool fair value estimates, including one that suggests as much as 15% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Pool research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Pool. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pool's overall financial health at a glance.
Looking For More Ideas Beyond Pool?
Once you understand Pool Corporation, it can help to contrast its profile with other businesses that share features you care about, whether that is valuation support, balance sheet strength or a focus on steadier cash flows.
- If you are hunting for quality at a reasonable entry point, compare Pool with a 36 high quality undervalued stocks that screens for companies with strong fundamentals trading below their estimated worth.
- For readers who care more about resilience than excitement, compare Pool's risk profile with a 29 resilient stocks with low risk scores that highlights businesses with sturdier financial and business risk scores.
- If you want to focus on financial staying power, evaluate Pool alongside a list of solid balance sheet and fundamentals (24 results) that filters for companies with healthier leverage and liquidity metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com