


Key Points
Even as it cuts spending in some places, it needs to increase it in others.
Lucid plans to increase vehicle service support staff by 35% this year alone.
Improving Lucid's customer service is a must, even if overlooked by investors.
Investors in Lucid Group (NASDAQ: LCID) have heard plenty about what its vehicles can do. Impressive technology, compelling performance, and an expanding lineup could give shareholders reasons to believe the company has something worth saving. But the ownership experience is key, too.
Here's what most investors don't consider at all: If taking care of the vehicle becomes a headache, another impressive feature won't necessarily convince the next customer to sign up and buy. All in all, there's one consistently overlooked aspect that makes one less-glamorous part of Lucid's turnaround worth watching: service.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
A problem that management recognizes
Management is investing in the people and capacity needed to support customers, even as it tries to bring spending under control elsewhere. Remember that Lucid has identified $1.4 billion in cash-flow saving opportunities, which will be crucial to execute in the near term. For long-term investors, that could be one of its more important balancing acts.
During Lucid's second-quarter earnings call, CEO Silvio Napoli acknowledged that the company had underinvested in service, responded too slowly to quality issues, and launched products before they were ready. He said those shortcomings had strained trust with customers and investors. That's a tough admission from the person running the company. It also helps explain why Lucid's turnaround requires more than another vehicle launch, especially considering the importance its delayed Cosmos model and platform could have.
The response includes plans to increase technicians and dedicated customer-support staff by 35% by year-end, alongside more than 20% additional mobile service capacity. Combined with better parts availability and service operations, management expects those efforts to reduce wait times by more than 30%. Its earnings release described the goal as a one-third reduction this year.
Those are targets, rather than completed improvements. But they give shareholders something specific to follow beyond promises to put customers first. Rivian Automotive offers a useful comparison.
Rival Rivian shows why
In a February update, Rivian reported that scheduling wait times had declined 35% during 2025. It also said it had added and trained more than 1,000 service specialists over the preceding year and planned to increase its mobile service van fleet by 50% during 2026. That doesn't establish which company offers faster appointments. Their starting points, networks, and customer needs differ. But that said, what it does show is that expanding service is a practical priority for another young EV maker trying to grow.
Rivian also described how remote diagnostics can identify problems before a vehicle arrives, helping technicians prepare and ensuring parts are available. Sometimes, an over-the-air update can resolve the issue without a visit.Lucid's opportunity follows the same basic concept: Make ownership easier while building the capacity to support more vehicles. A service appointment shouldn't become an endurance sport simply because the car has impressive endurance.
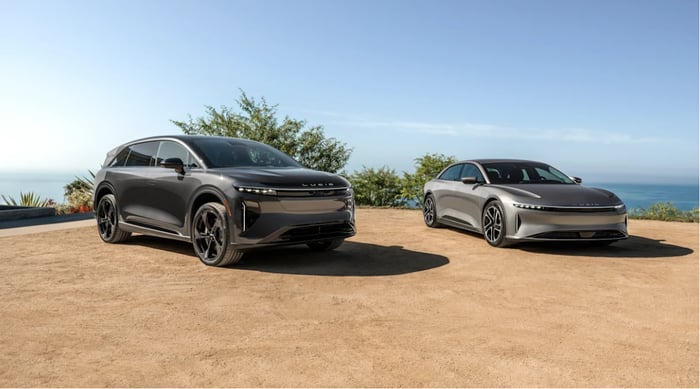
Image source: Lucid.
Why investors should care
For Lucid, this is about protecting the appeal of its lauded vehicles after the sale -- a critically overlooked aspect of its business and future potential.
A satisfied owner can become a repeat buyer or recommend the brand to somebody else. A frustrating ownership experience can work in the opposite direction. Better service could help Lucid turn its technology into a more convincing sales pitch, although management hasn't exactly quantified that potential benefit.
For investors familiar with Lucid's cash burn, hiring more technicians might sound like reaching for the credit card while trying to pay down the balance. But management is also targeting $1.4 billion in cash-flow improvements during 2026, including roughly $600 million to $800 million from inventory reductions. As we recently explored, converting excess inventory into deliveries and cash is an important part of that effort.
The goal shouldn't be to cut every expense. It should be to free up cash while protecting investments that give customers a reason to buy -- and stay with -- the brand. Better service belongs in that conversation, although Lucid still needs to show that the additional spending can deliver results. Lucid already has vehicles that attract attention, and arguably they are among the best EVs on the road today.
That said, its turnaround needs an ownership experience that gives customers a reason to come back -- and maybe bring somebody with them.
Daniel Miller has no position in any of the stocks mentioned. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.