


- Sempra is heading into its next earnings release with analysts expecting quarterly EPS of $1.18 and revenue forecasts that are above the prior year’s period, putting attention squarely on how its regulated utilities and infrastructure assets are currently performing.
- The mix of regulated utility earnings, long term infrastructure contracts and Texas growth projects has become a focal point for assessing how much earnings resilience is already reflected in Sempra’s current valuation.
- We will now look at how Sempra's investment narrative could be influenced by expectations for an earnings beat driven by regulated operations.
Compare Sempra’s earnings setup with other regulated utilities and infrastructure players by scanning a hand picked 42 power grid technology and infrastructure stocks focused on the same grid and transmission theme.
Sempra Investment Narrative Recap
Sempra appeals to investors who want a mix of regulated utility cash flows and long term infrastructure exposure. To stay comfortable as a shareholder, you need confidence that the Texas grid buildout and California utility operations can support steady earnings while LNG projects move from construction into contribution. The current earnings setup, with expectations around $1.18 EPS, mainly tests how well those regulated businesses are running right now.
The biggest near term catalyst is whether regulated operations deliver a clean quarter that supports the multi year capital plan in Texas. The main risk remains regulatory change in California or Texas that could pressure allowed returns or delay recovery of recent spending. This earnings report looks important for signalling how much room management has to keep funding that build program without stretching the balance sheet.
The most relevant backdrop to this earnings print is the capital intensive push in Texas. Oncor’s US$47.5b five year base capital plan, plus another US$10b of identified projects, means Sempra is committing a very large amount of capital into transmission and distribution just as investors are watching cash generation and interest coverage closely.
That grid investment is paired with capital recycling at Sempra Infrastructure, including the planned sale of a 45% stake and prior Ecogas México divestiture. Together, these are expected to remove close to US$9b of debt from the consolidated structure. For you, the key link to the current quarter is simple: any evidence that regulated earnings comfortably fund interest, dividends and that capex pipeline will matter more than short term share price moves.
Sempra Earnings and Valuation Expectations
Sempra's longer term story now comes with some clear numbers attached. Analysts are working off the idea that annual revenue could reach about US$14.1b and earnings about US$4.1b by 2029. That path assumes revenue growth of roughly 1.3% a year and an increase in earnings from about US$2.3b today, which implies an earnings uplift of roughly US$1.8b over that period.
Uncover why Sempra's fair value indicates a 15% potential upside to its current price that could narrow quickly.
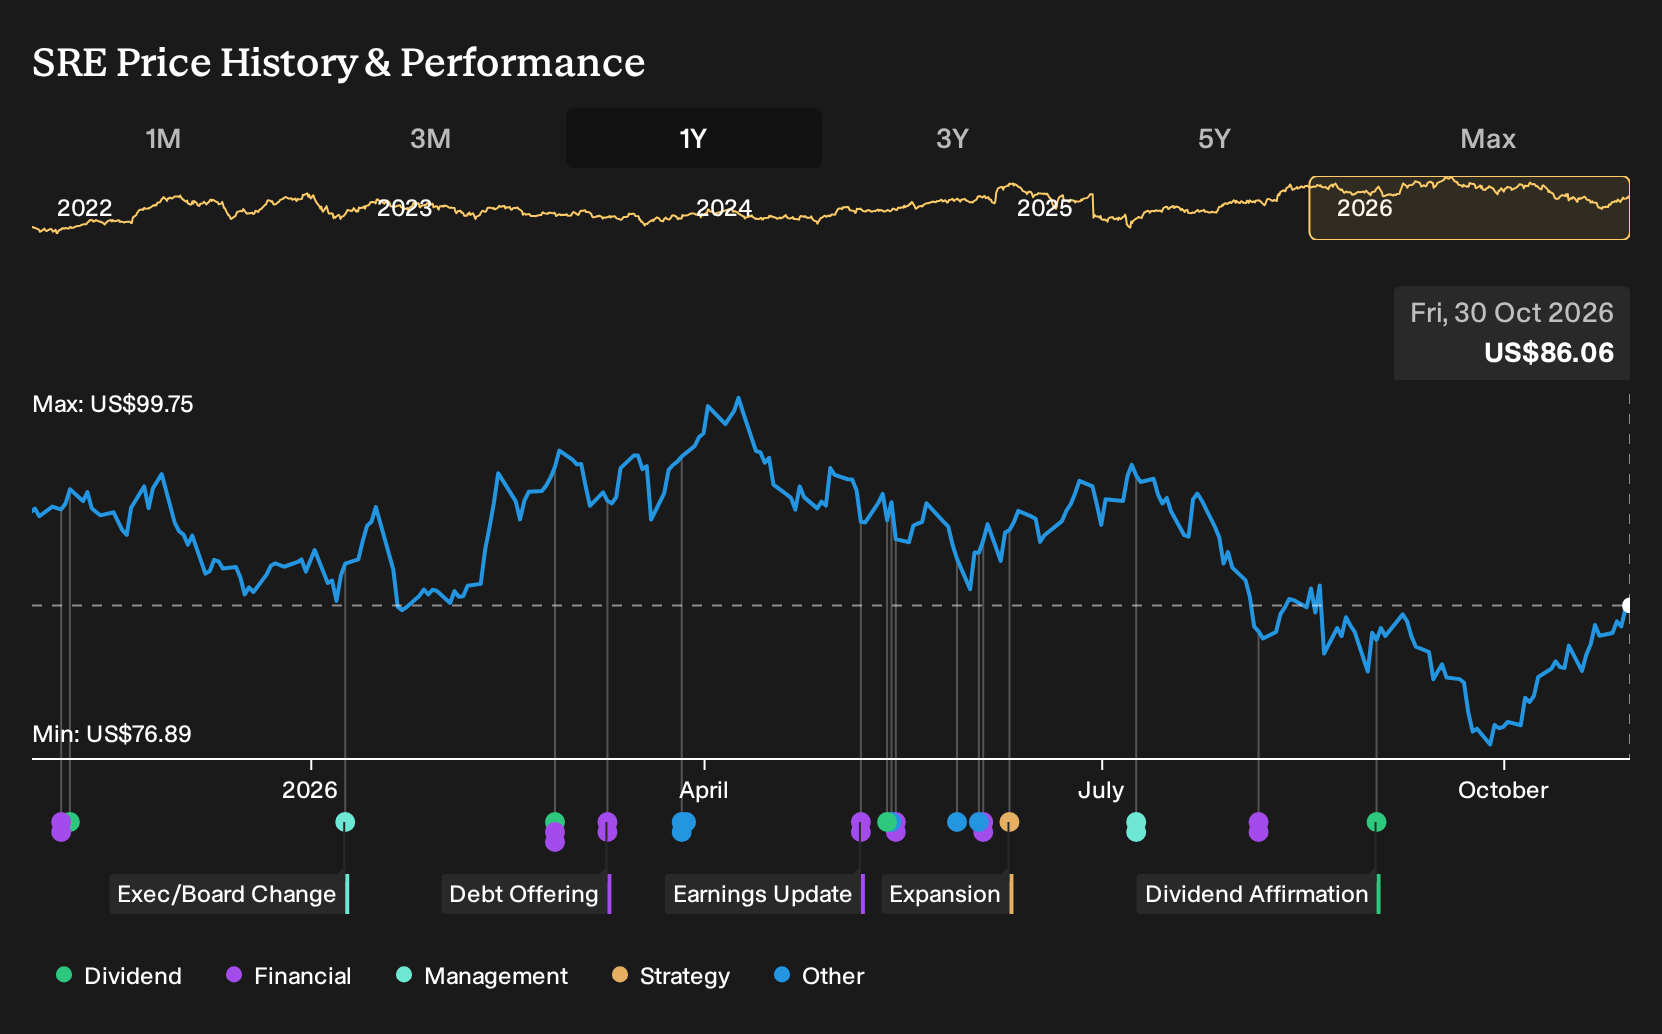
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide range, from about US$45.56 to roughly US$99.03, which reflects very different views on Sempra. Set those community opinions against Texas demand growth, regulatory risk in California and LNG project timing, and then decide which scenarios you want to explore further.
Explore another Sempra fair value estimate, including one that suggests as much as 47% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view based on thorough research.
- A great starting point for your Sempra research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sempra. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sempra's overall financial health at a glance.
Looking for more Sempra style investment ideas?
Once you have a view on Sempra, it can help to cross check that thesis against other companies with stronger balance sheets, different income profiles or a wider range of potential outcomes using the Simply Wall St Screener.
- If you want businesses that aim to combine dependable finances with a margin of safety, scan a 36 high quality undervalued stocks that filters for both quality and price discipline.
- If income matters to your portfolio, compare Sempra with a curated set of 5 dividend fortresses that focus on higher yields backed by sturdy fundamentals.
- If resilience is your priority, broaden your watchlist with a 29 resilient stocks with low risk scores designed to highlight companies with lower risk scores across several dimensions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com