


Arlo Technologies (ARLO) has put a fresh US$100 million share repurchase plan on the table. It was approved on 27 October 2026 and runs through the end of 2028, giving investors a new capital allocation signal.
Arlo Technologies shares trade at US$14.47 and have climbed 16.9% over the past week and 13.2% over the past month, yet the 1 year total shareholder return is down 23.7% even after a 59.7% gain over three years and 108.5% over five years, which points to shorter term momentum improving while longer term holders still sit on sizeable gains overall.
Scan beyond Arlo Technologies and see how other security and hardware names with improving momentum line up in our hand picked 19 high quality undiscovered gems list.
Bulls see a growing platform and a fresh US$100 million buyback supporting the current share price. Bears point to a premium tag and mixed recent returns. Which side does Arlo Technologies valuation evidence support next?
Most Popular Narrative: 32% Undervalued
On the most followed view, Arlo Technologies screens as undervalued, with a fair value of $21.40 against the latest close at $14.47. That gap rests on how the subscription engine is expected to reshape the business mix over time.
Continual migration of subscribers to higher-priced AI-driven service tiers (Arlo Secure 6) and the corresponding increase in ARPU (now over $15, up 26% y/y) reinforces the long-term shift to recurring, high-margin (85% non-GAAP service margin) subscription revenue, supporting expanding net margins and earnings visibility.
See why 12 investors see Arlo Technologies as 32% undervalued.
Arlo Technologies anchors this narrative to a fair value estimate of $21.40 that uses an 8.84% discount rate and assumes a steady, subscription led model rather than a one off hardware cycle. That reference price implies a sizeable cushion to the current $14.47 share price. It also asks you to be comfortable with modest revenue growth and earnings that analysts expect to build gradually.
The same framework leans on a projected net profit margin of about 7.8% and a future P/E of roughly 66.9x, both of which are tied to a services heavy mix and recurring cash flows. Analysts in that camp see the hardware range, distribution partners and ADT alliance as feeders into higher margin plans, with Aloe Care Health and other add ons expanding the use cases beyond basic home security.
Underpinning all of this is the idea that Arlo Technologies is now valued more like a device linked platform than a pure electronics vendor. This is despite forecast revenue growth of around 4.7% a year and earnings growth of 1.3% a year sitting below broader US market assumptions. That tension between a premium multiple and slower headline growth is where each investor needs to decide whether the subscription story justifies the narrative fair value, or whether the current price already captures enough of that shift.
Result: Fair Value of $21.40 (UNDERVALUED)
Still, the Arlo Technologies story could change quickly if hardware pricing pressure erodes device margins or if subscription fatigue slows uptake on higher tier plans.
Find out about the key risks to this Arlo Technologies narrative.
Another View: Arlo Technologies Through The P/E Lens
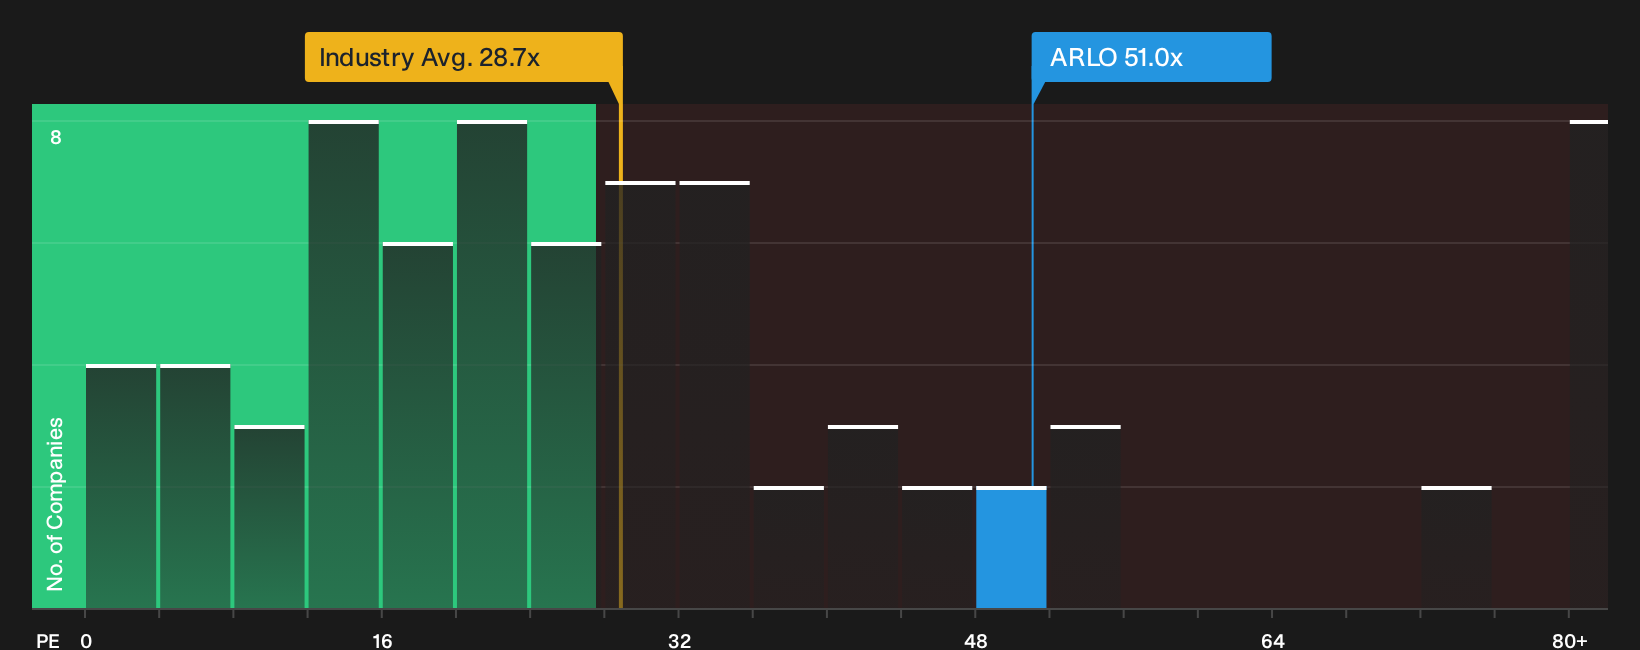
There is a very different message when Arlo Technologies is viewed through its P/E ratio. The stock trades around 51x earnings, compared with about 28.7x for the wider US Electronic industry and 23.8x for peers. The fair ratio sits nearer 18.5x, which points to meaningful valuation risk if sentiment cools.
High multiples can reflect quality, or simply high expectations that leave less room for mistakes. Which side of that line do you think Arlo Technologies is on today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Arlo Technologies so far. If you want to move quickly and build your own stance using both caution and optimism, start by weighing its 3 key rewards and 2 important warning signs
Looking For More Investment Ideas Beyond Arlo Technologies?
If you stop with Arlo Technologies, you only see one angle. Cast the net wider on Simply Wall Street and compare it with other potential opportunities.
- Target quality at a discount by scanning companies with solid fundamentals using the 36 high quality undervalued stocks.
- Prioritise resilience and peace of mind by reviewing businesses screened for stability through the 29 resilient stocks with low risk scores.
- Hunt for overlooked potential by checking companies with strong under the radar fundamentals in the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com