


- Jazz Pharmaceuticals reported updated Phase 3 HERIZON-GEA-01 data at ESMO 2026 showing Ziihera based regimens delivered longer median overall survival and reduced risk of death versus trastuzumab plus chemotherapy in first line HER2 positive gastroesophageal adenocarcinoma, reinforcing recent FDA approvals and inclusion in NCCN guidelines.
- The combination of stronger survival outcomes, preferred guideline status and two newly approved first line Ziihera regimens highlights a growing oncology franchise. Longer treatment duration and broader label coverage could materially influence Jazz Pharmaceuticals’ future revenue mix, capital allocation priorities and R&D focus.
- The focus now turns to how Jazz Pharmaceuticals’ investment narrative might shift given Ziihera’s updated survival benefit in HER2 positive GEA.
See how Jazz Pharmaceuticals’ Ziihera story compares with other late stage biotechs building oncology momentum by reviewing our curated list of 19 high quality undiscovered gems.
Jazz Pharmaceuticals Investment Narrative Recap
To own Jazz Pharmaceuticals, you need to be comfortable with a business that is gradually shifting from a mature sleep portfolio toward oncology and rare epilepsy. Ziihera’s updated HERIZON GEA data supports that pivot and reinforces a case that cancer assets can become a larger share of future cash generation while older products face generic and pricing pressure.
The most important near term catalyst now sits in execution on the newly approved Ziihera regimens, especially uptake in HER2 positive GEA. The biggest risk remains erosion in the legacy oxybate franchise and any setback in oncology or rare epilepsy programs that would slow the transition in its revenue mix.
The Ziihera HERIZON GEA update lands just before Jazz Pharmaceuticals reports Q3 2026 results after market on 2 November. Attention will likely cluster around early prescription trends for the two FDA approved first line GEA regimens and how management talks about treatment duration, access and physician adoption in light of the longer overall survival data.
On the same call, investors get another read on how much capital Jazz Pharmaceuticals is channeling into oncology and epilepsy relative to debt reduction and buybacks. Stronger HER2 positive GEA data may reinforce R&D and commercial spend behind Ziihera and could shape how management frames future catalysts across other HER2 driven tumors in the pipeline.
Jazz Pharmaceuticals' current analyst narrative points to US$5.7b in revenue and US$1.7b in earnings by 2029, based on forecasts that assume 7.4% yearly revenue growth and an earnings increase of about US$759m from US$940.8m today.
Uncover why Jazz Pharmaceuticals' fair value indicates a 36% potential upside to its current price that could narrow quickly.
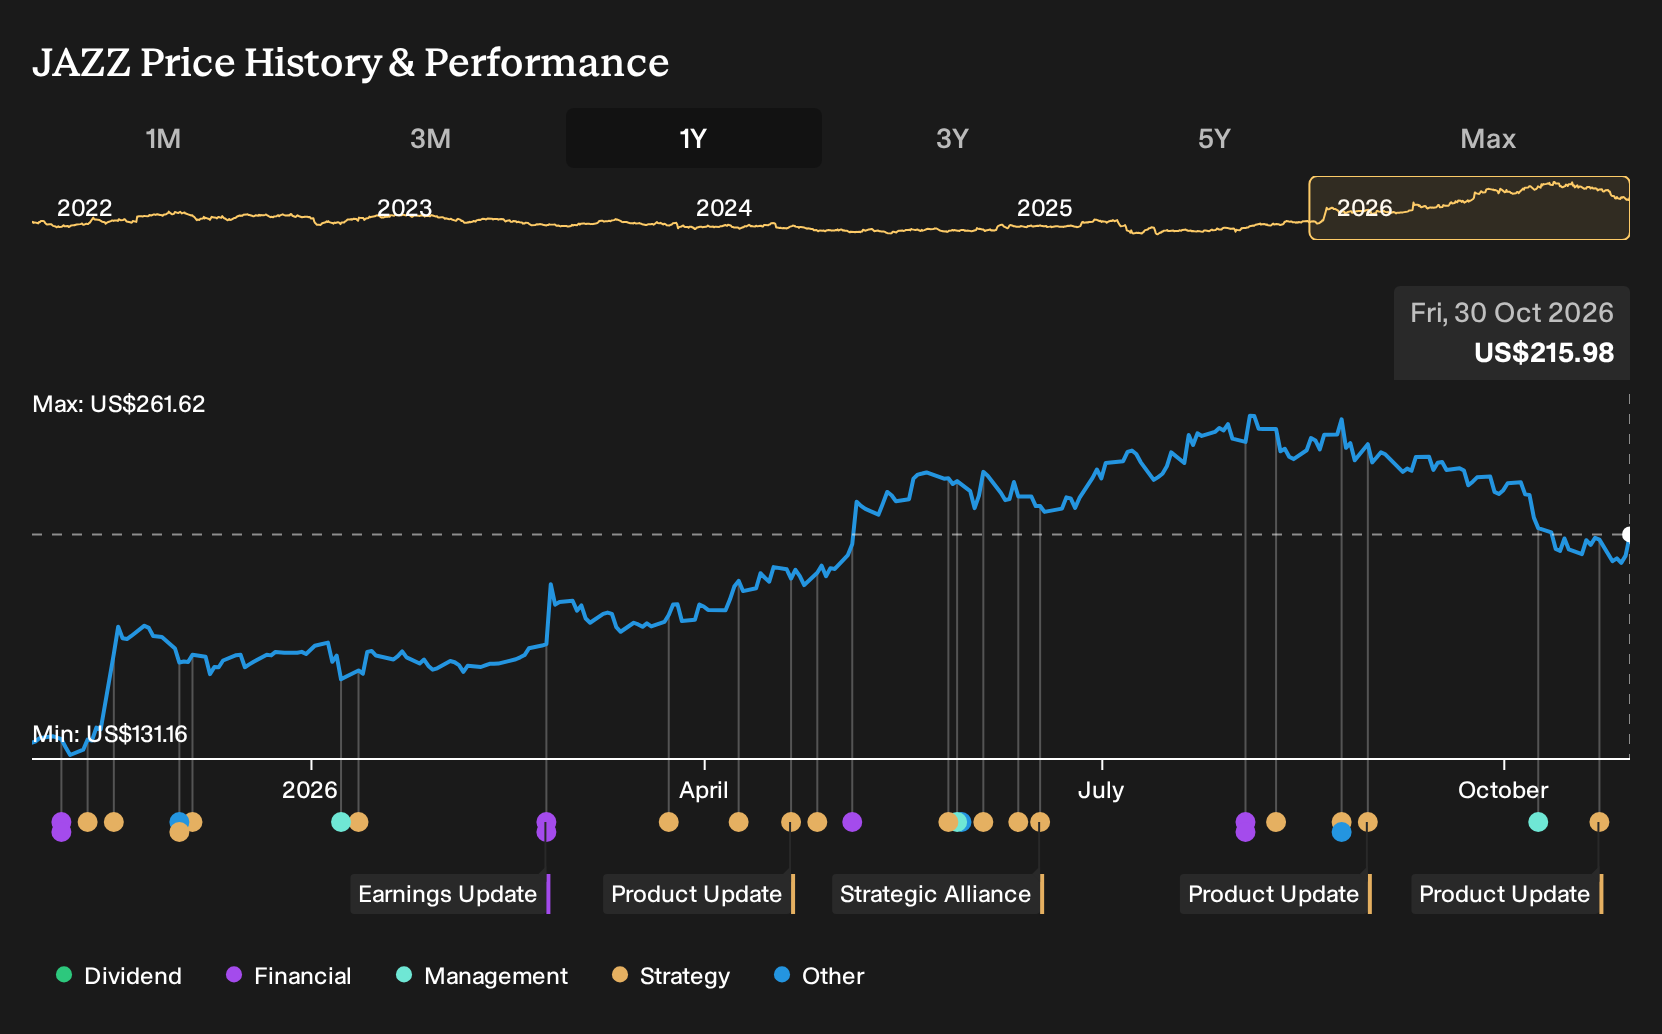
Exploring Other Perspectives
One alternate view puts Ziihera at the center of Jazz Pharmaceuticals’ story. The most optimistic analysts were already penciling in revenue of about US$6.6b and earnings of US$2.2b by 2029 before this HERIZON GEA update. That is a far brighter scenario than consensus, so explore both paths and decide which assumptions feel realistic to you.
Explore 3 other Jazz Pharmaceuticals fair value estimates, including one that suggests up to 173% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Jazz Pharmaceuticals research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Jazz Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jazz Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Jazz Pharmaceuticals?
If Jazz Pharmaceuticals has sharpened your thinking about risk, reward and time horizons, then broadening your watchlist across other opportunities can help you stress test that approach and avoid anchoring on a single story.
- If you want potential mispricing plus quality, start with a focused set of 36 high quality undervalued stocks that pair solid fundamentals with more modest expectations baked into prices.
- For investors who care most about balance sheet strength and resilience, a curated list of solid balance sheet and fundamentals (24 results) can surface businesses where debt and liquidity look more robust.
- If capital preservation and smoother returns matter most to you, consider a 29 resilient stocks with low risk scores that filters for companies with more measured risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com