


- First Mid Bancshares reported third quarter 2026 results, with net interest income of US$79.38 million, net income of US$33.3 million, and net charge offs of US$194,000, all compared with the prior year period.
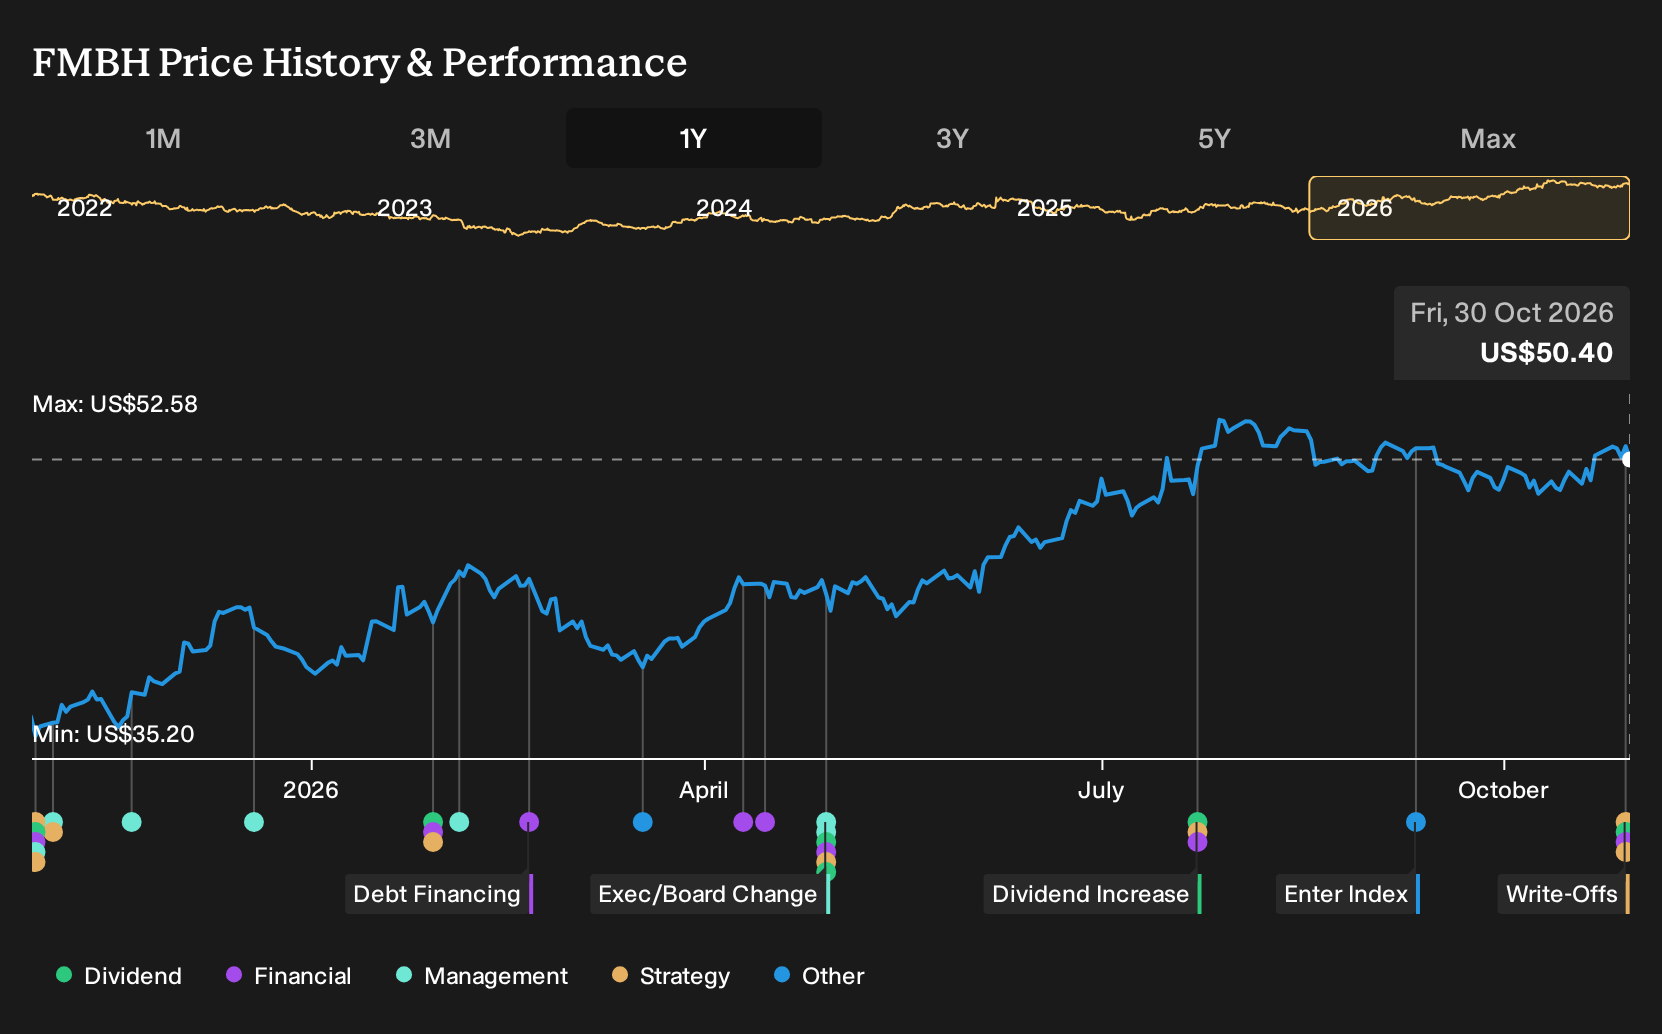
- The Board reaffirmed its regular quarterly dividend at US$0.26 per share, payable on December 1, 2026, signaling confidence alongside higher basic earnings per share from continuing operations of US$1.26 in the quarter.
- The focus now turns to how First Mid Bancshares' higher net interest income shapes the broader investment narrative around the bank's earnings profile.
What Is First Mid Bancshares' Investment Narrative?
To own First Mid Bancshares, you need to believe this is a conservative community bank that can keep turning solid net interest income into steady earnings while keeping credit issues contained. The latest quarter fits that idea. Net interest income of US$79.38 million and net income of US$33.3 million sit alongside very low net charge offs of US$194,000, which points to disciplined underwriting rather than a chase for volume at any cost.
In the short term, the key swing factors are margin resilience, credit quality and how management allocates capital. The affirmed US$0.26 dividend signals some confidence, although the track record is described as unstable and return on equity is characterized as low at 10.1%. With earnings growth flagged as positive but not high versus the broader market, the real question is whether this execution can offset the fact that revenue growth expectations are modest.
Even so, there is an underappreciated pressure point in First Mid Bancshares' story that could matter if ...
There's only one way to know the right time to buy, sell or hold First Mid Bancshares. Head to Simply Wall St's company report for the latest analysis of First Mid Bancshares's Fair Value.
Exploring Other Perspectives
Fair value estimates for First Mid Bancshares from the Simply Wall St Community span from about US$101 to more than US$83,000, across 2 individual assessments. This shows how far apart private investors can be. Those views were formed before the latest earnings and low net charge offs, so you may want to revisit several perspectives with fresh numbers in mind.
Explore another First Mid Bancshares fair value estimate, including one that suggests it could be worth just $101.46!
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your First Mid Bancshares research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First Mid Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Mid Bancshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond First Mid Bancshares?
If First Mid Bancshares has you thinking about balance sheet strength, dividends and risk, it can help to line it up against peers with similar traits. The Simply Wall St Screener lets you filter for exactly the type of businesses you want to research next.
- Prefer companies that combine sturdy finances with lower risk scores so you can focus on fundamentals instead of surprises? Then start with 29 resilient stocks with low risk scores.
- If you want potential value on your side and care about quality metrics backing that up, scan through 36 high quality undervalued stocks.
- For investors who like the idea of robust balance sheets alongside healthy underlying business strength, take a look at the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com